



ASX200 Afternoon Report May 23rd 2022
The ASX200 has given back over 50 points of early gains to be trading flat at 7145 at 3.00 pm Sydney time.
Share this:

The ASX200 has given back over 50 points of early gains to be trading flat at 7145 at 3.00 pm Sydney time.
The retreat came after Beijing reported a record number of Covid 19 cases sparking fears that the city will be forced into lockdown just as stifling restrictions in Shanghai begin to ease. And has soured hopes that the market might spring higher after the weekend's Federal Election, which removed the uncertainty of a hung parliament and raised hopes that the ALP might be able to mend fractured diplomatic relations with China.
A cut to China's prime lending rate on Friday to support its stuttering economy, behind a 6% surge in iron ore futures today and good gains for the Materials sector. Fortescue Metals (FMG) added 2.1% to $20.57. Mineral Resources (MIN) added 1.7% to $60.83, Rio Tinto (Rio) added 1.4% to to $109.88 and BHP Group (BHP) added 1.35% to $47.83.
Gains also for the Energy sector as the price of crude oil cemented a toe hold above $110 p/b. Santos (STO) added 1.1% to $8.17, Woodside Petroleum (WPL) added 0.42% to $28.89, Beach Energy (BPT) added 0.31% to $1.62.
Weighing on the index, a fall in the Heath Care Sectors led by heavyweight CSL, which fell 1.64% to $270.73, Resmed (RMD) fell 0.85% to $28.11, Virtus Health (VRT) fell 0.1% to $8.11. Going the other way, Cochlear (COH) added 1.6% to $219.18 and Ansell (ANN) added 1.75% to $27.33.
The Finance sector is also trading lower today led by ANZ which fell 0.9% to $25.27, National Australia Bank (NAB) fell 0.85% to $30.85. Westpac (WBC) fell 0.7% to $23.40, Commonwealth Bank (CBA) fell 0.4% to $104.21, and Macquarie (MQG) fell 0.83% to $179.92.
A mixed day for the IT sector. Novonix (NVX) fell 4.14% to $3.94, Afterpay owner Block (SQ2) fell 3.57% to $123.08, Sezzle (SZL) fell 2.5% to $0.58c. Zip (ZIP) fell 2.15% to $0.91c. Bringing some respectability to the IT Sector scoreboard, Megaport (MP1) added 2.56% to $7.42, Xero (XRO) added 2.1% to $90.35, and Appen (APX) added 1% to $6.79.
Lithium names have suffered another round of falls. Liontown Resources (LTR) fell 1.53% to $1.29, Pilbara Minerals (PLS) fell 1.25% to $2.82, Galan Lithium (GLN) fell 1.05% to $1.43, while Lake Resources (LKE) fell 1% to $1.50.
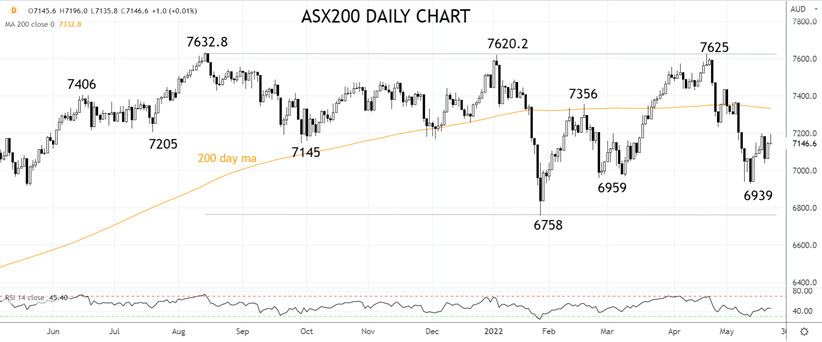
Over the past fortnight, the ASX200 has followed our road map to perfection. From our 7000/6950ish downside target, the rebound in the ASX200 last week reached our upside target at 7200. With the uncertainty of a hung parliament removed, I expect to see the ASX200 embark on a relief rally towards 7300/50, providing Wall Street behaves itself in the interim.
Source Tradingview. The figures stated are as of May 23rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 has given back over 50 points of early gains to be trading flat at 7145 at 3.00 pm Sydney time.
The retreat came after Beijing reported a record number of Covid 19 cases sparking fears that the city will be forced into lockdown just as stifling restrictions in Shanghai begin to ease. And has soured hopes that the market might spring higher after the weekend's Federal Election, which removed the uncertainty of a hung parliament and raised hopes that the ALP might be able to mend fractured diplomatic relations with China.
A cut to China's prime lending rate on Friday to support its stuttering economy, behind a 6% surge in iron ore futures today and good gains for the Materials sector. Fortescue Metals (FMG) added 2.1% to $20.57. Mineral Resources (MIN) added 1.7% to $60.83, Rio Tinto (Rio) added 1.4% to to $109.88 and BHP Group (BHP) added 1.35% to $47.83.
Gains also for the Energy sector as the price of crude oil cemented a toe hold above $110 p/b. Santos (STO) added 1.1% to $8.17, Woodside Petroleum (WPL) added 0.42% to $28.89, Beach Energy (BPT) added 0.31% to $1.62.
Weighing on the index, a fall in the Heath Care Sectors led by heavyweight CSL, which fell 1.64% to $270.73, Resmed (RMD) fell 0.85% to $28.11, Virtus Health (VRT) fell 0.1% to $8.11. Going the other way, Cochlear (COH) added 1.6% to $219.18 and Ansell (ANN) added 1.75% to $27.33.
The Finance sector is also trading lower today led by ANZ which fell 0.9% to $25.27, National Australia Bank (NAB) fell 0.85% to $30.85. Westpac (WBC) fell 0.7% to $23.40, Commonwealth Bank (CBA) fell 0.4% to $104.21, and Macquarie (MQG) fell 0.83% to $179.92.
A mixed day for the IT sector. Novonix (NVX) fell 4.14% to $3.94, Afterpay owner Block (SQ2) fell 3.57% to $123.08, Sezzle (SZL) fell 2.5% to $0.58c. Zip (ZIP) fell 2.15% to $0.91c. Bringing some respectability to the IT Sector scoreboard, Megaport (MP1) added 2.56% to $7.42, Xero (XRO) added 2.1% to $90.35, and Appen (APX) added 1% to $6.79.
Lithium names have suffered another round of falls. Liontown Resources (LTR) fell 1.53% to $1.29, Pilbara Minerals (PLS) fell 1.25% to $2.82, Galan Lithium (GLN) fell 1.05% to $1.43, while Lake Resources (LKE) fell 1% to $1.50.
Over the past fortnight, the ASX200 has followed our road map to perfection. From our 7000/6950ish downside target, the rebound in the ASX200 last week reached our upside target at 7200. With the uncertainty of a hung parliament removed, I expect to see the ASX200 embark on a relief rally towards 7300/50, providing Wall Street behaves itself in the interim.
Source Tradingview. The figures stated are as of May 23rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Cyclical stocks sniff out better times ahead
Different economies, different drivers, similar price action. The German DAX, ASX 200 and Russell 2000 are all hinting at a more optimistic view on the global economy.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.