






AUD/USD weekly outlook: 4-year low heading into US CPI and AU jobs
Another strong NFP report sent AUD/USD to a 4-year low on Friday, which was already under pressure following renewed bets of RBA cuts thanks to a soft CPI print for Australia. AU jobs and US CPI are the key data points for Aussie traders this week.
Share this:
- US data continues to drive sentiment for markets in general, AUD/USD is taking its directional cues from the USD and yuan
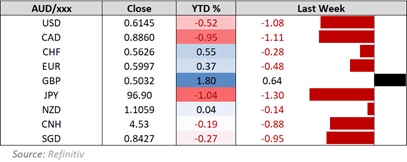
- The Australian dollar was lower against all but GBP last week, with AUD/USD hitting a 4-year low
- US CPI is the main economic event, while the Australian jobs report is the biggest domestic event
- RBA cash rate futures imply a 78% chance of a February cut from the RBA following softer timed-mean inflation
Another strong NFP report on Friday dealt another blow to dwindling hopes of Fed cuts and sent AUD/USD to a 4-year low. Markets were barely pricing in two Fed cuts this year ahead of the NFP report. And with evidence of inflationary pressures rising before Trump’s returns to the Whitehouse, no cuts in 2025 is also plausible. And that means incoming US data remains the key driver for sentiment in general.
Most of the key data points this week are for December, the biggest of which will be US CPI released at 00:30 Thursday (Sydney time). Core inflation is expected to soften to 0.2% m/m, which means a print of 0.3% or higher could spell further trouble for the Aussie has traders will likely continue to bid a strong USD and offload bonds to send yields higher.
Several FOMC and Fed members hit the wires this week, but it is difficult to see how they could provide a convincingly dovish tone given the strength of the US economy and uncertainty surrounding Trump’s policies. But in simple terms, strong US data is likely to keep AUD/USD under selling pressure.
Australia’s employment report on Thursday is the biggest domestic event on the calendar. And given the excitement of a softer trimmed-mean figure last week (which is now 0.2% points above the RBA’s 2-3% band), even small signs of weakness have the potential to be amplified by Aussie bears. But unless Australian businesses culled staff for Christmas, I suspect another robust set of figures to arrive. Still, RBA cash rate futures now imply a 78% chance of a February cut, but we really need to see a softer quarterly CPI report in a couple of weeks before we can be sure a Feb cut is a given.
China’s Q4 GDP report lands on Friday alongside the usual retail sales, industrial production, unemployment and investment figures. They are of course worthy of a look, but traders are likely to pay greater attention to incoming leading indicators to see if or when freshly-announced stimulus is making an impact.
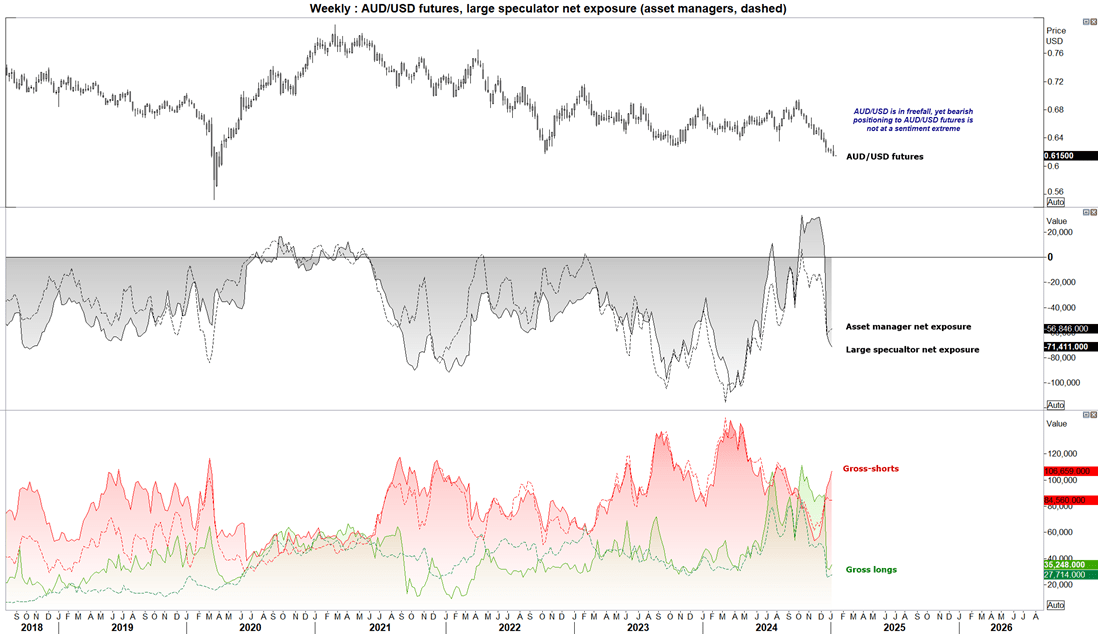
AUD/USD futures – market positioning from the COT report:
The data delays due to public holidays over the festive season means that we’re actually looking at how traders were positioned in the final week of 2024. The latest batch of data will be released overnight, but for now this makes a decent recap.
- Large speculators increased their net-short exposure to AUD/USD futures to a 33-week high
- While asset managers trimmed their net-short exposure slightly by -1.4k contracts, they were net-short for an 11th week and around their most bearish level in just over 6 months
AUD/USD technical analysis
Over the past 14 weeks, AUD/USD has fallen 11 and risen just three. Traditional metrics could suggest the market is oversold, but macro moves like the one we’re witnessing cares little for such measures. And that fact that we saw a bearish outside candle form at a 4-year low on week 14 is a testament to that.
If the implied volatility levels are correct, AUD/USD could be in the upper 50s in four weeks. What would make this unique is that we’re yet to see the Aussie fall below 60c without a shock to the system such as Covid, the GFC or the Nasdaq bubble bursting.
The daily trend is firmly bearish and one that likely favours bears fading into minor rallies, while prices remain beneath 63c. A test of 61c this week is not out of the question, a break beneath which brings the 2008 (GFC) and April 2020 low into focus for bears.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

Australian Dollar Forecast: AUD/USD Four-Week Slide Nears Critical Uptrend Support 9 29 2026
Aussie momentum has deteriorated sharply into quarter-end, with inflation, Core PCE and NFP on tap as AUD/USD closes in on a pivotal technical threshold.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.