



DAX Nears Highs; BoE Rate Cut & Amazon Earnings Ahead
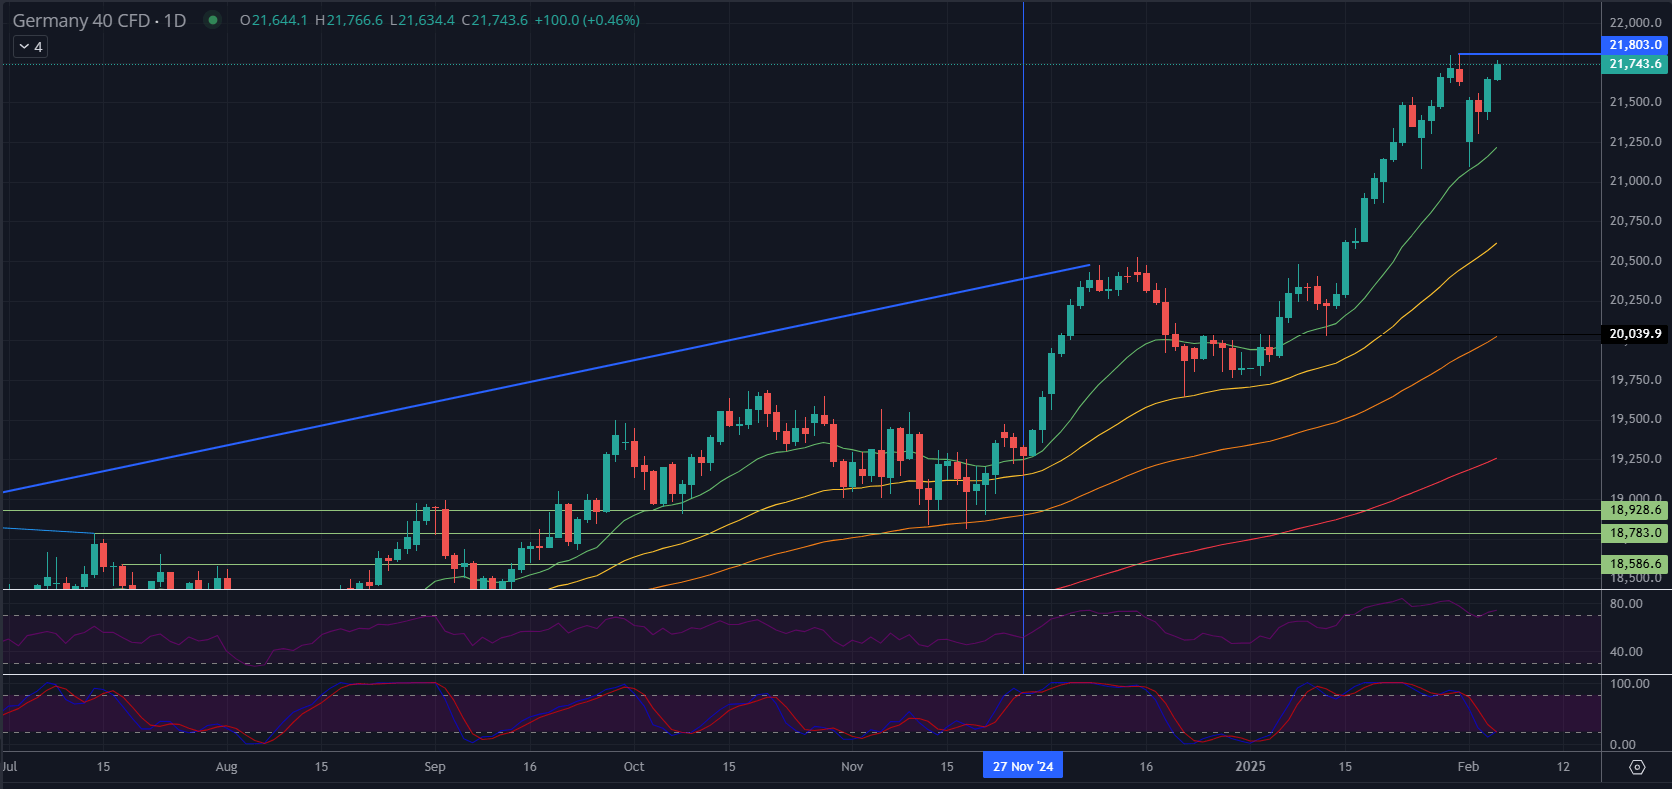
The DAX maintains bullish momentum, nearing 21,803, as global markets stabilize. Investors focus on today’s BoE rate decision, expected at 4.50%, and U.S. jobless claims. Oil rebounds after Saudi price hikes, while gold edges toward record highs. The U.S. labor market data and Amazon earnings could set the next market move.
Share this:
Market Update – 6.2.2024
Market Overview
Global markets are exhibiting cautious optimism as concerns over aggressive trade retaliation from China ease. The stability of the yuan and a rally in European healthcare stocks, driven by Novo Nordisk's strong drug sales, have provided additional support.
Commodity markets have seen oil prices rebound following Saudi Arabia’s price hikes, signaling confidence in demand. Meanwhile, gold continues to edge closer to record highs, reflecting increased demand as a hedge against economic uncertainties.
Regional Market Performance
Asian shares advanced, following Wall Street’s positive momentum:
- Nikkei 225 (Japan): +0.5%
- S&P/ASX 200 (Australia): +1.2%
- Kospi (South Korea): +0.7%
- Hang Seng (Hong Kong): +0.8%
- Shanghai Composite (China): +1.0%
In the U.S., the major indices also posted gains:
- S&P 500: +0.4%
- Dow Jones Industrial Average: +0.7%
- Nasdaq Composite: +0.2%
Strong earnings from Mattel and Amgen contributed to these gains.
Commodities Update
- Oil: Prices rebounded after Saudi Arabia announced price hikes, suggesting a positive demand outlook.
- Gold: Nearing record highs, driven by rising safe-haven demand amid global economic uncertainties.
DAX Technical Analysis 1 Day
The Germany 40 (DAX) chart shows continued bullish momentum, with the price approaching its recent high at 21,803. The price remains well above key moving averages, reinforcing the strong uptrend. The short-term moving averages, such as the 20 EMA, continue to provide dynamic support, keeping the bullish structure intact.
The RSI is elevated but not yet in extreme overbought territory, suggesting there is still room for further upside. However, the Stochastic RSI is at higher levels, indicating that momentum could slow down in the short term, leading to potential consolidation or a minor pullback before another push higher.
Key support levels to watch are near 21,400 and 20,750, where moving averages provide additional buying interest. A breakout above 21,803 could trigger a continuation of the uptrend, while failure to hold support levels may lead to a deeper retracement toward the 20,000 zone.
Key Economic Events & Market Implications
Bank of England Interest Rate Decision (12:00)
- Expected: 4.50%
- Previous: 4.75%
- Impact: The BoE is expected to cut rates by 25 basis points, marking the first reduction since 2020. This move aims to address sluggish economic growth and persistent inflation (currently at 2.5%). Markets have priced in over 80 basis points of easing by year-end, but uncertainty remains regarding policymakers’ stance.
Potential Market Effects:
- Economic Growth: Lower interest rates can reduce borrowing costs for businesses and consumers, potentially leading to increased spending and investment, boosting corporate earnings and stock prices.
- Sector-Specific Impacts:
- Financials & Banks: Might experience lower net interest margins due to reduced lending rates, exerting downward pressure on stock prices.
- Consumer Discretionary & Industrials: Could benefit as cheaper loans encourage consumer spending and business investment.
- Currency Impact: Lower rates may weaken GBP, potentially benefiting UK exporters but increasing costs for companies reliant on imports.
- Inflation Considerations: While aimed at stimulating the economy, concerns about rising inflation (currently projected to increase) could dampen purchasing power and market optimism.
U.S. Initial Jobless Claims (13:30)
- Expected: 214K
- Previous: 207K
- Impact: A rise in unemployment claims suggests a weakening labor market. If the actual figure exceeds expectations, concerns about economic slowdown may weigh on equities. A lower-than-expected print, however, could reinforce confidence in the labor market and support risk assets.
Speeches & Market Sentiment Drivers
- 17:00 GMT – EUR: German Buba Balz speaks on monetary policy and financial stability.
- 19:30 GMT – USD: Fed Governor Christopher Waller’s remarks could provide insights into future Federal Reserve policy.
- 20:30 GMT – USD: FOMC Member Mary Daly speaks, influencing market expectations regarding U.S. interest rates.
- 21:05 GMT – GBP: BoE Governor Bailey’s speech may provide key signals on the UK’s monetary policy direction.
Earnings Spotlight – Amazon - Aftermarket
Amazon is set to release earnings after market close. The company has exceeded EPS estimates in 7 of the last 8 quarters, making this a closely watched report that could influence broader market sentiment. Average expected move after earnings 8%.
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

DAX Climbs After Fed Move, Eyes Break Above 26,000 Resistance
The DAX has opened significantly higher following the Federal Reserve's delivery of its first interest rate hike since 2023. Although the Fed signaled further tightening, the market reaction was surprisingly positive, as much of the hawkish expectation had already been priced in. Attention now shifts to the 25,900–26,000 point range, which will likely determine whether the current recovery evolves into a new upward wave or remains merely a short-covering rally.

USD/JPY, DAX Forecast: Two trades to watch 150926
USD/JPY rises as U.S. Treasury yields rise above 5%. DAX slumps as bond rout continues and oil prices surge.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.