



DAX Climbs After Fed Move, Eyes Break Above 26,000 Resistance
The DAX has opened significantly higher following the Federal Reserve's delivery of its first interest rate hike since 2023. Although the Fed signaled further tightening, the market reaction was surprisingly positive, as much of the hawkish expectation had already been priced in. Attention now shifts to the 25,900–26,000 point range, which will likely determine whether the current recovery evolves into a new upward wave or remains merely a short-covering rally.
Share this:
DAX Market Letter: Fed interest rate hike provides new tailwind
Thursday, September 17, 2026
DAX starts with a significant gain
The DAX opened significantly stronger on Thursday following yesterday's Fed decision. Wednesday's Xetra closing price was 25,537.75 points , a gain of 0.53%. At the start of today's trading, the DAX is up 0.6% at approximately 25,695 points .
The main impetus comes from the USA: The Fed raised the key interest rate yesterday by 25 basis points to 3.75–4.00% – the first interest rate hike since 2023. At the same time, the new Fed leadership under Kevin Warsh hinted at further tightening.
The market's initial reaction has been surprisingly constructive. Apparently, some of the hawkish Fed expectations were already priced in.
Yesterday's winners and losers
Wednesday was generally positive for the DAX, although with significant sector rotation.
DAX leader
|
share |
Wednesday |
|
Siemens Energy |
+3.10% |
|
RWE |
+2.81% |
|
Hochtief |
+2.59% |
|
Symrise |
+2.30% |
|
adidas |
+1.94% |
DAX laggards
|
share |
Wednesday |
|
Volkswagen Vz. |
-2.64% |
|
Mercedes Benz |
-2.57% |
|
Commerzbank |
-2.40% |
|
Rheinmetall |
-1.52% |
|
Siemens Healthineers |
-1.31% |
The strength of Siemens Energy and RWE is striking , while German automakers were once again under pressure. The weakness of Volkswagen and Mercedes thus remains a drag on market breadth.
What's happening today
The market movement is broad-based again today. In the current DAX indication, Siemens Energy (+3.50%), Continental (+2.83%), and RWE (+2.57%) are leading the way . On the losing side are Volkswagen (-2.12%), Mercedes-Benz (-2.04%), and Commerzbank (-1.58%) .
This means that the pattern from Wednesday continues initially: energy and industrial stocks are leading, while automotive and some financial stocks are lagging behind.
The Fed provides the most important impetus
The Fed raised its key interest rate yesterday to 3.75–4.00% . At the same time, projections signaled a further possible rate hike later this year. The median of the Fed projection for the end of 2026 rose to approximately 4.1% .
This explains the strength of the US dollar and the renewed rise in short-term Treasury yields.
For the DAX, this is a double-edged sword:
On a positive note, the Fed is signaling its intention to combat inflation. A credible decline in inflation could later allow for lower interest rates.
On the downside: Higher US interest rates mean higher global financing costs and can limit the valuation of stocks.
Important appointments today
Today's calendar remains extremely full.
11:00 AM – Eurozone Inflation
The final August data on eurozone inflation will be published. Total inflation is expected to be 3.3% and core inflation 2.4% year-on-year.
1 p.m. – Bank of England
The Bank of England decides on the UK's key interest rates. The consensus is 3.75% , so it remains unchanged.
2:15 p.m. – ECB Chief Economist Philip Lane
Philip Lane is speaking at the ECB's Jean Monnet Lecture. Following the ECB's recent interest rate hike to 2.50%, statements regarding future inflation and interest rate policies are particularly relevant.
2:30 p.m. – Building permits and construction starts
Among other things, building permits and construction starts for August are expected from the USA . Approximately 1.315 million building permits and 1.305 million construction starts are anticipated on an annualized basis.
In addition, the market remains heavily focused today on the repercussions of the Fed's decision.
2:30 PM – US follow-up applications for unemployment benefits
Among the data coming from the US are the continuing claims for unemployment benefits for August. Around 1.785 million are expected. Also of importance – following yesterday's statement by Kevin Warsh regarding the robustness of the labor market – is that any major deviation could come as a surprise.
In addition, the market remains heavily focused today on the repercussions of the Fed's decision.
Technical analysis
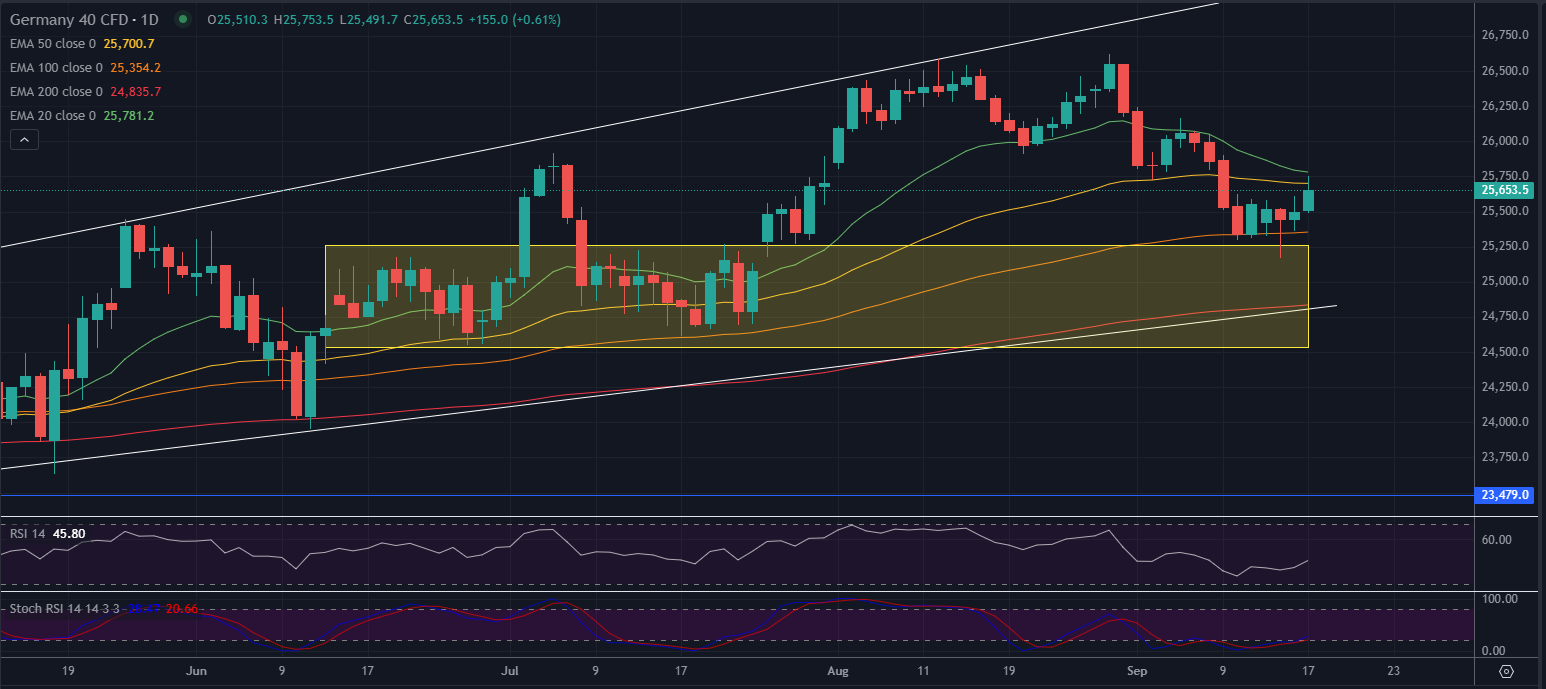
The DAX managed to hold above its important medium-term moving averages yesterday. Closing at 25,537 points, it remained above the 100-day moving average .
Current technical data for the DAX chart show:
- Pivot: 25,834
- Resistance 1: 25,800
- Resistance 2: 25,919
- Resistance 3: 26,157
- Support 1: 25,364
- Support 2: 25,192
- Support 3: 24,853
- 50-day moving average: approx. 25,703
- 200-day moving average: approx. 24,853
- Stoch RSI: approx. 20.8 – near oversold territory
Scenario 1: Outbreak
If the DAX can sustainably break through the 25,900–26,000 point zone , the short-term technical picture would improve further. Above 26,000 points, the next significant resistance level would then be in the 26,500–26,600 range , near the previous record high of 26,618.70 points.
Scenario 2: False Outbreak
If the index fails again at 25,900–26,000 points, the first relevant support zone lies at approximately 25,700–25,750 points . Below that, the 50/200-day zone around 25,700–24,850 comes into focus.
Scenario 3: Return below 25,500
A renewed drop below 25,500 points would significantly weaken today's recovery momentum. A retest of the recent lows would then be possible.
Conclusion
The DAX starts today with a clear technical advantage, but the movement is not yet confirmed.
The 25,900–26,000 point range represents the most important short-term resistance zone. A sustained breakout would improve the technical picture and refocus attention on the record high.
At the same time, the RSI is already close to 70. After the strong rise on Thursday morning, the risk of a short-term pullback is therefore increasing.
On a macro level , the Fed, oil, bond yields and European inflation remain the crucial variables.
Today's trading will therefore depend primarily on whether the DAX can overcome the 26,000-point mark or whether the initial reaction to the Fed decision merely leads to short-term short covering.
Technical bias: positive in the short term, but close to a key resistance zone.
By Philip J Papageorgiou - Head of Investment Research
Find him on X (x twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.

EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.