


ECB Day: What DAX investors need to know today
Earnings season has taken a back seat for now. Instead, rising oil prices, higher bond yields, and renewed inflation concerns are shaping market sentiment. Brent crude is trading above $100 per barrel again, while the ECB is poised for another interest rate hike. Investors are now focusing on Christine Lagarde's press conference and today's US producer prices for clues about the future direction of interest rates on both sides of the Atlantic.
Share this:
DAX Market Letter: ECB, oil and US inflation dominate trading
Thursday, September 10, 2026
DAX under pressure – focus on the ECB
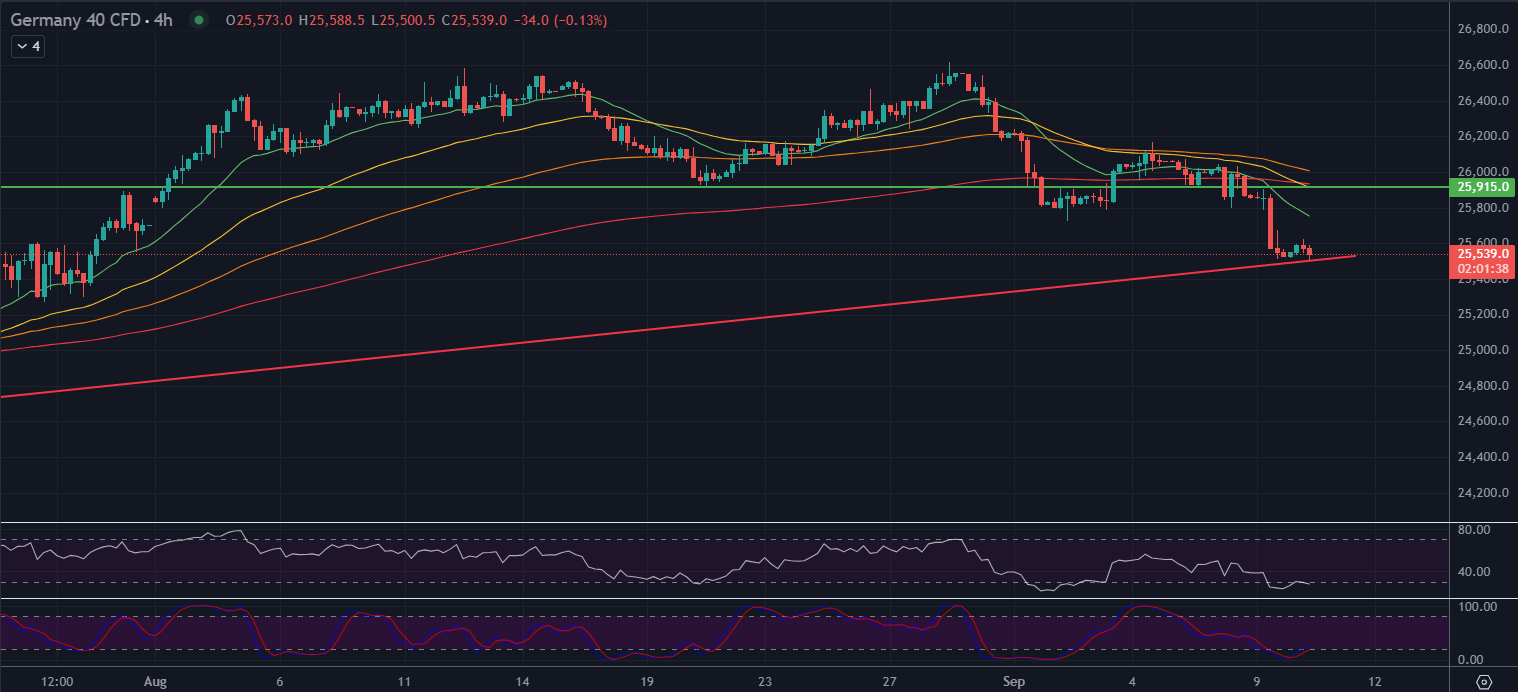
The DAX is currently trading significantly below its record high of recent weeks. The decisive factor weighing on the index is no longer corporate earnings reports, but rather the combination of rising oil prices, higher bond yields, and increasing inflationary pressure .
Brent crude has risen back above the $100 per barrel mark . At the same time, the yield on ten-year US Treasury bonds is near 4.85% . This is worsening the environment for European stocks.
German inflation confirms increased price pressure
The German inflation data published today offers no initial relief.
Consumer prices rose by 2.9% in August compared to the previous year , exactly in line with expectations.
Furthermore, the ECB will decide on its future monetary policy today. The market expects an interest rate hike of 25 basis points to 2.65% . However, the decisive factor will be less the interest rate hike itself than the subsequent communication from ECB President Christine Lagarde.
What is crucial for the DAX
A hawkish Lagarde – that is, an indication of further interest rate hikes – would be negative for the DAX.
Conversely, a wait-and-see approach could trigger a recovery, especially if the ECB emphasizes that future decisions will depend on the data and the development of energy prices.
Oil price becomes the central risk
The rise of Brent crude above $100 is now a serious macroeconomic factor.
The conflict in the Middle East is straining energy supplies and leading to higher transport and production costs. At the same time, this is raising inflation expectations. Brent crude has risen above $100 for the first time since July.
This creates an unfavorable cycle for the DAX:
Higher oil prices → higher inflation → less room for interest rate cuts → higher yields → lower stock valuations.
Highly valued growth and technology stocks are particularly vulnerable.
In contrast, energy companies and, to some extent, banks are the beneficiaries.
DAX stocks in focus
Yesterday's trading was characterized by widespread risk aversion. Siemens, with a decline of almost 3%, was among the weaker DAX stocks. Deutsche Börse, Airbus, and Symrise also suffered significant losses.
Today, interest rate-sensitive stocks are likely to be in particular focus.
SAP: The stock remains one of the most important drivers of the DAX. Rising yields are a short-term drag on its valuation.
Siemens: Following Wednesday's significant decline, the stock is under technical pressure. Due to its high index weighting, this development is also relevant for the DAX.
Deutsche Bank / Commerzbank: Higher interest rates can generally support interest income. The banking sector could therefore perform relatively better than highly valued technology stocks.
Rheinmetall: Geopolitical tensions remain a structural driver of the share price, while at the same time the stock is particularly vulnerable to profit-taking after the strong long-term rally.
US PPI this afternoon
The next big impetus will come from the USA.
The US Producer Price Index for August will be released at 2:30 PM CEST . A year-on-year increase in the overall PPI rate of 4.7% to approximately 5.2% is currently expected ; the monthly forecast is for a rise of around +0.2% .
This is currently the most important short-term US catalyst.
Three possible reactions
PPI significantly higher than expected:
US yields rise, expectations for interest rate cuts/raises shift further towards a more restrictive Fed. Negative for the Nasdaq and DAX.
PPI roughly in consensus:
The market is likely to focus more on the ECB press conference and tomorrow's US CPI.
PPI significantly lower:
Relief in inflation expectations, falling yields and potential rebound in technology stocks.
Tomorrow's US CPI is even more important, however, because it directly influences Fed expectations. Markets currently see an increased probability of a Fed interest rate hike at the meeting on September 15th/16th.
Trading plan for the DAX
After reaching a record high, the DAX is now in a clear risk-off phase .
Three areas are crucial today:
1. Oil: If Brent remains above $100, inflationary pressure will persist.
2. Yields: A further increase in the US 10Y yield above the 4.85% range would be an additional warning signal.
3. ECB: Lagarde's press conference is likely to determine the direction of the European interest rate market.
Conclusion
The short-term bias remains bearish to neutral . The DAX continues to have fundamental support from solid corporate profits and the structural strength of major German companies. However, the short-term macroeconomic environment has clearly deteriorated.
Today, the decisive trigger is not the record high, but the market's reaction to the ECB, oil, and US PPI.
A decline in oil prices and falling yields could quickly trigger a technical rebound. However, if oil remains above $100 and yields stay high, the pressure on the DAX is likely to persist.
Von Philip J Papageorgiou - Leiter der Marktforschung
Finde ihn auf X (x twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.