


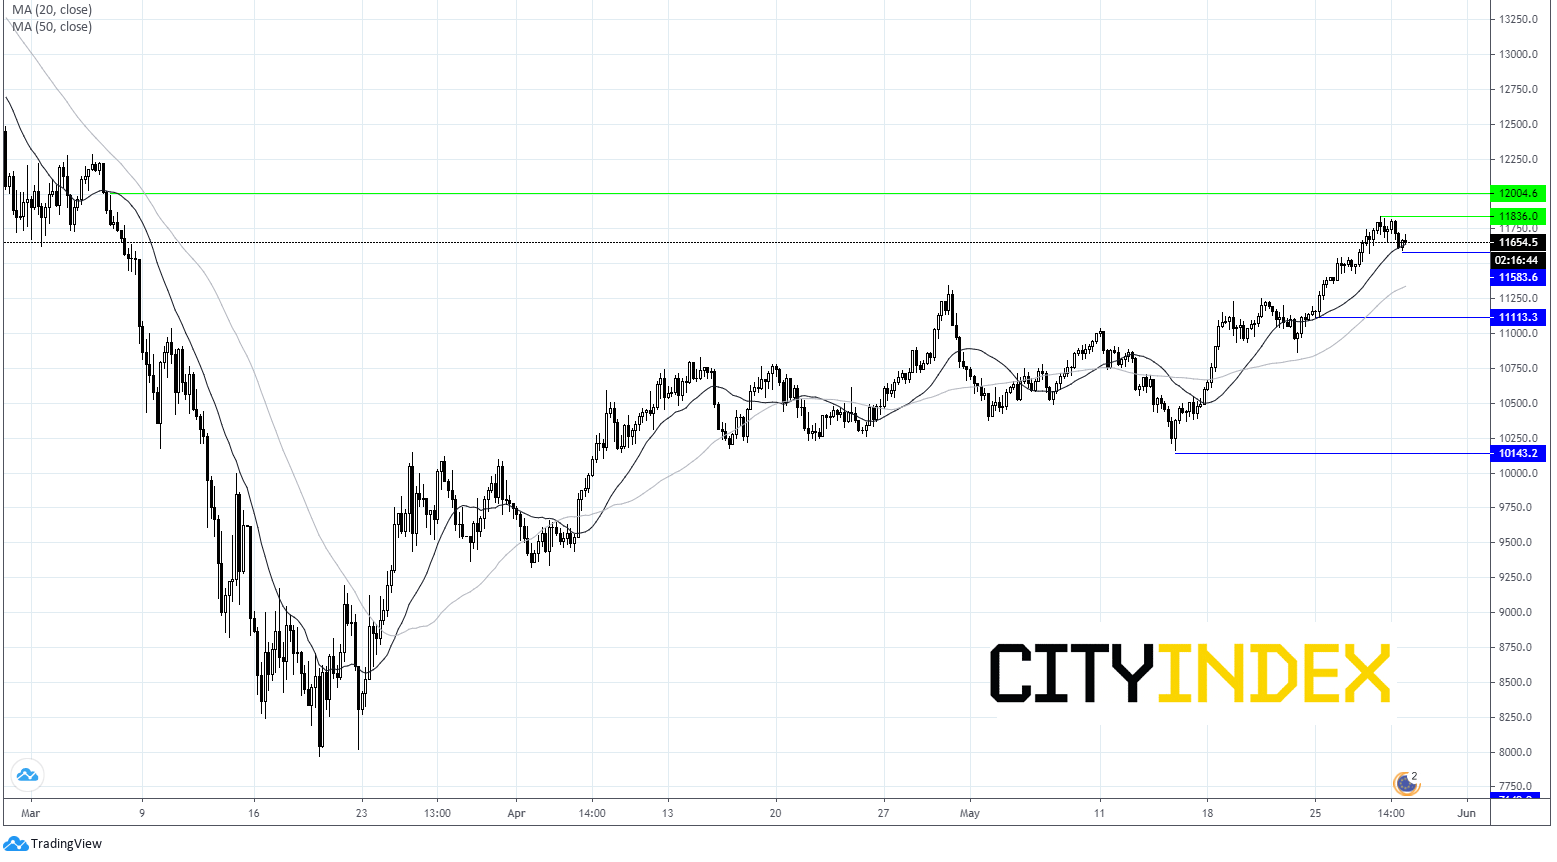


Europe Points Lower Ahead of Trumps Response
With tensions between US - Sino now at boiling point, traders are no longer able to brush off the spat
Share this:

After three days of gains, European bourses are pointing to a softer start. Reopening optimism had overshadowed simmering US – China tensions across the week, despite several signals that relations were deteriorating. However, with tensions between the two powers now at boiling point, traders are no longer able to brush off the spat.
Risk sentiment drops
Risk off is dominating as investors look ahead to Trump’s response, provoked by China’s crackdown on civil liberties in Hong Kong, Asia’s financial hub. Stocks on Wall Street reversed on the announcement of Trump’s press conference, finishing the day lower. Asia also traded on the back foot, with Europe expected to follow suit as demand for riskier assets take a hit. Safe haven gold is building on gains from the previous session as tensions between the US and China mount, although the US Dollar is slipping lower, decoupling from falling stocks.
Risk off is dominating as investors look ahead to Trump’s response, provoked by China’s crackdown on civil liberties in Hong Kong, Asia’s financial hub. Stocks on Wall Street reversed on the announcement of Trump’s press conference, finishing the day lower. Asia also traded on the back foot, with Europe expected to follow suit as demand for riskier assets take a hit. Safe haven gold is building on gains from the previous session as tensions between the US and China mount, although the US Dollar is slipping lower, decoupling from falling stocks.
The clash over Hong Kong joins a list of other grievances between the world’s largest economies, including Huawei, human rights in Xinjiang, trade and currency wars.
Trump could announce sanctions on several Chinese individuals and remove Hong Kong’s special trade status or take other measures. It appears that the markets have found some solace in the fact that the trade deal remains intact, for now. The fear is that the US – China spat could hamper a fragile economic recovery from the coronavirus crisis.
Trump could announce sanctions on several Chinese individuals and remove Hong Kong’s special trade status or take other measures. It appears that the markets have found some solace in the fact that the trade deal remains intact, for now. The fear is that the US – China spat could hamper a fragile economic recovery from the coronavirus crisis.
In addition to Trump’s press conference, Fed Chair Jerome will give a speech, however given his numerous appearances over the past few weeks, his impact on the market is expected to be limited. Other indicators for April, such as personal income and spending will also be in focus.
Germany keeps spending
Signs that Germany kept spending in lockdown is boosting the EUR. German retail sales are significantly better than forecast. Retail sales in Europe’s largest economy dropped “just” -5.3% month on month in April, much better than the -12% decline forecast. Whilst the drop is a touch down from March’s -4% fall, this is expected to be the bottom. The fact that the bottom for retail sales isn’t as bad as feared has boosted he EUR which is trading above $1.11.
Signs that Germany kept spending in lockdown is boosting the EUR. German retail sales are significantly better than forecast. Retail sales in Europe’s largest economy dropped “just” -5.3% month on month in April, much better than the -12% decline forecast. Whilst the drop is a touch down from March’s -4% fall, this is expected to be the bottom. The fact that the bottom for retail sales isn’t as bad as feared has boosted he EUR which is trading above $1.11.
EZ CPI
Attention will now turn to Eurozone inflation figures. The German retail sales inspired push higher for the euro could be short lived. Expectations are for Eurozone inflation to increase at just 0.2% month on month, whilst annual inflation of just 0.8% could drag on demand for the common currency, especially ahead of next week’s ECB meeting.
Dax Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.