



European Open: Multiple CPI reports and Fed speakers on the docket
It’s another busy day for the calendar which kicks off with UK inflation at 07:00 GMT.
Share this:


Asian Indices:
- Australia's ASX 200 index fell by -50.5 points (-0.68%) and currently trades at 7,369.90
- Japan's Nikkei 225 index has fallen by -79.55 points (-0.31%) and currently trades at 25,360.34
- Hong Kong's Hang Seng index has fallen by -83.9 points (-0.33%) and currently trades at 25,629.88
- China's A50 Index has fallen by -29.94 points (-0.19%) and currently trades at 15,577.07
UK and Europe:
- UK's FTSE 100 futures are currently down -28.5 points (-0.39%), the cash market is currently estimated to open at 7,298.47
- Euro STOXX 50 futures are currently down -3 points (-0.07%), the cash market is currently estimated to open at 4,398.49
- Germany's DAX futures are currently down -29 points (-0.18%), the cash market is currently estimated to open at 16,218.86
US Futures:
- DJI futures are currently up 54.77 points (0.15%)
- S&P 500 futures are currently down -12.25 points (-0.08%)
- Nasdaq 100 futures are currently down -2.25 points (-0.05%)
Decision time for the FTSE 100

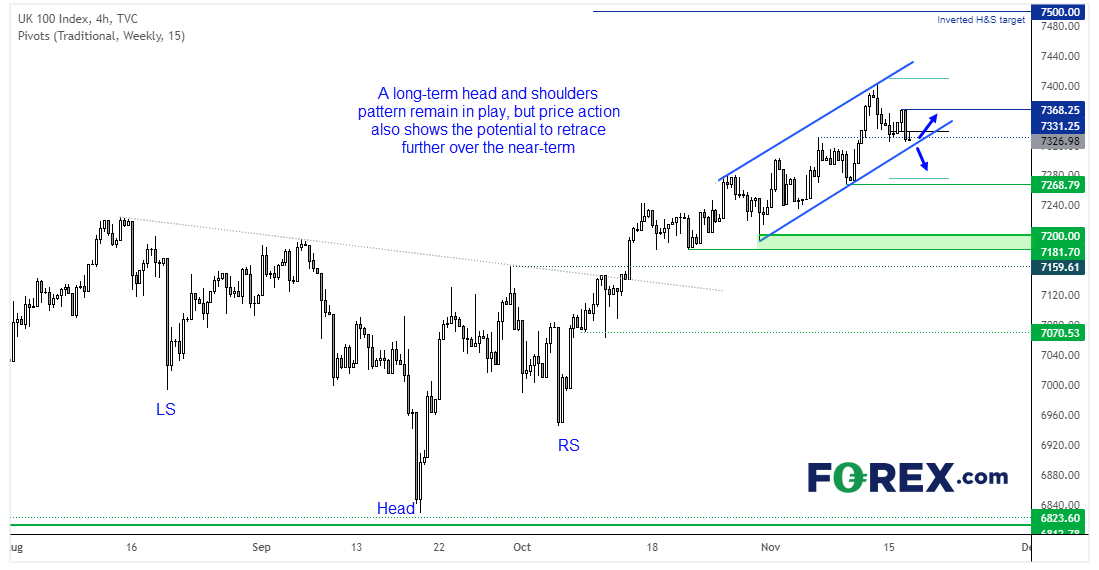
The FTSE 100 remains in an uptrend on the daily chart and an inverted head and shoulders pattern remains in play, which projects a target around 7500. Prices remain in a bullish channel on the four-hour chart, yet a rather aggressive lower high on formed yesterday to suggest a minor change in trend. And a break of the lower trendline witches our bias to bearish over the near-term. Take note that prices are below the weekly pivot point and the W1 support is just above the 7628 lows, making it a potential target for bulls. Should the trendline hold as support then a break above 7368 assumes bullish continuation.
FTSE 350: 4203.45 (-0.34%) 16 November 2021
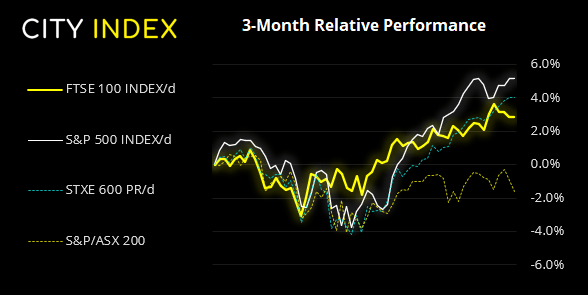
- 128 (36.47%) stocks advanced and 212 (60.40%) declined
- 18 stocks rose to a new 52-week high, 3 fell to new lows
- 62.39% of stocks closed above their 200-day average
- 61.25% of stocks closed above their 50-day average
- 20.23% of stocks closed above their 20-day average
Outperformers:
- + 16.77%-Restaurant Group PLC(RTN.L)
- + 7.12%-HomeServe PLC(HSV.L)
- + 5.13%-Harbour Energy PLC(HBR.L)
Underperformers:
- ·-5.81%-Genuit Group PLC(GENG.L)
- ·-5.70%-Cineworld Group PLC(CINE.L)
- ·-5.01%-Reach PLC(RCH.L)
Equity markets across Asia mostly lower
Asian equities were mostly lower, with the KOSPI 200 leading the pack lower as covid cases in South Korea rose and reignited concerns over it spreading to other parts of the region. Yet shares in China remained buoyant thanks to stoner-than-expected retail sales and industrial output yesterday, coupled with the amicable meeting between Xi and Biden.
The ASX200 was dragged lower by CBA’s earnings miss, with the stock falling over 8% and below $100. The index probed the September trend support level before closing on it, and will no doubt be a pivotal level for tomorrow.
And Japan’s shares were mostly lower after exports slumped to an 8-month low whilst machinery orders also disappointed. As this follows on from a weak (and quite negative) growth report thing are not looking great in Japan for Q4 right now.
Debt ceiling and Fed Chair back in the spotlight
US Treasury Secretary Lady Yellen wanted that the US could breach its debt limit by December the 15th. Whilst traders were aware that the can had been kicked down the road until December, it serves as a timely reminder none the less.
Separately, it was reported that Joe Biden could confirm his pick for the Fed chai by as early as this week. Whilst odds still favour Jerome Powell to cling on to the position, Brainard is still in with a chance so take nothing for granted. Even if they are both very dovish.
Multiple inflation reports and Fed speakers on today’s docket
If there was any doubt after yesterday’s employment set report over whether the BOE will raise rates on the 16th December, then a strong inflation print today should put those concerns to rest. CPI is expected to rise to 3.9% from 3.1% and core PCI is expected to rise to 3% from 2.9%. Perhaps there’ll be a bit of a wobble should inflation undershoot these expectations, but it would probably have to miss by a wide margin to completely reverse the market’s expectation of no hike this year, and that would no doubt prompt the greater volatile reaction.
CPI data is also released at 10:00 for Europe and Canada at 13:30, although there are no expectations for a hike form either respective central bank. Building permit and housing start data is also released for the US at 13:30.
We also have a Few Fed speakers at the helm, with Williams at 14:10, Bowman at 16:00, Waller at 17:40, Evans at 21:5 and Bostic at 21:10. The ECB’s Lagarde also speaks at 18:30.
Up Next (Times in BST)
Related tags:
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.