




FTSE Extends Recovery
Share this:

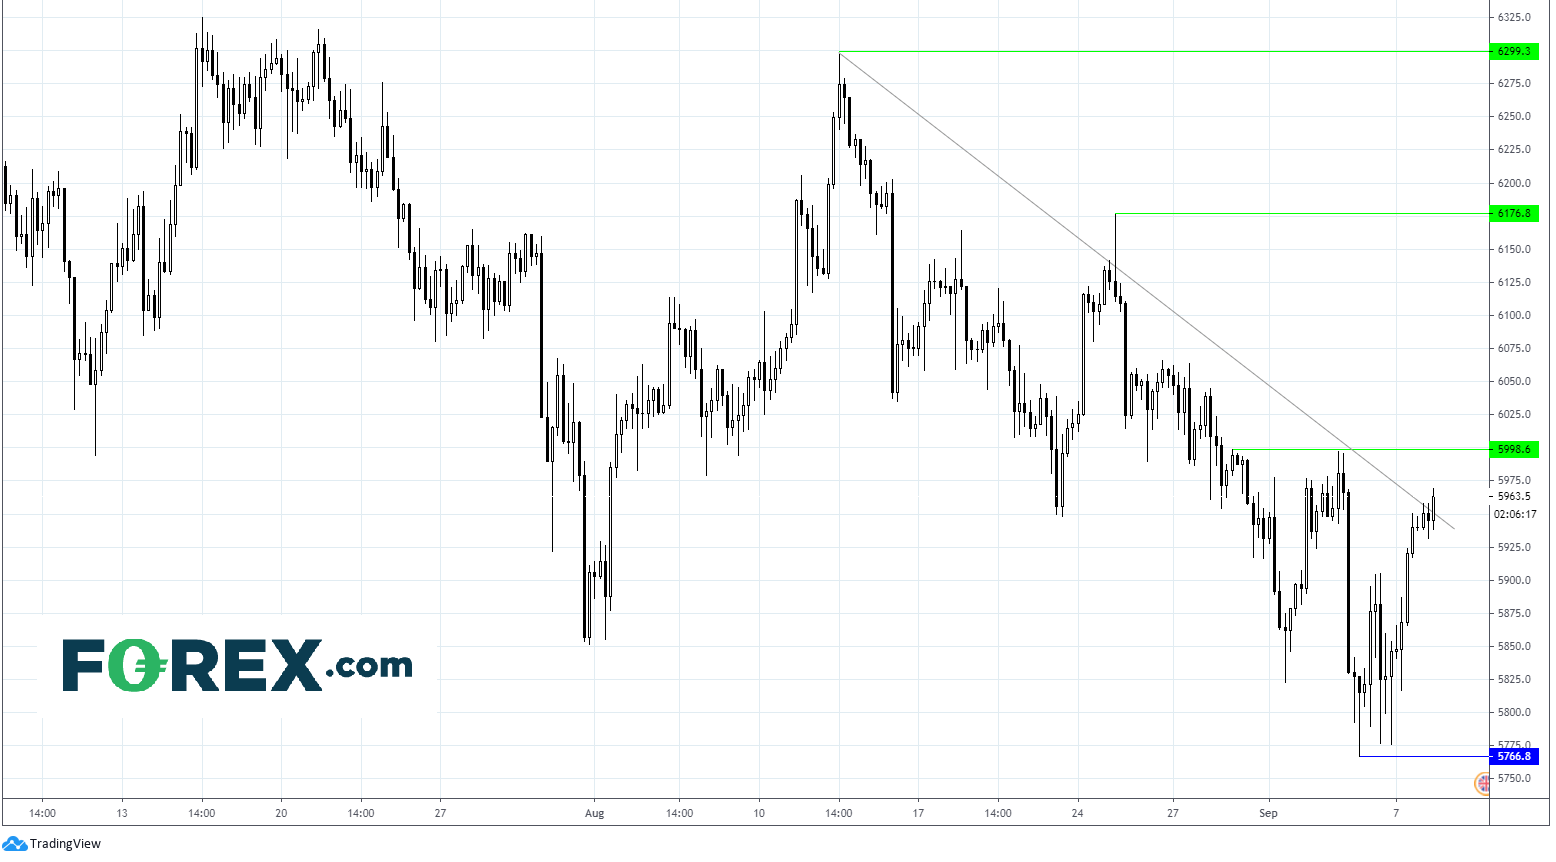
The FTSE is opening on the front foot, adding to yesterday’s impressive gains after upbeat risk sentiment and a sliding Pound helped lift the index 2.3%. Sentiment looks set to remain steady for now, although the real test will be when US cash markets open after the long weekend.
Pound extends Brexit losses
The Pound is adding to yesterday’s Brexit inspired losses as the 8th round of Brexit trade talks are due to kick off in London. Boris Johnson continues to attempt to inject some sort of urgency into the talks which have made little progress in months. The PM’s threat that if no progress is made, no deal preparations will be ramped up, come following yesterday’s new deadline for a deal – 15th October and as the government plans to override parts of the Brexit divorce treaty. Boris appears to be pushing the EU to its limits in last chance saloon. However, given the EU’s warning that the UK mustn’t hamper with the Brexit deal, these talks appear to be unraveling before they have even started.
The Pound is extending losses trading at a two-week low a light economic calendar could keep the bears firmly in control. $1.31 is clearly in target now, whilst unfavourable Brexit headlines across this week could see sterling losses ramp and $1.30 become a very real target. A weaker Pound is beneficial for the multinationals on the FTSE so we could finally see the UK index play catch up with its peers that it has trailed behind since the mid March recovery.
Demand concerns hit oil
Oil can’t shake off demand concerns, particularly as US driving seasons comes to an end It’s refocusing the market on demand expectations, just US covid cases are on the rise again in the US. Data showed that coronavirus cases rose in 22 states over the Labor Day public holiday weekend, cases are also climbing sharply in the UK and in mainland Europe raising fears that oil demand will stay lacklustre for longer. Quite simply people won’t look towards extended travel is coronavirus cases are surging again. WTI fell 1.9% overnight striking and trades at $39.0.
With oil trading lower USD/CAD is a touch softer, although holding above 1.31 as the BoC meeting tomorrow also draws into focus.
Euro lifted by mixed German trade data
Mixed trade data from Germany has been enough to reverse earlier losses in the Euro and push EURUSD back over $1.18. Whilst imports increased an anemic 1.1%, German exports jumped +4.7% mom, after a 14.7% rise in June. Another surge in exports is boosting optimism surrounding a strong GDP rebound. Eurozone GDP will move into focus
FTSE Chart
The FTSE is opening on the front foot, adding to yesterday’s impressive gains after upbeat risk sentiment and a sliding Pound helped lift the index 2.3%. Sentiment looks set to remain steady for now, although the real test will be when US cash markets open after the long weekend.
Pound extends Brexit losses
The Pound is adding to yesterday’s Brexit inspired losses as the 8th round of Brexit trade talks are due to kick off in London. Boris Johnson continues to attempt to inject some sort of urgency into the talks which have made little progress in months. The PM’s threat that if no progress is made, no deal preparations will be ramped up, come following yesterday’s new deadline for a deal – 15th October and as the government plans to override parts of the Brexit divorce treaty. Boris appears to be pushing the EU to its limits in last chance saloon. However, given the EU’s warning that the UK mustn’t hamper with the Brexit deal, these talks appear to be unraveling before they have even started.
The Pound is extending losses trading at a two-week low a light economic calendar could keep the bears firmly in control. $1.31 is clearly in target now, whilst unfavourable Brexit headlines across this week could see sterling losses ramp and $1.30 become a very real target. A weaker Pound is beneficial for the multinationals on the FTSE so we could finally see the UK index play catch up with its peers that it has trailed behind since the mid March recovery.
Demand concerns hit oil
Oil can’t shake off demand concerns, particularly as US driving seasons comes to an end It’s refocusing the market on demand expectations, just US covid cases are on the rise again in the US. Data showed that coronavirus cases rose in 22 states over the Labor Day public holiday weekend, cases are also climbing sharply in the UK and in mainland Europe raising fears that oil demand will stay lacklustre for longer. Quite simply people won’t look towards extended travel is coronavirus cases are surging again. WTI fell 1.9% overnight striking and trades at $39.0.
With oil trading lower USD/CAD is a touch softer, although holding above 1.31 as the BoC meeting tomorrow also draws into focus.
Euro lifted by mixed German trade data
Mixed trade data from Germany has been enough to reverse earlier losses in the Euro and push EURUSD back over $1.18. Whilst imports increased an anaemic 1.1%, German exports jumped +4.7% mom, after a 14.7% rise in June. Another surge in exports is boosting optimism surrounding a strong GDP rebound. Eurozone GDP will move into focus
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.