



Gold risks further setback
The improved risk sentiment that emerged during the session yesterday flowed through into the European and U.S. sessions prompting a strong rally in equities and a round of selling in traditional safe-haven assets including gold.
Share this:

The improved risk sentiment that emerged during the session yesterday flowed through into the European and U.S. sessions prompting a strong rally in equities and a round of selling in traditional safe-haven assets including gold.
Supporting the move, a Reuters report that Chinese authorities were preparing to further prop up the Chinese economy by cutting the loan prime rate (LPR) and banks reserve requirement ratio (RRR) at its next meeting on February 20th. Also aided by comments from the World Health Organisation (WHO) that the virus did not as yet constitute a pandemic.
While there is never a good time to potentially upset the “gold bugs” amongst us, gold appears increasingly vulnerable to a retreat back to the $1520 area, for a mix of the macro and technical reasons outlined below.
From a macro perspective, while physical demand is not a primary driver of the gold price, demand from China accounts for approximately 30% of the world's physical gold jewellery, bar and coins. The uncertainty created by the coronavirus is likely to impact underlying physical demand for gold.
Technically our medium-term target in gold was the $1600 region, a level that was reached one month later.
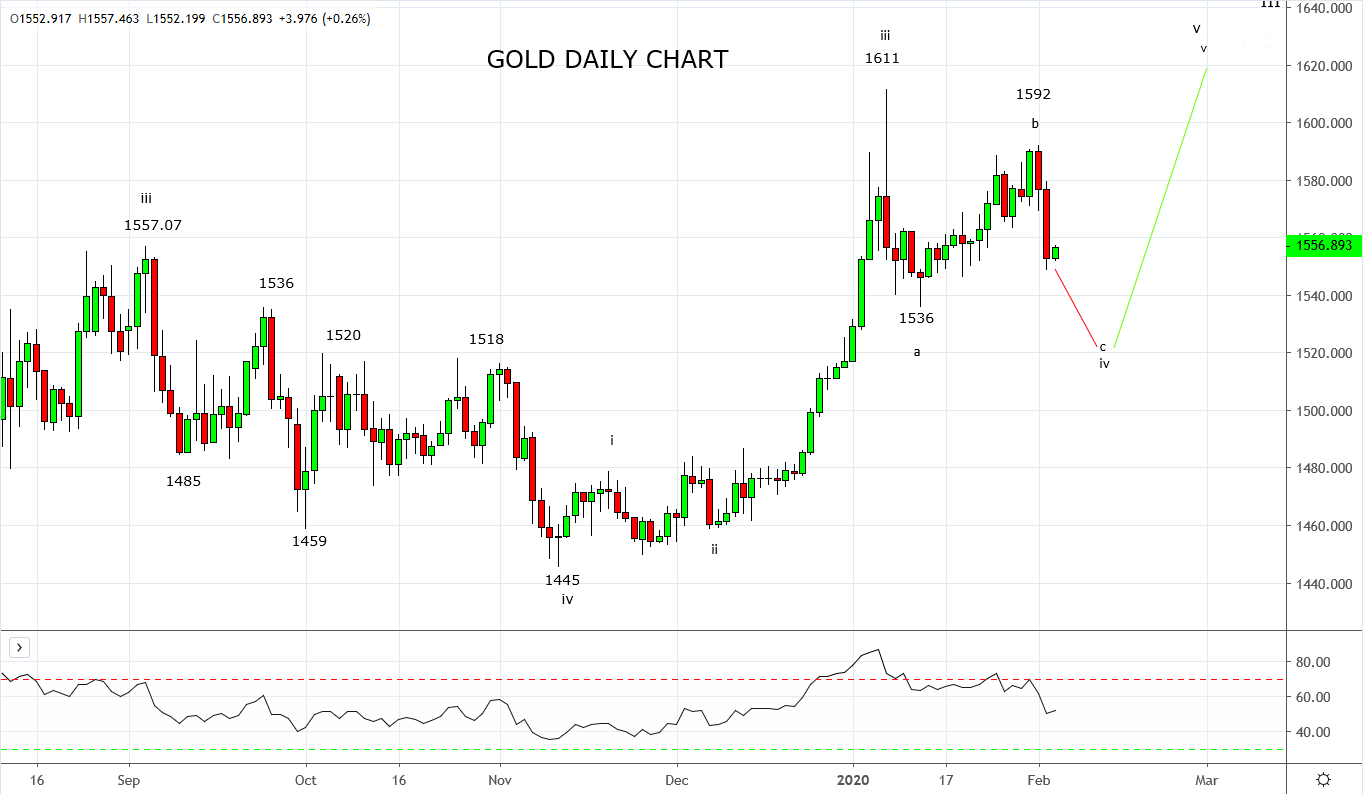
Drilling down, the rally from the $1536 low of January 14 to the $1592 high of this week lacks impulsive characteristics. Instead, it appears to be Wave B or the second leg of a three-wave correction. In this light, we see golds overnight fall as part of Wave C or the third and final leg of the pullback which targets wave equality support $1520/15 area.
Providing gold holds the $1520/15 area and in the process forms a bullish reversal type candle we will look to re-enter longs in anticipation of a retest of the $1611 high. This would complete a five-wave rally on both the short term and long term time frames. Keeping in mind that if gold fails to hold the $1520/15 support region, the risks of a deeper pullback towards $1445 increase significantly.
Source Tradingview. The figures stated areas of the 5th of February 2020. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Price Forecast: XAU/USD Avoids Breakdown as Yields Surged but Can it Continue?
Surging Treasury yields sent a jolt across markets last week but, so far, gold prices have held above the FOMC low. The big question now is whether that can continue and, if not, will bulls show up at $4100 or $4k like they did in June and July?

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.


Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.