



Market Brief Brexit Optimism Boosts GBP US Indices Pull Back
See a summary of the top market themes and trends from today's US trading session!
Share this:

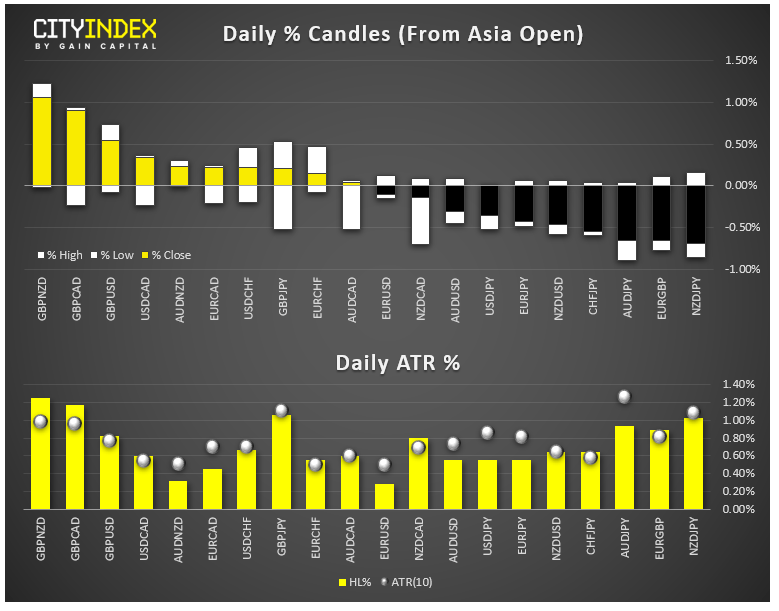
- FX: Potentially positive signs on Brexit made the pound the strongest major currency on day. The kiwi brought up the rear.
- Commodities: Gold edged nearly 1% higher on the day while Oil tacked on 2.5%. See more on the why silver may start to outperform gold.
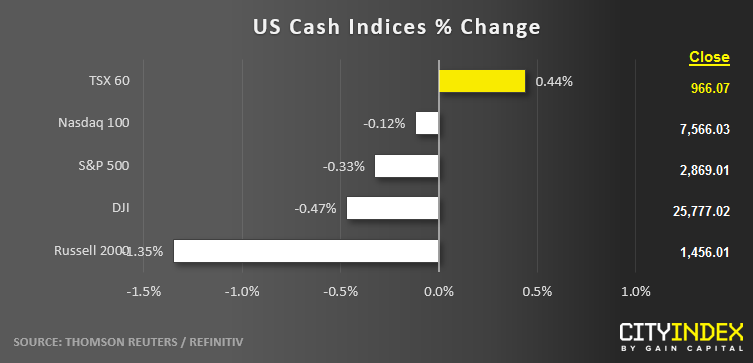
- US indices closed marginally lower in “dog days of Summer” trade (see more on the S&P 500 here). Yield curve inversions were the story of the day, with the 2s10s inverting on a closing basis and the 30-year Treasury yield falling below that of the 3-month tenor for the first time in 12 years.
- Utilities (XLU) were the strongest sector today while Energy stocks (XLE) were the weakest.
- Stocks on the Move:
- Altria (MO, -4%) and Philip Morris International (PM, -7%) are reportedly in talks to merge after separating back in 2008.
- Costco Wholesale (COST) rallied 5% after opening its first store in China. It took some customers up to three hours to park and the store had to close early due to the massive crowds.
- Johnson and Johnson (JNJ) rose 2% on a smaller-than-feared $572M fine for the firm’s role in fueling the opioid epidemic.
- Snapchat (SNAP) dropped 4% on news that rival Instagram was working on a new messaging app called Threads for close friends and family.
*No major macroeconomic data is scheduled for release in the upcoming Asian session.*
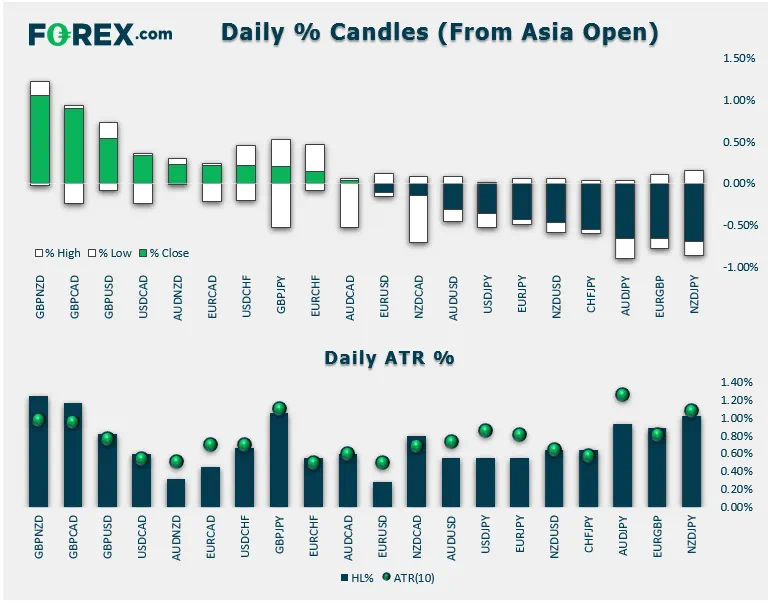
- FX: Potentially positive signs on Brexit made the pound the strongest major currency on day. The kiwi brought up the rear.
- Commodities: Gold edged nearly 1% higher on the day while Oil tacked on 2.5%. See more on the why silver may start to outperform gold.
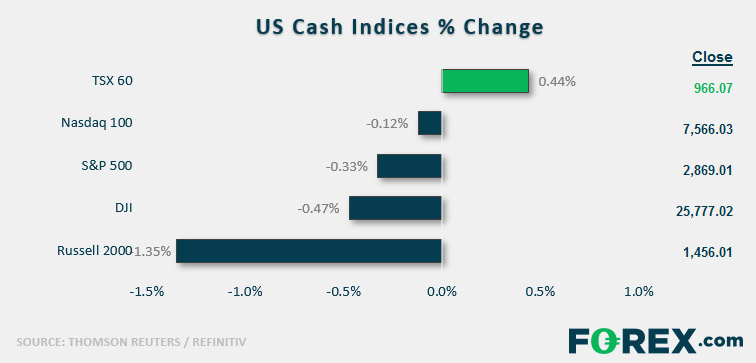
- US indices closed marginally lower in “dog days of Summer.” Yield curve inversions were the story of the day, with the 2s10s inverting on a closing basis and the 30-year Treasury yield falling below that of the 3-month tenor for the first time in 12 years.
- Utilities (XLU) were the strongest sector today while Energy stocks (XLE) were the weakest.
- Stocks on the Move:
- Altria (MO, -4%) and Philip Morris International (PM, -7%) are reportedly in talks to merge after separating back in 2008.
- Costco Wholesale (COST) rallied 5% after opening its first store in China. It took some customers up to three hours to park and the store had to close early due to the massive crowds.
- Johnson and Johnson (JNJ) rose 2% on a smaller-than-feared $572M fine for the firm’s role in fueling the opioid epidemic.
- Snapchat (SNAP) dropped 4% on news that rival Instagram was working on a new messaging app called Threads for close friends and family.
*No major macroeconomic data is scheduled for release in the upcoming Asian session.*

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.