





Market Brief Pound soars and stocks rebound
A summary of news and snapshot of moves ahead of the US session.
Share this:

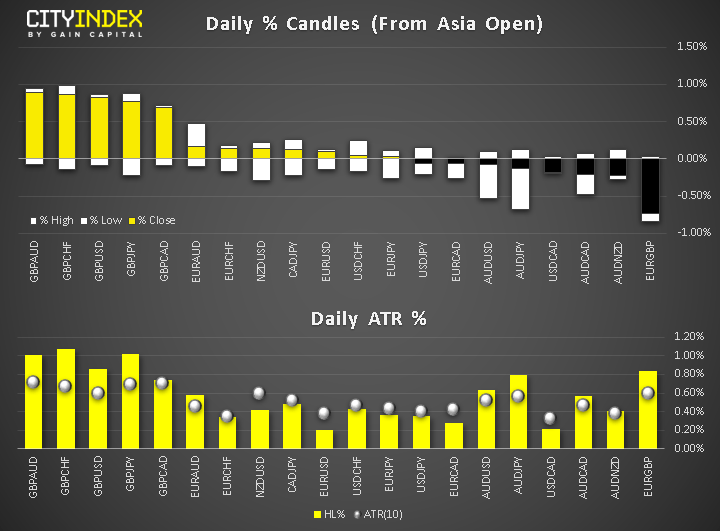
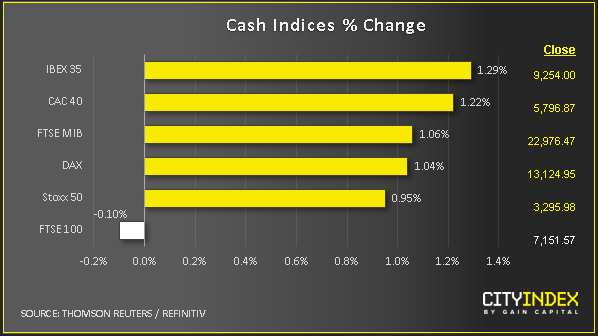
- Market update at 13:20 GMT: the GBP was easily the strongest currency while the AUD and USD brought up the rear. European stocks and US index futures were rebounding sharply, although the FTSE underperformed, hurt once again by a stronger pound. Crude oil was up along with risk assets ahead of oil inventories today and OPEC meeting tomorrow. Gold was supported by a weaker dollar, although the gains were kept in check due in part to rebounding equity prices.
View our guide on how to interpret the FX Dashboard
- GBP as expectations grow that the Tories will win the majority of the votes in the upcoming election. AUD fell after a sharp two-day rally when it was supported by stronger Chinese manufacturing PMI data. It was hit as growth data showed Australia’s GDP missed expectations at 0.4% Q/Q vs. 0.5% expected. USD was hurt by the ADP employment report showing jobs growth was much weaker in November than expected.
- Services PMI recap: Final services PMIs were revised higher for the Eurozone (to 51.9 from 51.5), Germany (to 51.7 from 51.3) and UK (49.3 from 48.6), but lower for France (to 52.2 from 52.9). Separately, flash services PMIs showed Spain beat (at 53.2 vs. 51.9) and Italy disappointed expectations (at 50.4 vs. 51.2 eyed). Overnight, China’s Caixin services PMI topped expectations at 53.5 compared with 51.1 expected and last.
- Stocks: Sentiment towards risk turned positive after a report by Bloomberg suggested that the phase 1 trade deal between the US and China was actually much closer than thought, and that it could be signed by December 15 tariffs deadline. Today’s gains for stocks come after a sharp two-day sell-off, triggered by concerns that a trade deal was not imminent. On Tuesday, it was Donald Trump himself who surprised the markets by saying a trade deal with China could wait until after the 2020 presidential election in November. It remains to be seen whether the gains can be sustained though, given that Bloomberg’s source was “unidentified.” What’s more, the US has imposed fresh tariffs on Argentina and Brazil exports of metals, while Trump has threatened to impose duties on French goods. On top of this, China has warned that the US bill calling for a tougher US response to Beijing's treatment of its Uighur Muslim minority will impact bilateral cooperation. So there are plenty of reasons why trade jitters could escalate.
- Coming up:
Related tags:



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
British Pound Technical Outlook: GBP/USD Rebound Challenges September Downtrend 9 30 2026
Sterling has rallied sharply from key support, with GBP/USD at an inflection point that could determine whether a larger recovery is underway.

EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.


NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.