



Global Markets Mixed as Shutdown Nears End | Tech Concentration & UK Rate Cut Bets in Focus
US markets weakened as tariff concerns resurfaced, with futures pointing lower across all indices. APAC equities traded mixed, while Europe opened in the red after Monday’s brief rebound. The DAX is testing its 200 EMA near 24,100, with short-term bearish momentum but structural uptrend intact. Gold extended its rally beyond $4,150/oz, oil held steady, and the dollar whipsawed amid shifting risk tone. With the US–China tariff deadline looming, sentiment remains cautious.
Share this:

Market & Macro Summary – 12 November 2025
Global Markets Overview
- US: President Trump said tariffs on coffee imports will be lowered, signaling a modest easing of trade restrictions.
- Asia: Chinese President Xi reaffirmed partnership with Spain, stressing trust and deeper cooperation.
- Crypto: Bitcoin traded choppy around USD 103 k amid reduced volatility.
- Australia: RBA Deputy Governor Hauser said policy remains “restrictive” but is under debate; consumption recovery is “gradual,” and no unemployment level is yet satisfactory.
Equities & Sector Themes
Technology Concentration – S&P 500
- Tech dominance deepens: IT now makes up ≈ 36 % of the S&P 500, 23 ppt above Financials, and nearly 50 % if broader tech names are included.
- AI dependence: The index’s performance is increasingly tied to the AI cycle, amplifying potential downside if sentiment fades.
- Earnings power: Tech expected to generate ~25 % of Q3 S&P 500 profits, likely rising further. High self-funding capacity from internal cash flow remains a stabilising factor.
European Energy Stocks
- Up 18 % YTD in EUR (+32 % in USD) despite a 15 % oil price drop — a historical decoupling.
- Analysts see parallels to the early 1990s: efficiency and payout discipline supporting returns amid weak oil prices.
- Caution: 2026 profit forecasts cut ~15 %, valuations stretched; sustained outperformance unlikely if oil oversupply persists.
DAX Technical analysis 4 H
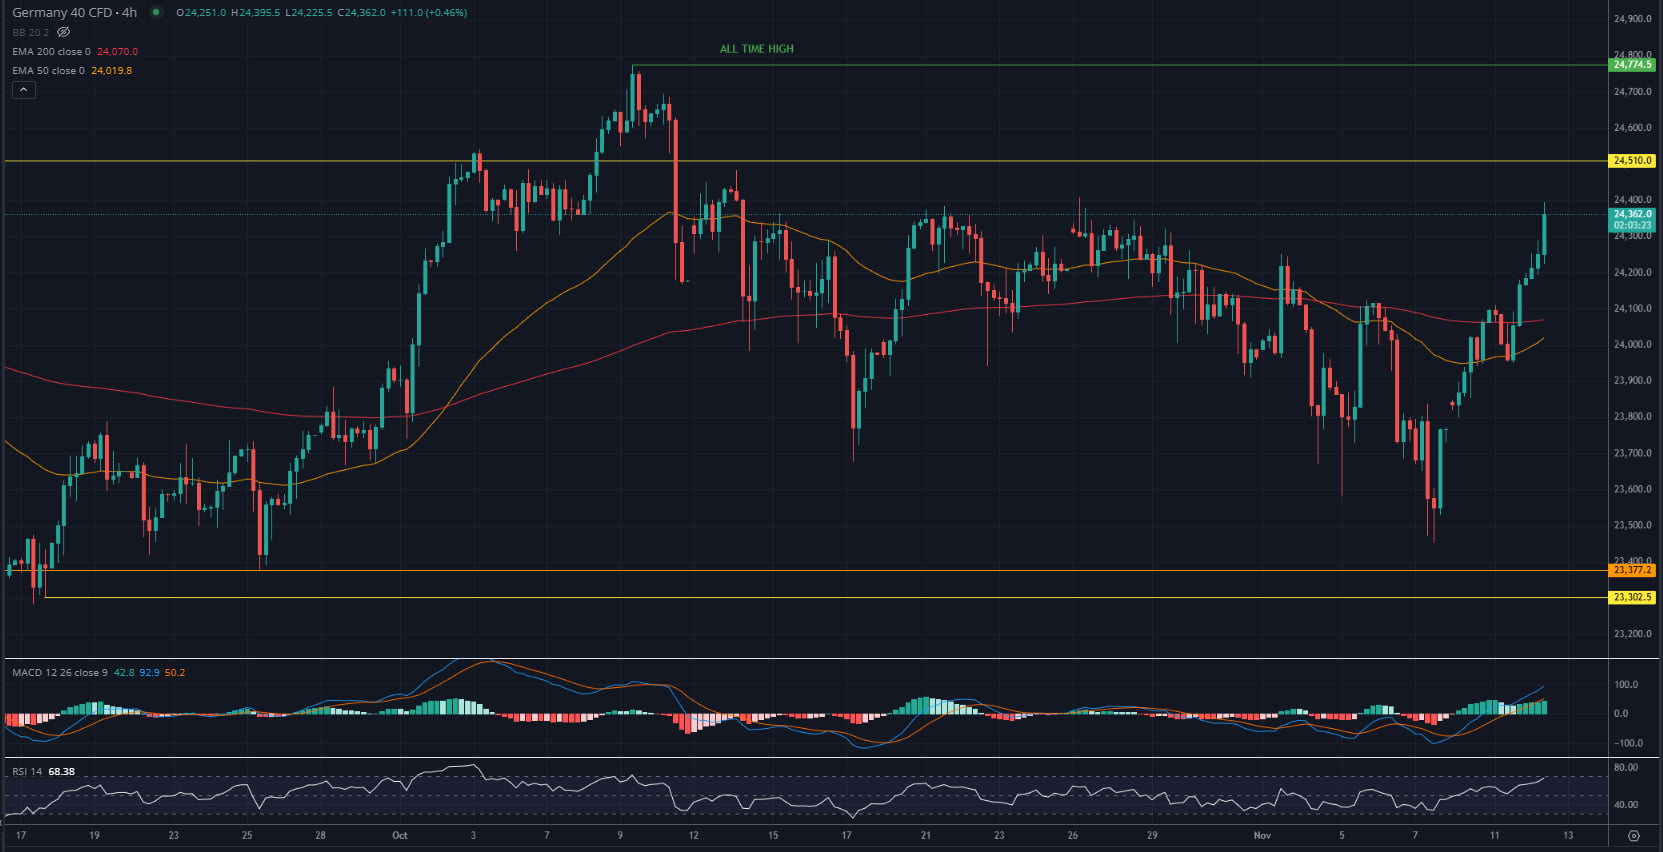
The Germany 40 CFD (4H) has broken higher from its recent consolidation, reclaiming both the 50 EMA (24,020) and 200 EMA (24,070) with strong momentum. The index is now testing the 24,510 resistance area — a key level that has repeatedly capped rallies. The MACD shows a bullish crossover with expanding histogram bars, while the RSI (68) approaches overbought territory, reflecting strong short-term buying pressure.
If price closes above 24,510, a breakout toward the all-time high (24,774) becomes likely. Failure to clear resistance could lead to consolidation back toward 24,200–24,050 support. As long as price holds above 24,000, the bullish structure remains intact. Tone: bullish breakout attempt, with momentum favoring continuation if 24,510 gives way.
France – Corporate Tax Plan
- National Assembly approved measures raising corporate tax for large firms.
- Up to 30 % of CAC 40 could see earnings fall ≥ 5 %; French banks’ profits –3 % expected.
- CAC 40’s valuation premium vs. STOXX 600 at rare extremes (~97th percentile).
- Political risk from higher taxes not yet fully priced.
UK Markets – Rate Expectations & Divergence
- Jobless rate: 5.0 % (Jul–Sep), higher than forecast; employment down –32 k in Oct.
- Wages: +4.2 % YoY (slower than BoE’s projection).
- Market reaction: 10y gilt yields fell, equities rose, GBP weakened across G10.
- Futures imply ~90 % chance of BoE rate cut on 18 Dec.
- FTSE 100 +15 % YTD (in EUR), beating S&P 500 (+6 %). FTSE 250 +2.5 %, near 12-year low vs. FTSE 100.
- Large caps benefit from global exposure and buybacks; mid-caps hurt by UK stagnation and high rates.
Corporate & Technology Developments
|
Company |
Key Update |
Implication |
|
AstraZeneca |
Hit new record high; now UK’s largest listed firm. |
Pharma strength driving FTSE defensives. |
|
Richemont & Swatch |
Gained on prospects of US–Switzerland tariff cut (to 15 % from 39 %). |
Boost for Swiss luxury exports. |
|
SoftBank |
Sold entire Nvidia stake (USD 5.8 bn) to fund AI push; Q2 profit doubled to JPY 2.5 trn (USD 16.6 bn) on OpenAI valuation gains. |
Reinforces Japan’s central role in AI investment. |
|
Nebius Group |
Signed USD 3 bn AI-infrastructure deal with Meta; Q3 revenue up 4×; follows USD 17.4 bn Microsoft contract. |
Underscores demand for high-performance computing capacity. |
|
Meta / Yann LeCun |
Meta’s chief AI scientist to exit and launch startup; firm reorganising AI under Superintelligence Labs led by Alexandr Wang (ex-Scale AI). |
Highlights internal reshuffle and competitive AI talent market. |
Macro & Policy Context
US Shutdown Resolution
- 40-day government shutdown nearing end: Senate approved a compromise funding package.
- Includes back pay for federal staff and military; pending House vote.
- Positive equity response: S&P 500 +, NASDAQ +, reflecting relief over data resumption and fiscal clarity.
Inequality & Consumption Trends
- Economists describe a “K-shaped” economy: high-income groups benefit from asset inflation and wage gains; lower-income households face weak real wages and job losses.
- Corporate earnings skewed toward premium and tech sectors, while mass-market firms face pressure.
- AI advances further widen corporate and labour-market dispersion.
Regards,
Philip Janni Papageorgiou - @PhilipForexCom


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

Australian Dollar Forecast: AUD/USD Four-Week Slide Nears Critical Uptrend Support 9 29 2026
Aussie momentum has deteriorated sharply into quarter-end, with inflation, Core PCE and NFP on tap as AUD/USD closes in on a pivotal technical threshold.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.