




OIL MARKET WEEK AHEAD PreOPEC Whispers Intensify
Behind-the-scenes discussions on the next production level decision are intensifying...
Share this:

As the OPEC’s December meeting in Vienna draws closer, the behind-the-scenes discussions on the next production level decision are intensifying as is the flow of sideways comments from the cartel’s oil ministers. In the past week, Saudi Arabia, which has ended up with lower output levels not only because of planned cuts but also because of the attack on the Abqaiq refinery, hinted that it is keen to see other members stick to their output quotas, wagging an accusatory finger at Iran and Nigeria.
During the week ahead, look out for a response from Russia which is less than keen to rein in its output. The CEO of Russia’s Rosneft, Igor Sechin, made it openly clear that he is opposed to cutting production and recently indicated that Saudi Arabia should mind its own business rather than put pressure on Russia to reduce output.
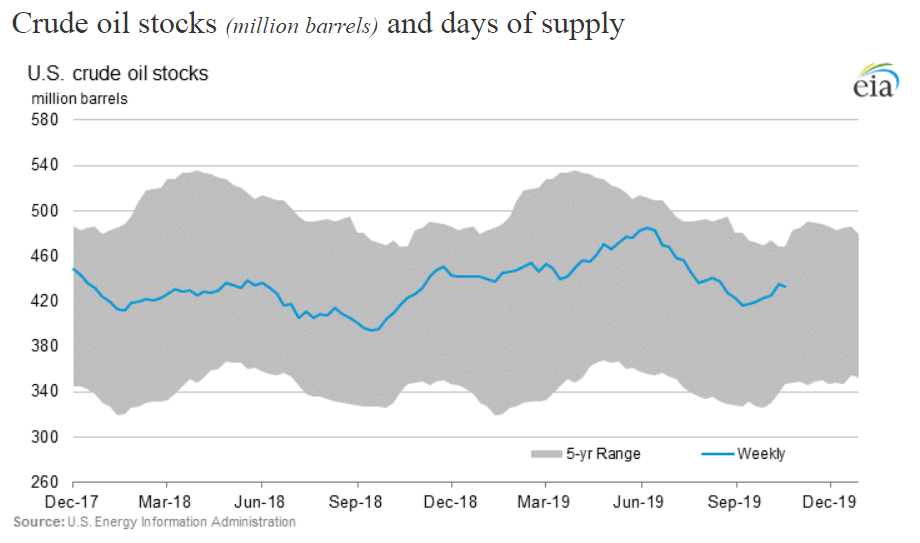
Irrespective of the less-than-amicable comments, oil producers are facing stagnating demand and a build-up of reserves which may force OPEC into not only extending existing output restrictions but also adding new ones to meet slowing demand.
API WEEKLY CRUDE STOCKS
US crude oil production is now running at an all-time high of 12.4M b/d, which is partially catering to slightly higher domestic demand but is also being increasingly exported abroad. According to the EIA the gradual increase in US exports will mean that the US will become a net exporter of petroleum in the last quarter of this year.
The API stocks on Tuesday and EIA weekly petroleum reserves on Wednesday will show if the domestic US stock levels are continuing to build as they did in September and October or if increased exports and domestic demand are managing to balance out the US oil market.
Expectations for US GDP data on Wednesday are for a slight slowdown from the 2% growth in the second quarter, which tallies with other economic indicators over the last few months. A slowdown in domestic growth will not be supportive of the oil market and may require a re-think on domestic production levels.
| When? | What? | Why is it important? |
| Sunday 27 Oct | China Sept industrial profit | Indicator of Chinese industrial growth |
| Tuesday 29 Oct | BP Q3 results | How lower prices affected quarterly earnings |
| Tuesday 29 Oct | Conoco Phillips Q3 earnings | How lower prices affected quarterly earnings |
| Tuesday 29 Oct 15.00 | US pending home sales | Indicator of demand from the construction industry |
| Tuesday 29 Oct 20.30 | API US weekly crude oil stocks | Previously increase of 4.45m bbl |
| Wednesday 30 Oct 13.30 | US GDP | Previously at 2% |
| Wednesday 30 Oct 16.30 | EIA crude oil inventories | Previously down 1.699m |
| Thursday 31 Oct 02.00 | Chinese Manufacturing PMI | Indicator of Chinese manufacturing growth, previously at 49.8 |
| Friday 1 Nov 02.45 | China Caixin Manufacturing PMI | Similar to the previous indicator but focused on smaller and medium-sized enterprises |
| Friday 1 Nov 14.45 | US Manufacturing PMI | Indicator of the state of US manufacturing. Previously at 51.5 |
| Friday 1 Nov 20.30 | CFTC Oil Net Positions |
BP Earnings Results on Tap
BP’s results on Tuesday will provide more information on how badly the oil’s dips below $60 in the last quarter affected the company’s upstream operations. Hurricane Barry slowed down production in the Gulf of Mexico during Q3 as did maintenance activities and seasonal turnaround. Lower prices would have worked in favour of BP’s downstream business. But weaker demand for petroleum products caused by an overall weakening of the global economy is also likely to have affected BP’s refining operations.




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Wall Street Forecast: DJIA rises on hawkish Fed expectations & rising yields
U.S. stocks are opening lower on Wednesday, pressured by higher crude oil prices and rising government bond yields, as investors await further developments from negotiations in the Middle East and ahead of a key U.S.-China summit.


Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.

Crude and dollar rebound as Trump says deal possible after the election
Donald Trump’s speech at the UN seems to have poured cold waters on any hopes of a deal. Crude oil, the US dollar and bond yields all bounced back from their lows, causing fresh pressure on foreign currencies, European indices and to a lesser degree precious metals.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.