



Q4 2021 US Reporting Season Preview
Q4 reporting season picks up speed this evening with reports from financial heavyweights JP Morgan, Wells Fargo, Citigroup, and Blackrock, before 114 companies report next week. See below the key themes and trends we'll be monitoring.
Share this:
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
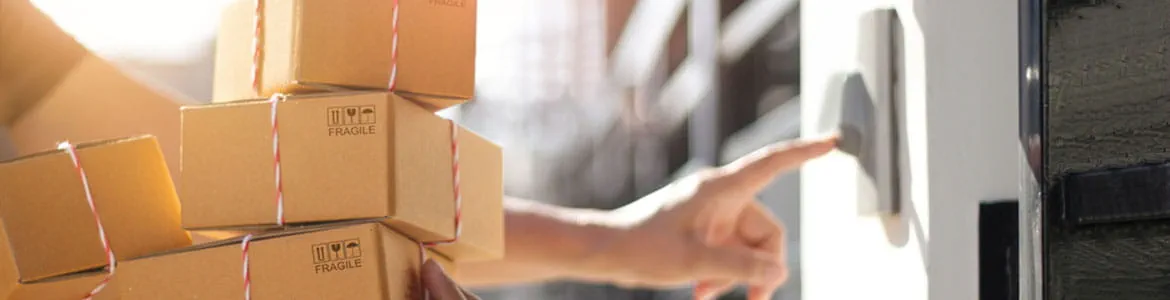
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Macro Overview
2021 saw the S&P500 hit fresh record highs on an astonishing 70 separate days. It is noticeable that the first two weeks of 2022 have seen a continuation of the volatility that marked the final months of 2021.
US inflation recently reached an almost 40 year high, hitting an annualised 7% in December. To counter this, the Federal Reserve has become increasingly hawkish.
In response, market expectations have shifted towards faster balance sheet normalization, with "quantitative tightening" to begin in September after Fed lift-off in June or possibly as early as March. A prospect that has rattled tech stocks.
Meanwhile, surging Omicron cases have left hospitals straining under the weight of numbers, disrupting global supply chains and grocery shelves empty. A development that will weigh on Q1 growth, likely to be reflected in some company's forward guidance.
Earnings
Despite the headwinds outlined above, S&P500 companies are expected to deliver strong earnings growth again. According to Factset, "For Q4 2021, the estimated earnings growth rate for the S&P 500 is 21.7%."
Presuming this is the confirmed growth rate for the quarter, it will mark the fourth straight quarter of earnings growth above 20% and lift full years earning growth to more than 40% for the full year.
Guidance
As noted by FactSet in the first week of January, "93 S&P 500 companies have issued EPS guidance for the fourth quarter. This number is slightly below the 5-year average of 100. Of these 93 companies, 56 have issued negative EPS guidance, and 37 have issued positive EPS guidance."
This marks the first time since Q2 2020 that S&P500 companies have issued more negative EPS guidance than positive guidance. Despite this, the estimated (year over year) earnings growth for Q4 2021 is above the expectations from the start of Q4.
Sector Performance
As noted by Factset, the Energy sector led by companies such as Exxon Mobil and Chevron have recorded the largest percentage increase in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at 40.8% (to $28.1 billion from $20.0 billion).
The Consumer Discretionary sector led by Amazon.com has recorded the largest percentage decrease in estimated (dollar-level) earnings of all eleven sectors since the start of the quarter at -15.1% (to $27.1 billion from $32.0 billion).
S&P500 Technical Outlook
The overnight decline has the S&P500 eyeing important trendline support at 4620/00ish from the March 2020, 2174 low.
Providing the S&P500 remains above 4620/00 (closing basis), look for a push towards 5000 during the first quarter of 2022.
However, should a sustained break below 4620/00ish occur, the risks are for a deeper pullback towards 4400.
Source Tradingview. The figures stated areas of January 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.