



S&P 500 Forecast: SPX muted as tech worries persist
US futures are pointing to a quiet open after heightened volatility last week, during which tech stocks came under pressure as the Dow Jones rose above 50,000. US NFP and CPI data are due later in the week.
Share this:
US futures
Dow futures 0.01%, S&P futures 0.03% & Nasdaq futures 0.01%
In Europe
FTSE -0.18 & DAX 0.47%
- Stocks stall after Friday’s recovery.
- Tech stocks fell last week while the Dow rose to 50k
- Yen rises after Takaichi wins the election
- Oil steadies on the prospect of further US-Iran talks


Tech stocks fail to extend Friday’s rally
US futures are pointing to a quiet open after heightened volatility last week, during which tech stocks came under pressure as the Dow Jones rose above 50,000.
The S&P 500 and the NASDAQ rebounded on Friday after three consecutive days of losses, as the AI trade came under renewed scrutiny amid concerns about heavy capital-expenditure forecasts. Several big tech results have revived investor concerns about huge spending, with Amazon, Google, Meta, and Microsoft collectively expected to spend around $650 billion in the race to win AI dominance.
Still, Friday's rebound in tech hasn't held up, and futures are pointing to a lower start today. Meanwhile, the Dow Jones holds above 50,000, boosted by rotation into value.
The next big test for AI shares will be Nvidia's earnings later this month. NVIDIA trades 1% lower premarket; other chip stocks such as Micron Technology and Broadcom are also trading over 1% lower.
Attention also turns to economic data, with Wednesday's January nonfarm payrolls report and Friday's CPI report, both of which can provide essential clues about the timing of the Fed’s next move. Weak jobs figures last week raised concerns over the health of the labour market.
Corporate news
Novo Nordisk is rising 5% after Him & Hers pulled its copycat weight loss pill off the market after Novo threatened legal action against the telehealth firm. His & Hers has sunk 18%
Micron Technologies is falling after a report indicated that Samsung Electronics would begin mass production of next-generation high-bandwidth memory chips this month, intensifying competition within the sector.
S&P500 forecast – technical analysis.
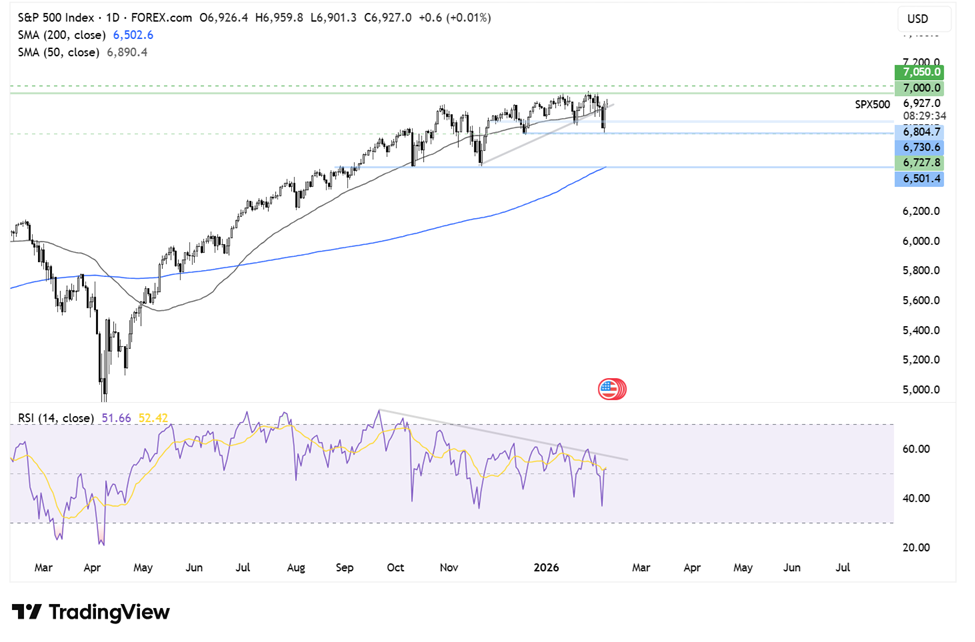
The S&P 500 broke below the 50 SMA and the rising trendline on Thursday to a low of 6730, before rebounding to test the 50 SMA and rising trendline resistance around 6900. Momentum is fading. Should buyers hold above this resistance, attention turns to 7000. A break below 6900 opens the door to 6800 and 6735. A break below here creates a lower low and exposes the 200 SMA at 6500.
FX markets – USD falls, USD/JPY falls
The USD is falling after last week's employment figures were weaker than expected, boosting expectations that the Federal Reserve will need to do more to support the labour market. This week's economic releases, including the nonfarm payrolls report and the CPI, could tip the scales.
USD/JPY is falling amid a stronger yen following Prime Minister Takaichi’s landslide victory in Sunday's election. The prospect of a stable government, coupled with serious warnings from the Japanese finance minister and top currency diplomat, deterred investors from reviving the sell Takaichi trade, leading to significant yen appreciation. The results do, however, hand Takeichi a stronger mandate for her fiscal expansive policies, which come at a time when Japanese public finances are under strain.
GBP/USD is rising amid a weaker U.S. dollar and despite rising political uncertainty. The Prime Minister, Kier Starmer, appears to be on increasingly shaky ground following the resignation of a close ally and amid scrutiny of a key diplomatic appointment. This situation, combined with the dovish Bank of England meeting, could limit sterling's upside.
Oil steadies on the prospect of further US-Iran talks
Oil prices are holding steady on Monday after the US and Iran pledged to continue indirect talks, easing concerns about supply; however, India's decision to step away from Russian oil purchases is providing a floor for prices.
Following Friday's peace talks, Iran and the US have pledged to continue negotiations, which both sides described as positive. The talks come as the US has built a military presence in the region; however, optimism about the outlook is keeping the oil risk premium steady.
Separately, India, once one of the largest buyers of Russian seaborne crude, is avoiding purchases for April delivery after agreeing a trade deal with the US that includes a halt to Russian oil purchases.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.