



S&P 500 Forecast: SPX pulls back on Fed independence worries
US stocks are set to open lower on Monday, pulling back from record highs this last week as President Trump escalated his attack on Federal Reserve Chair Jerome Powell.
Share this:
US futures
Dow futures -0.63%, S&P futures -0.50% & Nasdaq futures -0.73%
In Europe
FTSE 0.02% & DAX 0.44%
- Stocks fall from record highs, Gold hits a record high
- US prosecutors start a criminal investigation into Fed Chair Powell
- Geopolitical tensions – Iran, Venezuela, Greenland & Cuba
- Oil steadies after last week’s gains


Stocks slip on Trump – Powell spat
US stocks are set to open lower on Monday, pulling back from record highs this last week as President Trump escalated his attack on the Federal Reserve.
Department of Justice subpoenaed Fed Chairman Powell on criminal charges over the $2.5 billion Fed building restoration. Powell noted that the charges were an effort to oust him over the FOMC's monetary policy decisions.
Trump has been vocal in his criticism of Fed Chair Powell in recent months, insisting the Fed should cut rates more aggressively. Fed Chair Powell’s term finishes in May.
Initial market reaction has been relatively muted, with the biggest moves in the US dollar and precious metals, with gold and silver rising to record highs amid concerns about Fed independence.
Geopolitical tensions also remain on the radar with U.S. President Trump saying the US could meet Iranian officials, after a violent crackdown on protests in Iran. Trump has threatened intervention, although Iran says the situation is now under control.
These latest developments come after the US captured Venezuelan President Maduro earlier in the month, and as the US plans to take Greenland. Trump is also turning his attention to Cuba to make a deal as the flow of Venezuelan oil and money would now stop.
There is heightened geopolitical tension, which could keep the mood cautious.
The US economic calendar is quiet today. Attention will turn to US CPI data tomorrow, which could provide further clues about the Fed’s rate path.
Corporate news
Lululemon is rising 0.4% after saying it expects Q4 revenue and profit to be at the higher end of its previous forecast range amid strong holiday-season demand.
Citigroup is falling 4%, JP Morgan 3%, Bank of America is down 2.5%, and American Express is down 4.8% after President Trump called for a one-year cap on credit card interest rates at 10% starting on January 20.
Exxon Mobil is falling almost 1% after Trump said he could sideline the oil major from Venezuela's energy sector as he criticises the company's response to his push for U.S. oil producers to move quickly into the country.
Walmart is up 3% after shifting its listing to the Nasdaq from the New York Stock Exchange last month, and will join the Nasdaq 100 index on January 20.
S&P 500 forecast – technical analysis.
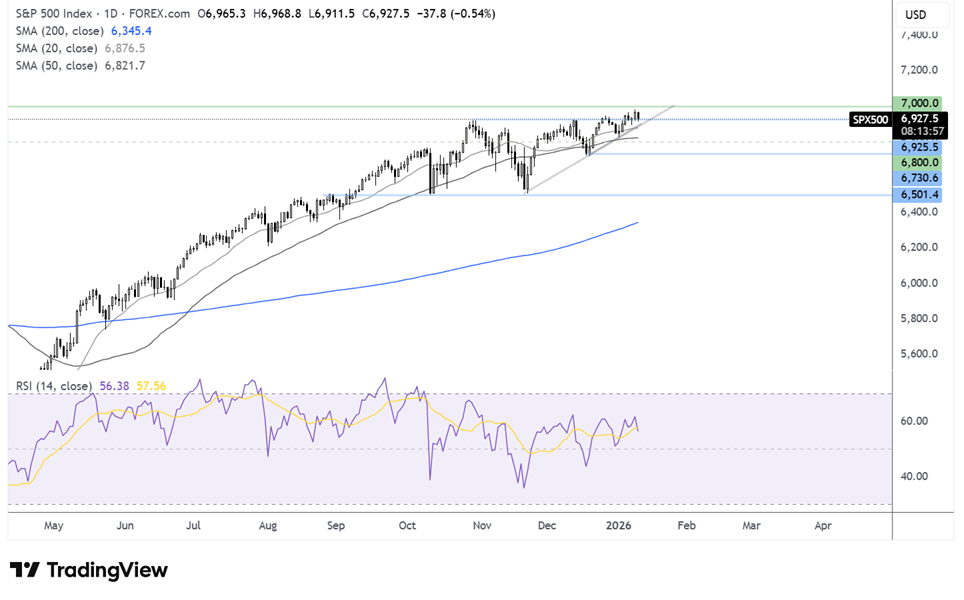
The S&P 500 is extending its recovery from the 6500 November low, pushing to a fresh record high of 6975 on Friday—the price trades above its rising trendline, 20 and 50 SMA. Buyers will look to extend gains towards 7000 as the next logical level. Immediate support is at 6920, the October high, and 6875, the trendline and 20 SMA. Below here, sellers could test 6820, the January low, ahead of 6715, the December low.
FX markets – USD falls, EUR/USD rises
The U.S. dollar is falling sharply after last week's gains and as U.S. prosecutors target Fed Chair Powell, raising concerns about the Fed's independence. Powell slammed the move as part of Trump’s push for greater control over the central bank.
EUR/USD is rising on USD weakness, and after Sentix investor confidence improved in January, rising to -1.8 from -6.2. This is the strongest level in 6 months, and well above the -5.1 forecast.
GBP/USD is rising amid a weaker USD. However, UK unemployment data tomorrow could limit the upside in cable. UK unemployment rose to 5.1%, the highest level since Covid. A further rise in the unemployment rate could raise concerns about the health of the labour market and fuel expectations of BoE rate cuts.
Oil steadies after last week’s gains
Oil prices are unchanged at the start of the week after rallying 3% last week amid ongoing geopolitical tensions.
Iran said that it has this situation completely under control following the anti-government demonstrations at the end of last week and across the weekend. These comments have helped to ease concerns about supply from the OPEC producer.
Trump had threatened intervention in Iran as the protests gathered momentum over the weekend.
Meanwhile, Venezuela remains on traders' radar after Trump announced that the government in Caracas is set to turn over 50 million barrels of sanctioned oil to the US. Any increase in supply would come at a time when the market is already concerned about oversupply in 2026.
Latest market news



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.

S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.