



S&P 500 Forecast: SPX rises cautiously after tech selloff
U.S. stocks are set to open modestly higher on Friday following a sharp tech-led sell-off in the previous session. Investors continue to weigh up corporate earnings, escalating tensions in the Middle East and the latest tariff announcements from the Trump administration.
Share this:


S&P 500 Forecast: SPX rises cautiously after tech selloff
US futures
Dow futures 0.36%, S&P futures 0.19% & Nasdaq futures 0.04%
European futures
FTSE 0.31%, DAX 0.92%
- US stocks rise after yesterday’s tech-led selloff
- US -Iran conflict deepens, oil jumps 40% this month, lifting inflationary pressures
- Intel rises after strongest revenue growth in 15 years
- Oil rises eases from $100 but rises 10% this week
U.S. Stocks rise after tech selloff, Middle East & tariffs in focus
U.S. stocks are set to open modestly higher on Friday following a sharp tech-led sell-off in the previous session. Investors continue to weigh up corporate earnings, escalating tensions in the Middle East and the latest tariff announcements from the Trump administration.
The S&P 500 and Nasdaq posted their steepest one-day declines in a month on Thursday as concerns surrounding the AI trade intensified. Results from Alphabet and Tesla heightened investor worries that capital spending and cash burn among the hyperscalers are rising faster than returns, fuelling caution ahead of next week's earnings from Microsoft, Amazon and Meta.
If you thought tariffs were a thing of the past think again! The Trump administration imposed tariffs of 10% and 12.5% on goods from 60 trading partners after the temporary 10% global tariff expired. However, the move had been widely anticipated and has generated little reaction across financial markets.
Geopolitical risks also remain in focus after President Trump threatened large-scale military action against Iran and its Houthi allies following attacks on two Saudi oil tankers in the Red Sea.
Brent crude has surged around 40% this month. Although prices are easing modestly today, the rally has revived inflation concerns ahead of next week's Federal Reserve meeting.
Markets are now pricing in around a 35% probability of a 25-basis-point Fed rate hike next week, up from roughly 12% a week ago.
Corporate movers
Intel is rising around 4% after reporting its fastest quarterly revenue growth in 15 years. Revenue increased 25% year-on-year to $16.1 billion, while adjusted EPS of $0.42 comfortably beat expectations.
Oracle is gaining 3% after signing a 10-year software agreement with the Pentagon worth almost $7 billion. The contract covers the use of Oracle software and cloud services across several branches of the U.S. military.
American Express is down 3% after reporting a slight revenue miss. Revenue came in at $19.64 billion versus expectations of $19.71 billion, although earnings per share exceeded forecasts.
S&P 500 Forecast – Technical Analysis
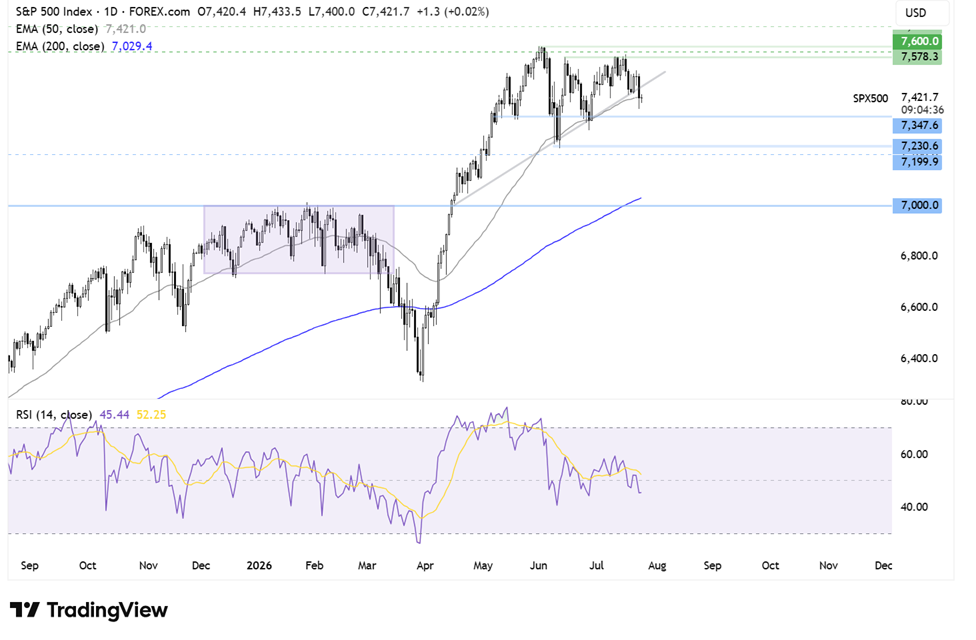
The S&P 500 ran into resistance at 7,575 before pulling back.
The index is now breaking below its rising trend line and testing support around the 50-day EMA at 7,420.
With the RSI slipping below 50, sellers will look for a break beneath the 50-day EMA, opening the door towards 7,350, the next area of horizontal support. A break below there exposes 7,225, the June low.
Should the 50-day EMA hold, buyers will look to reclaim 7,575, creating a higher high and bringing 7,620 and fresh record highs into focus.
FX Markets – Dollar firms, EUR/USD falls
The U.S. dollar is easing slightly on Friday but remains close to a three-week high and is still on track for a weekly gain of around 0.5%.
The greenback has been supported by the sharp rise in oil prices, which has fuelled inflation concerns and boosted expectations of a more hawkish Federal Reserve. Markets are pricing around a 33% probability of a rate hike next week and are fully pricing in a move by September.
EUR/USD is edging higher as the dollar softens slightly and after stronger-than-expected Eurozone PMI data. The composite PMI, a key gauge of business activity, rose to 51.9 from 50.0. However, escalating tensions in the Middle East could limit any meaningful improvement in the region's growth outlook.
GBP/USD is trading lower despite stronger UK PMI data. UK businesses reported their first expansion in three months after activity recovered in July, helped by a temporary easing in Middle East tensions earlier in the month.
The S&P Global Composite PMI rose to 52.1 from 49.3, the strongest reading since February and well above forecasts of 49.7. The Services PMI increased to 51.8 from 48.8, its strongest reading since April, as hospitality businesses benefited from warmer weather and increased demand linked to the Women's World Cup.
Oil rises for a fifth straight week
Oil prices are down around 3% on Friday after briefly topping $100 per barrel. However, Brent remains on track to gain around 10% this week as escalating U.S.-Iran tensions continue to fuel concerns over global supply.
Oil has rallied roughly 25% over the past two weeks after President Trump threatened major military action against Iran and its Houthi allies following attacks in the Red Sea.
The Bab el-Mandeb Strait remains a key chokepoint, while shipping through the Strait of Hormuz has slowed sharply, with vessel transits falling to just three per day over the past three days.
Although this does not amount to a full blockade, the disruption has been sufficient to heighten concerns over global oil supplies and maintain a sizeable geopolitical risk premium in crude prices.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Wall Street Split Widens Into Month-End 9 26 2026
Nasdaq strength contrasts with mounting Dow pressure as rising Treasury yields raise the stakes for stocks heading into the monthly close.


Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.