



Stocks Lower Ahead of Chancellors Summer Statement
The mood in the market remains depressed on Wednesday as coronavirus concerns coupled with geopolitical tensions drag on risk sentiment. Will Rishi Sunak be able to turn risk sentiment around?
Share this:

The mood in the market remains depressed on Wednesday as coronavirus concerns coupled with geopolitical tensions drag on risk sentiment. Equities across the board are out of favour whilst safe haven gold is consolidating just shy of $1800 after jumping 1% so far this week and hitting $1797, its highest level since 2012.
New daily US coronavirus cases dipped slightly at the start of the week. However, Tuesday’s figures have shown its premature to say that numbers are falling. COVID-19 concerns were further fueled by warnings from several Federal Reserve officials that rising coronavirus numbers in the US could jeopardize the economic recovery. The timing here of the rising numbers in the sunbelt is extremely important given that some stimulus programmes are due to expire soon.
US considers sanctions on Hong Kong & HSBC
Geopolitical tensions are also back in focus amid reports that the White House is toying with the idea of striking against the Hong Kong Dollar peg in retaliation for China’s national security law. Whilst the Hong Kong Dollar has shrugged off the reports, HSBC is under pressure as the Trump administration also considers sanctions against banks in the city.
Geopolitical tensions are also back in focus amid reports that the White House is toying with the idea of striking against the Hong Kong Dollar peg in retaliation for China’s national security law. Whilst the Hong Kong Dollar has shrugged off the reports, HSBC is under pressure as the Trump administration also considers sanctions against banks in the city.
HSBC is caught in a political tug of war between the US and China. Asia is the biggest regional contributor to HSBC income highlighting the importance of the region to the business. However, sanctions from the US would be extremely damaging. The share price in London is still down 40% year to date, reflecting the troubles at the bank, compared to Barclays, for example which trades -26% lower year to date.
Rishi Sunak’s Summer Statement in focus
The Chancellor Rishi Sunak is set to take centre stage as he delivers his Summer statement, outlining the economic stimulus package which he will implement to steer the UK economy through the coronavirus crisis. The focus is set to be on jobs, both the protection and creation of jobs as he attempts to pull the UK economy out of the deepest economic downturn in 300 years.
In addition to jobs focus on business costs would be beneficial with immediate effect. More business rate relief, the pre-announced stamp duty holiday and targeted VAT cuts, particularly for the leisure and hospitality sectors would be well received. These measures could see house builders and leisure and hospitality stocks rally, whilst business rate cuts could see battered retail sector rise.
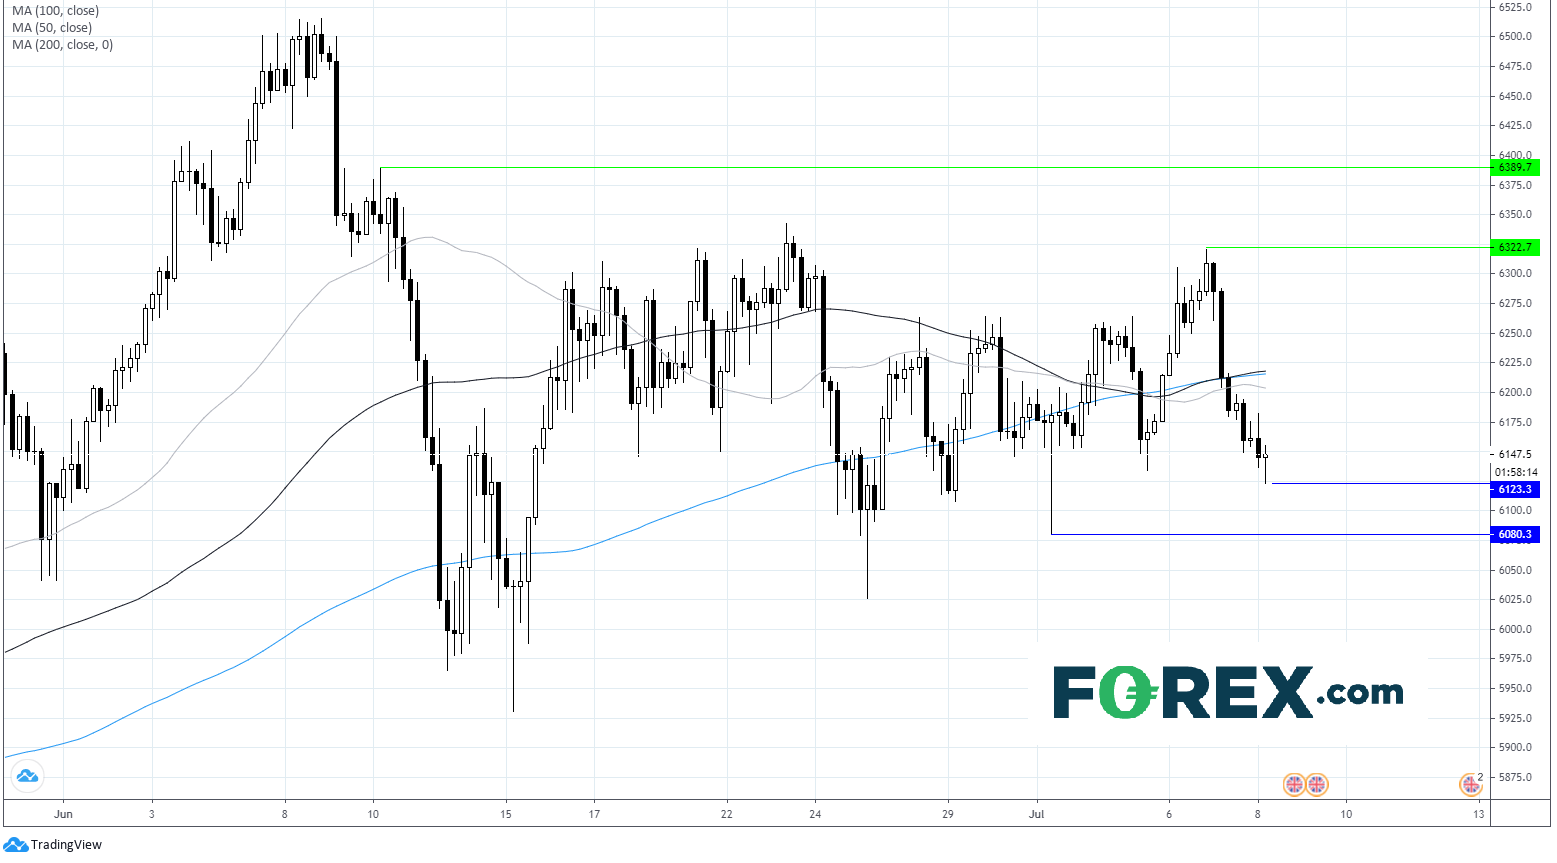
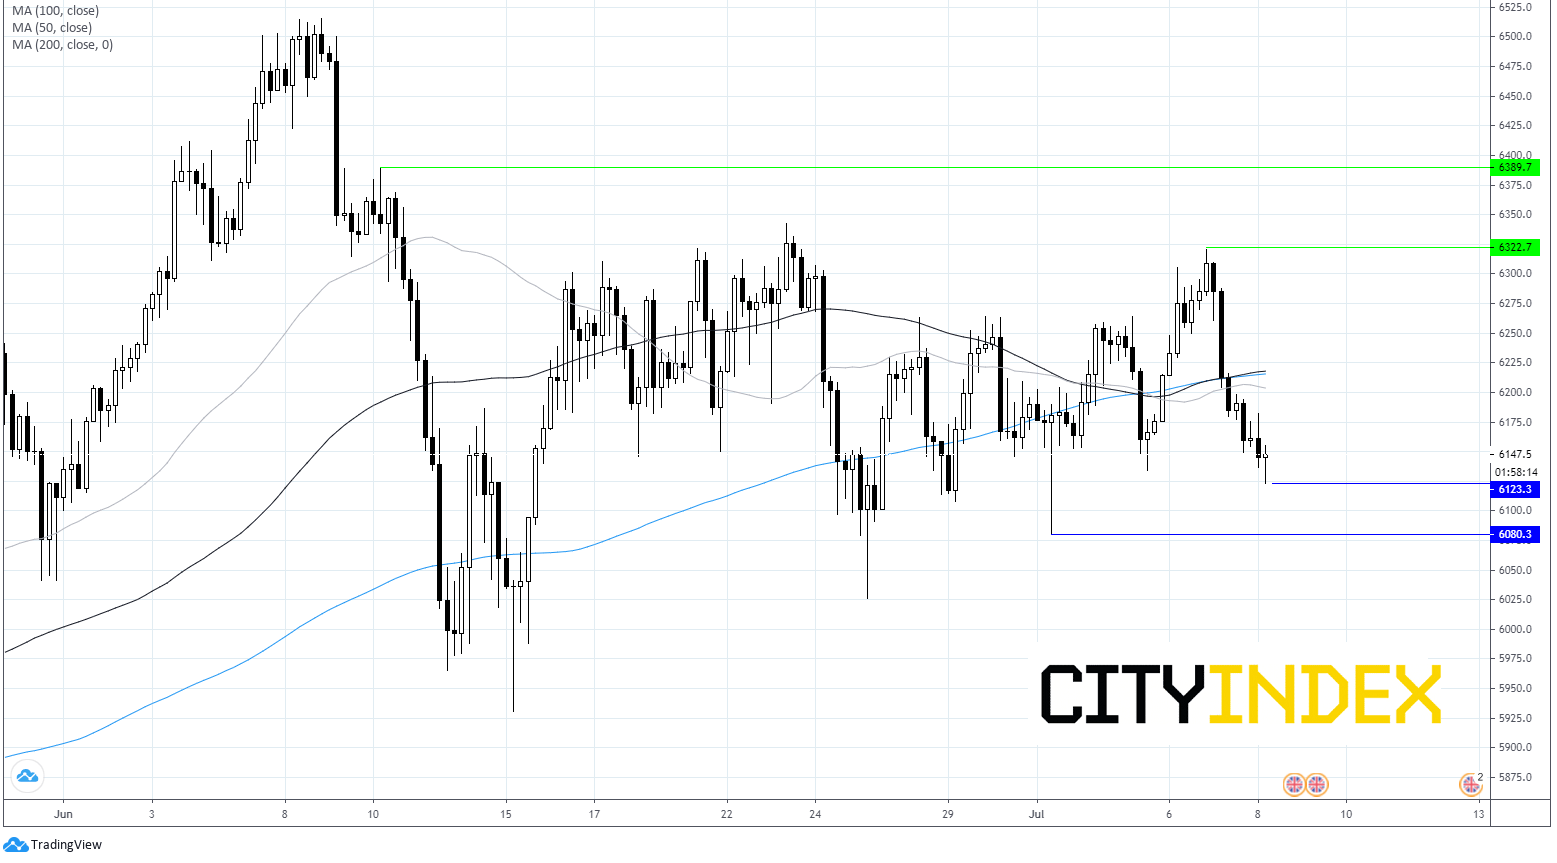
Should Rishi Sunak underwhelm, stocks, particularly on the FTSE250 could come under pressure among with the Pound.
FTSE 100 Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.