



Stocks To Extend Surge Higher On Recovery Optimism
As lockdown measures continue to ease, investors shrugged off geopolitical tensions and civil unrest on the streets of the US
Share this:
As lockdown measures continue to ease, investors shrugged off geopolitical tensions and civil unrest on the streets of the US for Wall Street to finish at its highest level in three months.
The optimism carried over into Asia, with the Nikkei rising to its best level since February boosted by the first expansionary reading for Chinese services PMI in four months. The Caixin service sector activity data jumped to 55 in May, its strongest reading in almost a decade and jumping from 44 in the previous month. The data adds to mounting evidence hat the Chinese economic recovery is underway following the coronavirus lockdown earlier in the year.
Positivity in Asia looks set to spill over into Europe, with bourses pointing to a stronger start. The markets are keen to fall back into the familiar rhythm of “the only way s up”, boosted by cheap money and reopening optimism without fully digesting the economic hit and scars which are being left behind. Despite the downside risks, investors are remaining firmly focused on the positives.
Equities are pushing higher, along with oil and the antipodeans, meanwhile safe havens US Dollar and gold are once again on the back foot.
Service sector PMIs
Today’s PMI readings could be good example of the almost blind optimism in the markets. PMI readings for the Eurozone and the UK are expected. Spain is expected to see the service sector pmi rebound from 7.1 to 25 in May, whilst activity in Italy’s service sector is expected to have jumped from 10.8 to 26.5. The optimists in the market will focus on the huge improvement in activity in the sector, whilst the pessimists would be drawn to the fact that activity remain deep in contraction. As they saying goes, optimism is blind optimism.
Unemployment figures in Europe are expected to show a slow creep northward. However, the headline numbers are not expected to climb as high as US due to a range of government programmes that pay companies to keep staff employed even when they are not working.
ADP in focus
Today’s US ADP reading is expected to be another fine example of how keen the market is to ignore economic scars being left behind. Expectations are for a 9 million drop in private payrolls in May. A shocking number by all accounts. However, it would be a significant improvement on April’s 25 million decline. With the markets so focused on the recovery, May’s numbers are not expected to cause a stir.
Today’s US ADP reading is expected to be another fine example of how keen the market is to ignore economic scars being left behind. Expectations are for a 9 million drop in private payrolls in May. A shocking number by all accounts. However, it would be a significant improvement on April’s 25 million decline. With the markets so focused on the recovery, May’s numbers are not expected to cause a stir.
Oil supported as inventories decline
The broad risk on sentiment, a weaker US Dollar and improving supply and demand fundamentals are providing support for oil prices. According to API data, inventories declined -0.483 million barrels in the week 29th May, versus the addition of 8,731 million barrels the previous week. Attention is turning to the June OPEC meeting; traders are finding some reassurance from indications that Saudi Arabia and Russia are moving closer to agreeing a deal to extend output cuts.
The broad risk on sentiment, a weaker US Dollar and improving supply and demand fundamentals are providing support for oil prices. According to API data, inventories declined -0.483 million barrels in the week 29th May, versus the addition of 8,731 million barrels the previous week. Attention is turning to the June OPEC meeting; traders are finding some reassurance from indications that Saudi Arabia and Russia are moving closer to agreeing a deal to extend output cuts.
WTI levels to watch
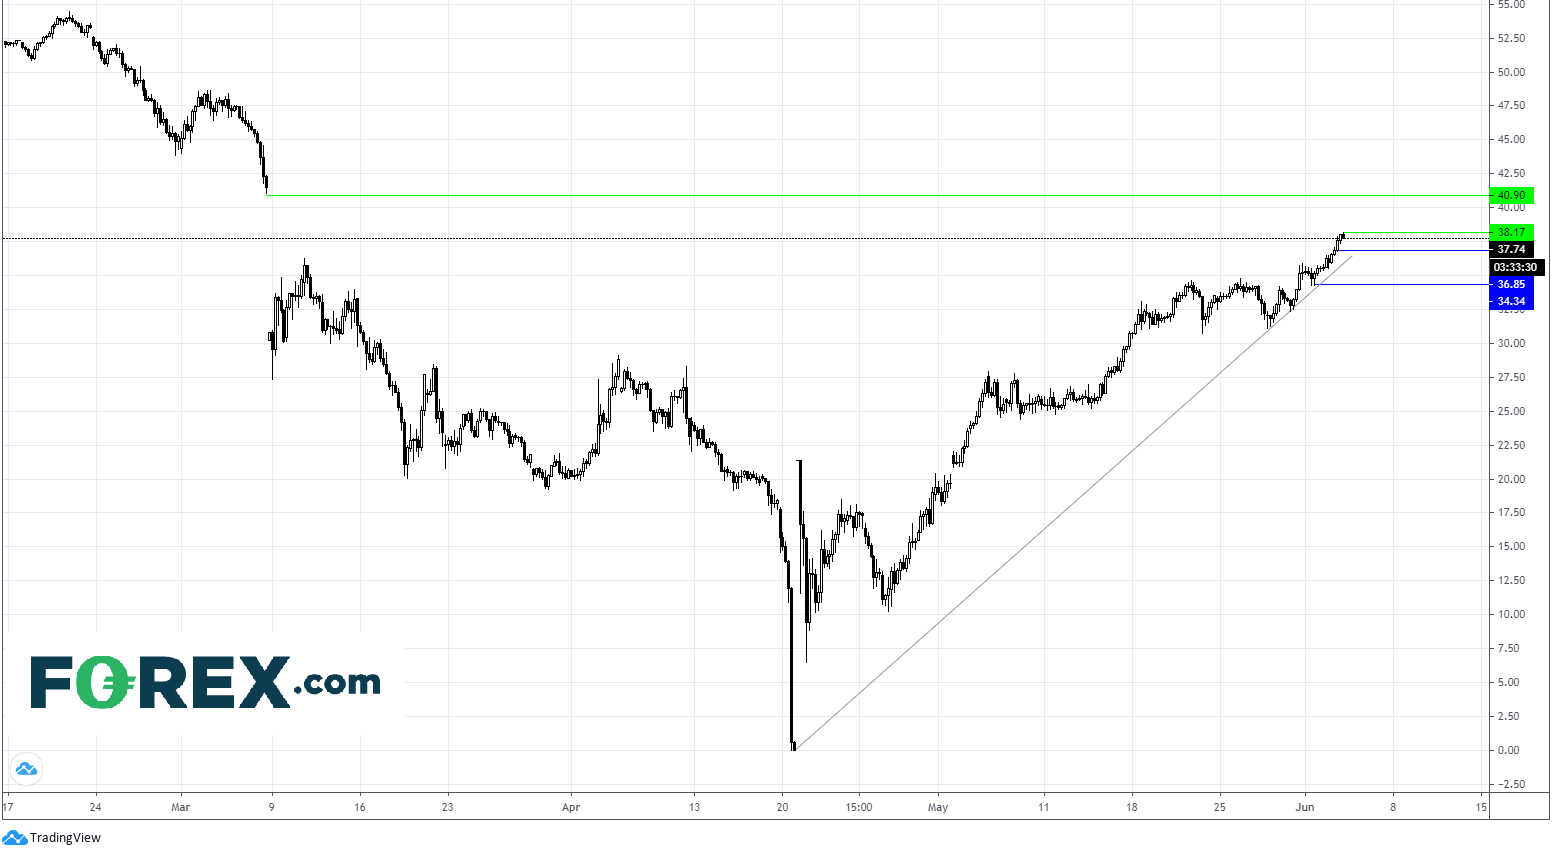
WTI is trading +2.5% in early trade at $37.87, it remains above the ascending trendline on 4 hour chart as it continue to cross the gap back towards early March’s pre- coronavirus $40.00 level.
Immediate resistance can be seen at $38.15 (overnight high) prior to $40.
Immediate support can be seen at 36.80 (today’s low) prior to $36.11 trendline support and $34.30 low (June 1st)
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Crude Oil Analysis: Geopolitical Risk Continues to Drive the WTI Barrel Higher
During recent trading sessions, a new wave of buying momentum has continued to gain relevance around WTI crude oil price action. Over the last three trading sessions, the market has maintained a bullish streak and is now up more than 5.5%, highlighting significant buying pressure in the short term.

Crude Oil Forecast WTI Prices Come Under Pressure as Middle East Risks Ease
Over the last two trading sessions, WTI crude oil has once again displayed a notable bearish bias, with prices falling nearly 6%. Part of this renewed selling pressure has been driven by recent developments in the Middle East, which have helped temporarily ease the geopolitical tensions that had supported the oil risk premium in previous weeks.
Crude Oil Analysis WTI barrel remains weak after OPEC+ announcements
Crude oil continues to face difficult trading sessions in the short term. Over the last 5 trading sessions on average, WTI remains down close to -3.5%, with consistent movements below the 70-dollar area. This continues to highlight a selling bias that has remained in place for several weeks.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.