



US open futures point lower after record rally
US futures pause for breath after a record rally on Monday. JOLTS job opening data in focus.
Share this:
US futures
Dow futures -0.2% at 33342
S&P futures -0.2% at 34060
Nasdaq futures -0.02% at 132590
In Europe
FTSE +1.3% at 6817
Dax +1% at 15260
Euro Stoxx +0.7% at 3975
Learn more about trading indices
Futures slip but economic optimism remains
US futures are pointing to a slower start on Tuesday after rallying to record highs in the previous session. The S&P 500 closed 1.4% higher on Monday at a record 4076 whilst the Dow Jones rose 1.1% to close at an all time high of 33527.
The strong gains come amid on growing expectations of a strong US economic recovery. A blowout US jobs report on Friday, followed by a surging in service sector activity reported on Monday and an accelerating vaccine programme suggest that the US economic recovery is firmly on track.
Further evidence of the recovering US labour market is expected from the JOLTS job openings data at 13:00 UTC.
Stocks in focus
BP ADR - trades +3% pre-market after the oil giant said it will achieve its $35 billion net debt target about a year earlier than expected, which means that it can restart its share buyback programme.
Carnival – trades +0.5% pre-market after 5% gains in the previous session is due to report early in the session.
Snap- trades +2.6% pre-market after Atlantic Equities upgraded its rating to overweight from neutral.
Where next for Snap share price?
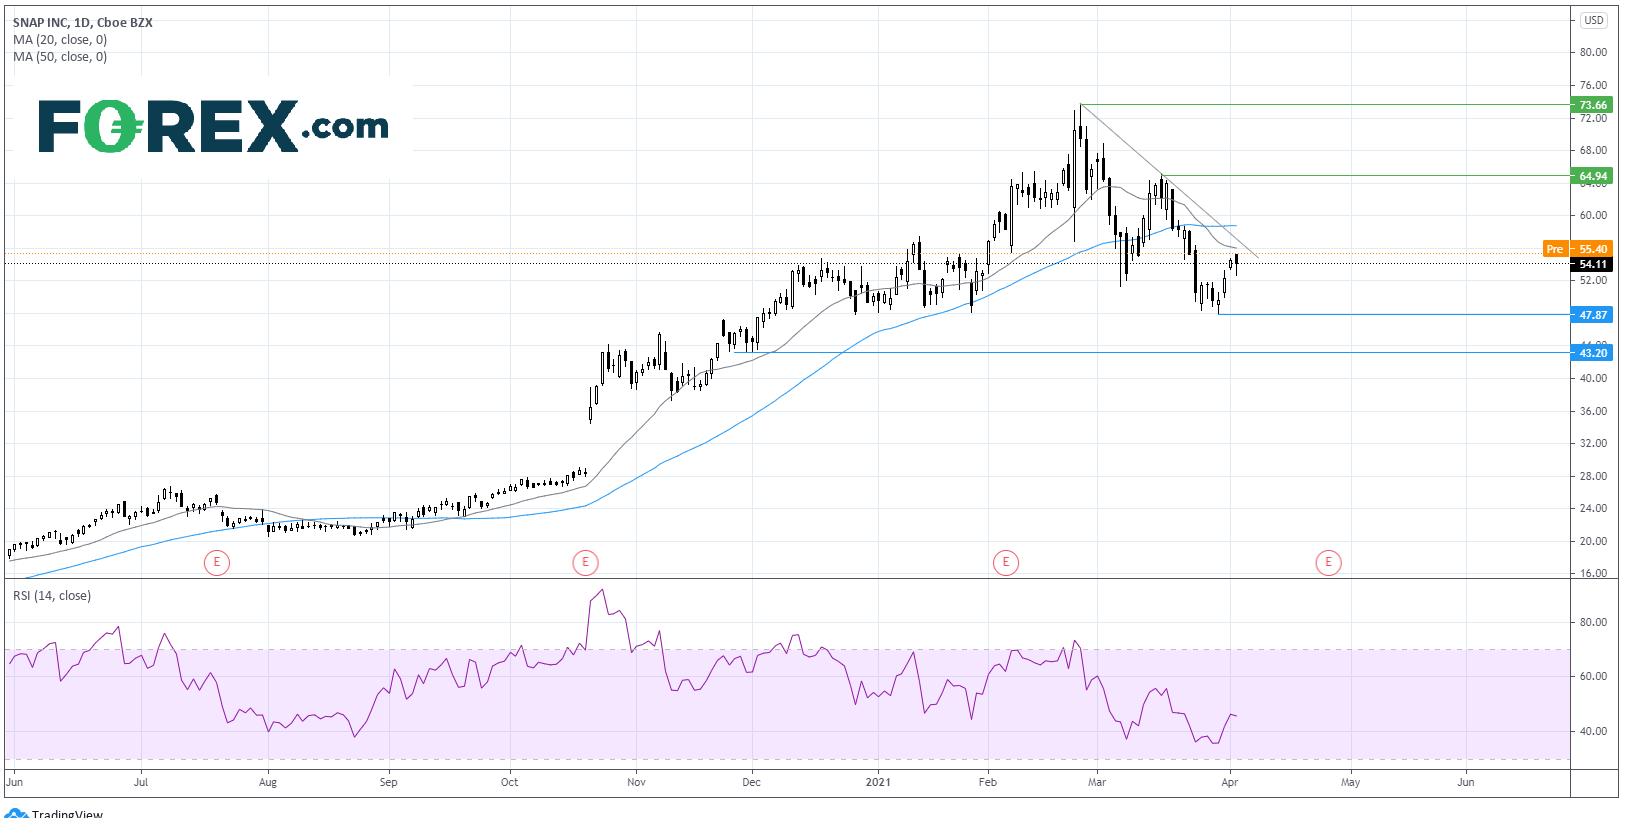
After trading steadily higher across the past year Snap hit an all time high of 73.60 in late February, before heading lower.
Price trades below its descending trendline dating back to late February. However, the jump higher pre-market is expected to see the price test resistance at the descending trendline and the 20 sma. A move above here could see the 50 sma tested at 59.00. should the bulls break above this level the move higher could gain momentum.
Failure to break above 56.50 the descending trendline and 20 sma could see the price rebound lower towards the March low and year to date low around 48.00. This is an important support level which has capped losses several times across the year. A break out below 48.00 could see a deeper selloff towards 43.20.
China asks for restrain in bank lending
China’s central bank has asked the country’s largest commercial banks to rein in their lending. The request comes after lending surged in the first two months of the year and is the latest effort by Beijing to rein in borrowing which surged through the pandemic to support the economic recovery.
The news hit demand for Chinese equities hard and the Shanghai Shenzhen 300 fell when the rest of the global markets were following wall street higher.
FX – EUR flat despite upbeat data, AUD lower post RBA
The US Dollar is attempting to recover after declining 0.4% in the previous session, its largest one -day decline in 3 weeks.
EUR/USD – trades unchanged at 1.18 despite upbeat Investor Sentiment Index. The index points to stronger morale in April, hitting 13.1, up from 5 in March and beating forecasts of 6.7.
AUD/USD – trades lower after the Reserve Bank of Australia left rates unchanged as expected. The central bank provided no clues over the future of its bond buying programme.
GBP/USD -0.5% at 1.3825
EUR/USD trades +0.03% at 1.1807
Oil rebounds on eco nomic recovery optimism
After diving 4.5% in the previous session, oil prices are rebounding today. Optimism surrounding the global economic recovery is helping to lift oil ahead of API stock pile data later today. Upbeat Chinese data overnight, following on from much stronger than expected US ISM service sector PMI data has helped calm nerves of rising supply.
Concerns over supply sent oil prices tumbling on Monday as the OPEC + group are expected to start increasing supply as from May.
US crude trades +1.6% at $59.62
Brent trades +1.4% at $63.01
Learn more about trading oil here.
The complete guide to trading oil markets
Analyst Fiona Cincotta looks at the price action of WTI and levels to watch here.
Looking ahead
15:00 US JOLTS Job Openings (Feb)
21:00 API weekly crude oil stock piles
US futures
Dow futures -0.2% at 33342
S&P futures -0.2% at 34060
Nasdaq futures -0.02% at 13590
In Europe
FTSE +1.3% at 6817
Dax +1% at 15260
Euro Stoxx +0.7% at 3975
Learn more about trading indices
Futures slip but economic optimism remains
US futures are pointing to a slower start on Tuesday after rallying to record highs in the previous session. The S&P 500 closed 1.4% higher on Monday at a record 4076 whilst the Dow Jones rose 1.1% to close at an all time high of 33527.
The strong gains come amid on growing expectations of a strong US economic recovery. A blowout US jobs report on Friday, followed by a surging in service sector activity reported on Monday and an accelerating vaccine programme suggest that the US economic recovery is firmly on track.
Further evidence of the recovering US labour market is expected from the JOLTS job openings data at 13:00 UTC.
Stocks in focus
BP ADR - trades +3% pre-market after the oil giant said it will achieve its $35 billion net debt target about a year earlier than expected, which means that it can restart its share buyback programme.
Carnival – trades +0.5% pre-market after 5% gains in the previous session is due to report early in the session.
Snap- trades +2.6% pre-market after Atlantic Equities upgraded its rating to overweight from neutral.
Where next for Snap share price?
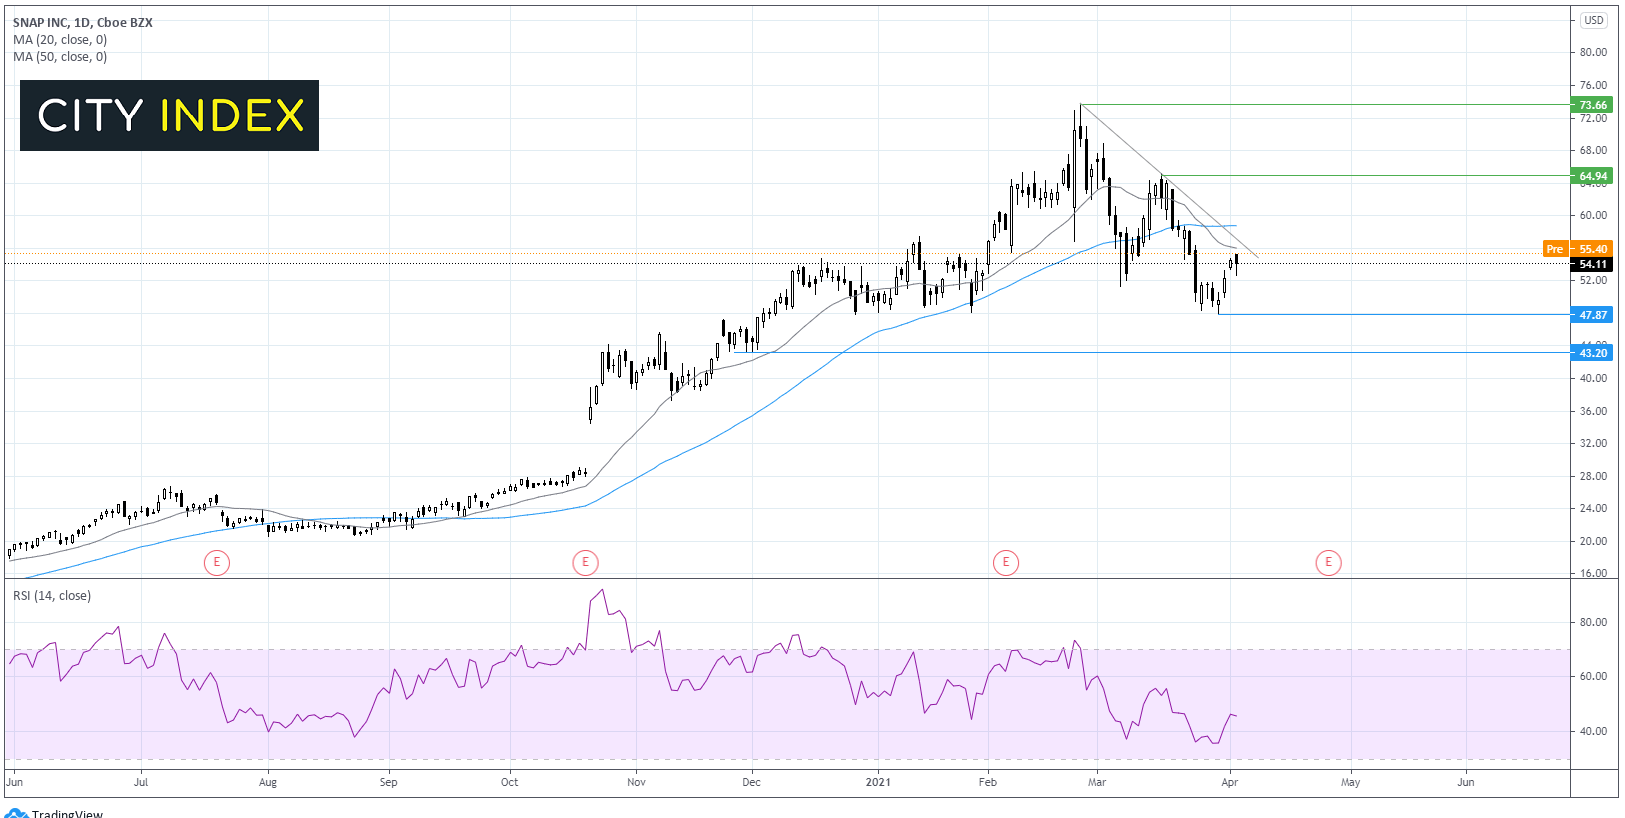
After trading steadily higher across the past year Snap hit an all time high of 73.60 in late February, before heading lower.
Price trades below its descending trendline dating back to late February. However, the jump higher pre-market is expected to see the price test resistance at the descending trendline and the 20 sma. A move above here could see the 50 sma tested at 59.00. should the bulls break above this level the move higher could gain momentum.
Failure to break above 56.50 the descending trendline and 20 sma could see the price rebound lower towards the March low and year to date low around 48.00. This is an important support level which has capped losses several times across the year. A break out below 48.00 could see a deeper selloff towards 43.20.
China asks for restrain in bank lending
China’s central bank has asked the country’s largest commercial banks to rein in their lending. The request comes after lending surged in the first two months of the year and is the latest effort by Beijing to rein in borrowing which surged through the pandemic to support the economic recovery.
The news hit demand for Chinese equities hard and the Shanghai Shenzhen 300 fell when the rest of the global markets were following wall street higher.
FX – EUR flat despite upbeat data, AUD lower post RBA
The US Dollar is attempting to recover after declining 0.4% in the previous session, its largest one -day decline in 3 weeks.
EUR/USD – trades unchanged at 1.18 despite upbeat Investor Sentiment Index. The index points to stronger morale in April, hitting 13.1, up from 5 in March and beating forecasts of 6.7.
AUD/USD – trades lower after the Reserve Bank of Australia left rates unchanged as expected. The central bank provided no clues over the future of its bond buying programme.
GBP/USD -0.5% at 1.3825
EUR/USD trades +0.03% at 1.1807
Oil rises ahead of OPEC+ meeting
After diving 4.5% in the previous session, oil prices are rebounding today. Optimism surrounding the global economic recovery is helping to lift oil ahead of API stock pile data later today. Upbeat Chinese data overnight, following on from much stronger than expected US ISM service sector PMI data has helped calm nerves of rising supply.
Concerns over supply sent oil prices tumbling on Monday as the OPEC + group are expected to start increasing supply as from May.
US crude trades +1.6% at $59.62
Brent trades +1.4% at $63.01
Learn more about trading oil here.
The complete guide to trading oil markets
Analyst Fiona Cincotta looks at the price action of WTI and levels to watch here.
Looking ahead
15:00 US JOLTS Job Openings (Feb)
21:00 API weekly crude oil stock piles
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Wall Street Forecast: DJIA falls as treasury yields hit new highs and ahead of the Trump-Xi summit
U.S. stocks are falling, further extending losses from the previous session, as oil prices move higher alongside Treasury yields and caution reigns ahead of the summit between President Trump and Xi Jinping.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.