



US open: Stocks fall with inflation data, earnings season in focus
US stocks are set to fall on the open as investors look ahead to Wednesday's inflation report and earnings season starting on Thursday.
Share this:

US futures
Dow futures -0.65% at 31140
S&P futures -0.15% at 3870
Nasdaq futures -0.94% at 12052
In Europe
FTSE -0.5% at 7160
Dax -0.85% at 12997
Euro Stoxx -0.78% at 3483
Stocks fall at the start of the week
US stocks are pointing to a weaker start on Monday as investors look cautiously ahead to the beginning of earnings season and inflation data due on Wednesday.
The inflation report comes hot on the heels of a strong US non-farm payroll report which showed 372k jobs were added in June, defying recession fears. Any slowdown being felt elsewhere in the US economy has yet to show up in the employment report.
The solid report and strong wage growth give the green light to the Fed to keep hiking interest rates. Expectations for a 75 bp rate hike remain strong, and now investors aren’t discounting a 100bp hike.
The banks will kick off earnings season on Thursday. There are growing fears that earning season could spark a selloff with profits forecasts seemingly far too upbeat for the mounting recession risks.
Adding to the downbeat mood are rising COVID cases in China. Mass testing started again in Shanghai after the new Omicron sub-variant, which is more contagious, was found. Cases are growing quickly, raising fears that another lockdown could be on its way.
In corporate news:
Twitter trades 5% lower premarket after Musk walks away from the deal and the social media platform threatens to sue him. This is likely to be a long-drawn-out process in the courts, and Musk will be looking to get a much-reduced price for his purchase, given the massive share price drop since the offer was made.
Where next for the Nasdaq?
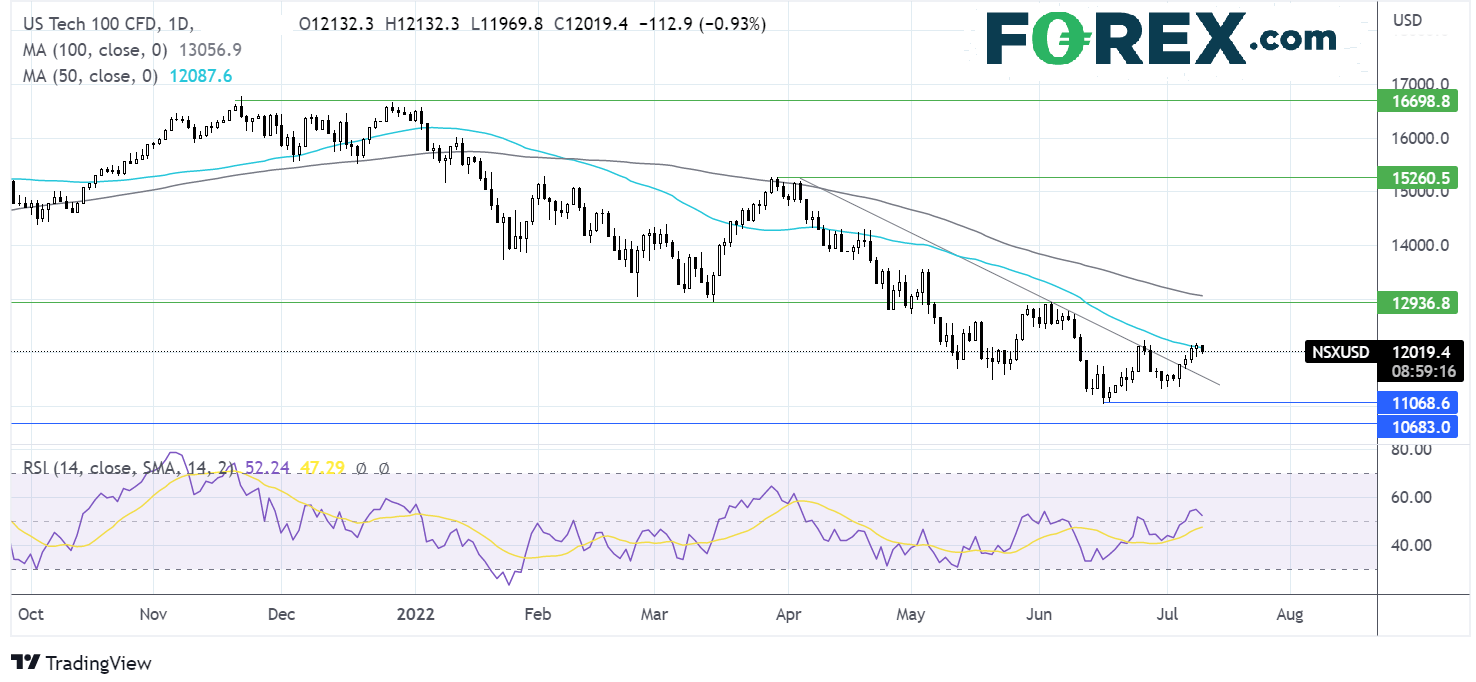
The Nasdaq has rebounded off the 2022 low of 11740, rising above its multi-month falling trendline, but has run into resistance at the 50 sma at 12090. Buyers would need a move over this level to create a higher high and aim towards 12935, the June high. Sellers would look for a move below 11525, the falling trendline support, and 11300, last week’s low ahead of 11360.
FX markets – USD rises, EUR drops towards parity.
USD is rising, extending gains after the strong US NFP on Friday and amid increasing expectations that the Fed will hike rates, if not by 75 bp, then by 100bp!
EURUSD is heading lower over fears for energy security as the Nord Stream 1 is closed for scheduled maintenance, but fears are rising that Russia may not switch the gas supply back on in 10 days when the works are over. This could cause a recession in Europe.
GBP/USD is falling as the dust settles on Boris Johnson’s resignation. The stepping down of the PM leaves the UK in limbo while a leadership contest takes place, which could take weeks or months. This is when the economic outlook deteriorates, and Brexit remains a mess.
GBP/USD -0.5% at 1.1926
EUR/USD -0.7% at 1.076
Oil falls as China COVID cases rise.
Oil prices are falling, adding to last week’s decline as demand concerns continue to drive the price lower. While recession fears sent commodity stocks lower last week, concerns over a resurgence of COVID in China and more lockdown restrictions are hurting the demand outlook this week.
The new Omicron sub-variant in Shanghai is rattling the markets outweighing supply concerns. Cases are back at the highest level since May, with more mass testing and growing fears of another extended lockdown.
Concerns over a potential cap on Russian oil prices and ongoing recession fears are also being weighed up by the market. Furthermore, worries overflow along the Caspian Pipeline Consortium remain. While oil is still flowing, following the Russian court’s decision to cut supply, this could soon dry up.
The risks in the market are becoming much more two-sided than they have been for a while
WTI crude trades -2.2% at $100.16
Brent trades -1.94% at $103.70
Looking ahead
19:00 Fed Williams speech
US futures
Dow futures -0.65% at 31140
S&P futures -0.15% at 3870
Nasdaq futures -0.94% at 12052
In Europe
FTSE -0.5% at 7160
Dax -0.85% at 12997
Euro Stoxx -0.78% at 3483
Learn more about trading indices
Stocks fall at the start of the week
US stocks are pointing to a weaker start on Monday as investors look cautiously ahead to the beginning of earnings season and inflation data due on Wednesday.
The inflation report comes hot on the heels of a strong US non-farm payroll report which showed 372k jobs were added in June, defying recession fears. Any slowdown being felt elsewhere in the US economy has yet to show up in the employment report.
The solid report and strong wage growth give the green light to the Fed to keep hiking interest rates. Expectations for a 75 bp rate hike remain strong, and now investors aren’t discounting a 100bp hike.
The banks will kick off earnings season on Thursday. There are growing fears that earning season could spark a selloff with profits forecasts seemingly far too upbeat for the mounting recession risks.
Adding to the downbeat mood are rising COVID cases in China. Mass testing started again in Shanghai after the new Omicron sub-variant, which is more contagious, was found. Cases are growing quickly, raising fears that another lockdown could be on its way.
In corporate news:
Twitter trades 5% lower premarket after Musk walks away from the deal and the social media platform threatens to sue him. This is likely to be a long-drawn-out process in the courts, and Musk will be looking to get a much-reduced price for his purchase, given the massive share price drop since the offer was made.
Read more about Twitter’s fall.
Where next for the Nasdaq?
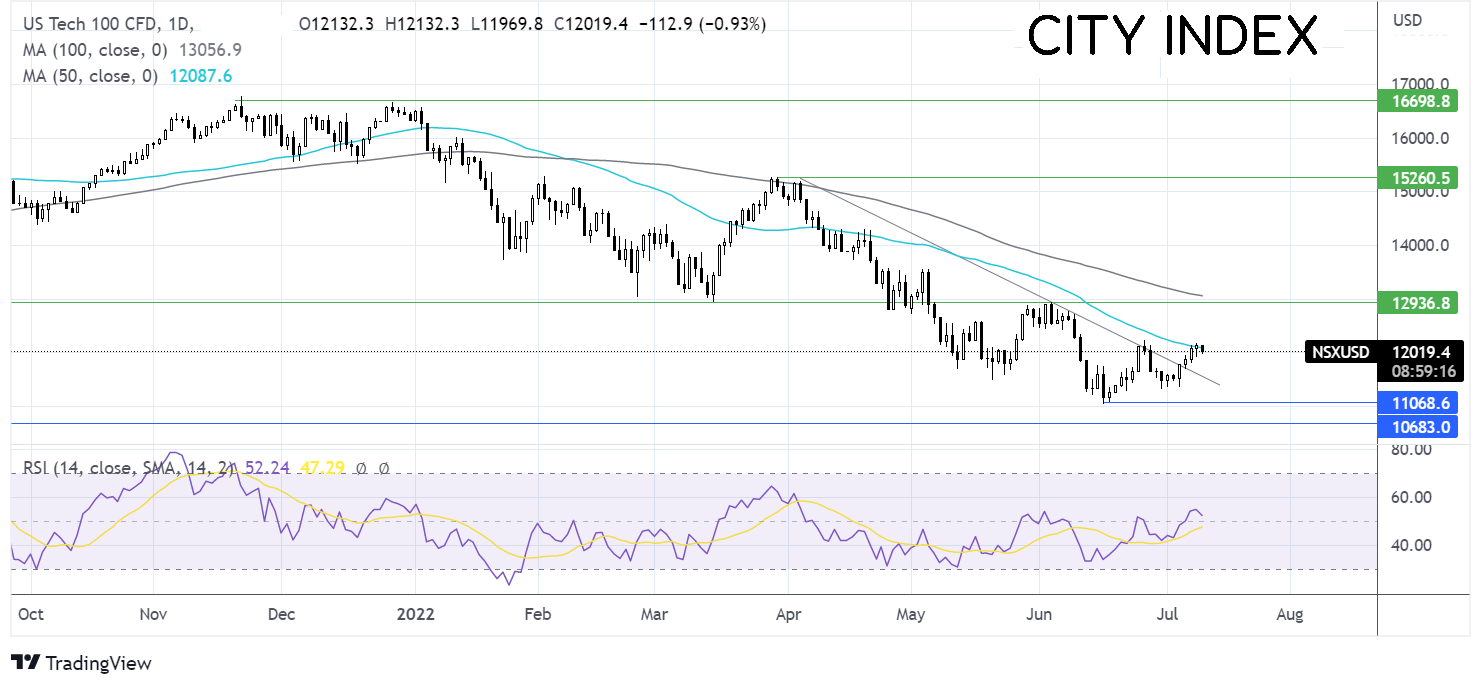
The Nasdaq has rebounded off the 2022 low of 11740, rising above its multi-month falling trendline, but has run into resistance at the 50 sma at 12090. Buyers would need a move over this level to create a higher high and aim towards 12935, the June high. Sellers would look for a move below 11525, the falling trendline support, and 11300, last week’s low ahead of 11360.
FX markets – USD rises, EUR drops towards parity.
USD is rising, extending gains after the strong US NFP on Friday and amid increasing expectations that the Fed will hike rates, if not by 75 bp, then by 100bp!
EURUSD is heading lower over fears for energy security as the Nord Stream 1 is closed for scheduled maintenance, but fears are rising that Russia may not switch the gas supply back on in 10 days when the works are over. This could cause a recession in Europe.
GBP/USD is falling as the dust settles on Boris Johnson’s resignation. The stepping down of the PM leaves the UK in limbo while a leadership contest takes place, which could take weeks or months. This is when the economic outlook deteriorates, and Brexit remains a mess.
GBP/USD -0.3% at 1.1923
EUR/USD -0.2% at 1.0078
Oil falls as China COVID cases rise.
Oil prices are falling, adding to last week’s decline as demand concerns continue to drive the price lower. While recession fears sent commodity stocks lower last week, concerns over a resurgence of COVID in China and more lockdown restrictions are hurting the demand outlook this week.
The new Omicron sub-variant in Shanghai is rattling the markets outweighing supply concerns. Cases are back at the highest level since May, with more mass testing and growing fears of another extended lockdown.
Concerns over a potential cap on Russian oil prices and ongoing recession fears are also being weighed up by the market. Furthermore, worries overflow along the Caspian Pipeline Consortium remain. While oil is still flowing, following the Russian court’s decision to cut supply, this could soon dry up.
The risks in the market are becoming much more two-sided than they have been for a while
WTI crude trades +2.2% at $100.16
Brent trades -1.94% at $103.70
Learn more about trading oil here.
Looking ahead
19:00 Fed Williams speech
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.
Equity Indices Q4, 2026 Outlook: Cracks Begin to Show
There's still an open door for a melt-up in the S&P 500 and Nasdaq but the Dow and Russell 2000 are looking more vulnerable, and until calm hits the Treasuries market there's a higher probability for volatility. The big question is whether that's a next quarter theme or not.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.