



US open: Stocks head lower, Twitter, big tech in focus
US stocks are set for a softer start. Tech stocks are in focus the day after Twitter agreed to Elon Musk's takeover and as big tech earnings ramp up after the close.
Share this:

US futures
Dow futures -0.7 % at 33850
S&P futures -0.62% at 4276
Nasdaq futures -0.6% at 13440
In Europe
FTSE +0.7% at 7437
Dax +0.7% at 14020
Euro Stoxx +0.8% at 3790
Learn more about trading indices
Twitter headlines dominate
US stocks are set for a weaker start, after a solid finish in the previous session and ahead of the start of big tech earnings. Inflation has been a key theme throughout earnings season so far and investors will continue to look for insights into the impact of inflation and consumer spending as the results roll in.
On the data from US durable goods were weaker than forecast rising 0.8% in March, up from 1.7% in February, but still short of the 1% forecast.
Looking ahead US consumer confidence data is due later this afternoon and is expected to rise to 108.00 from a 10-month low. This would mark the first time that it improves in four months, amid surging inflation. Interestingly despite consumer confidence plunging Americans haven’t stopped spending, with retail sales still holding relatively firm.
In corporate news:
Twitter rises 0.2% premarket as investors continue digesting the news that Elon Musk has bought the social media firm after the board agreed to the $44 billion deal to take the company private. Elon Musk has already hinted that he may not look to make Twitter more monetizable, in fact, his aim is quite different, to make it a more transparent fairer platform for free speech.
Looking ahead, earnings will step up a notch with big tech earnings moving into focus. Broadly speaking, earnings growth is expected to slow. Although, Microsoft, which reports after the close today is set to see record earnings growth. Even so, the share price has underperformed.
Alphabet is also due to report after the close. Expectations are for EPS of $25.63 on revenue of $68.13 billion.
More news on the stocks to watch
Where next for the S&P500?
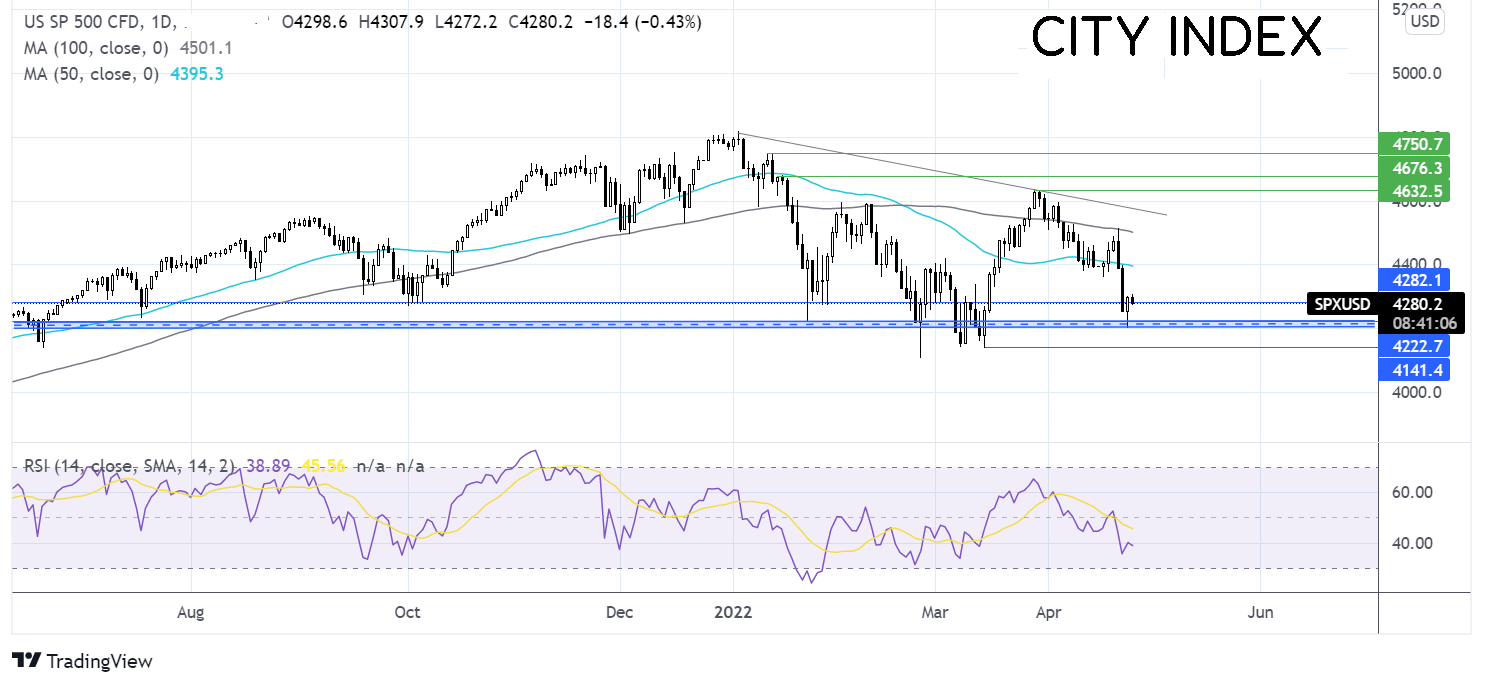
The S&P500 ran into resistance at the 100 sma at 4510 and rebounded lower breaking below the 50 sma falling to support at 4200. The RSI is below 50 and supports further downside while it trades out of the oversold territory. The zone 4210/4200 could be strong support for the index with a break below here opening the door to 4140. Meanwhile, buyers could be encouraged by the long lower wick on the candle to 4200, suggesting that the price failed to find much acceptance at these lower levels, helping the price higher. Buyers are currently testing resistance at 4280 with a move above here exposing the 50 sma at 4400.
FX markets USD rises, EUR looks to 2020 low.
USD is extending gains, driven by a combination of safe-haven flows and hawkish Fed expectations. Attention will now turn to US consumer confidence data for further clues over the health of the economy
EUR/USD trades below 1.07 as euro bulls shrug off hawkish ECB chatter and USD strength drags the pair lower. There is no high impacting EZ data so the greenback is likely to be the biggest influence on the pair. Bears will look for a move towards 1.0637 the 2020 low.
GBP/USD -0.4% at 1.2643
EUR/USD -0.35% at 1.0673
Oil steadies as demand concerns remain
Oil prices are holding steady after steep losses in the previous session. Concerns over the demand outlook saw oil prices drop over $7 per barrel at one point yesterday before some losses were clawed back and oil settled $2 lower.
China is the largest importer of oil so mass testing across major cities is understandably unnerving the market. China’s demand is already down some 1 million barrels per day with the Shanghai lockdown. Should more districts impose strict lockdown rules then demand will deteriorate further.
Supply remains tight which is keeping the price elevated. Europe appears to be moving closer to putting plans into place to phase out Russian oil and gas imports. Germany has given the go-ahead to do so as soon as possible.
WTI crude trades +0.3% at $98.60
Brent trades +0.6% at $102.80
Learn more about trading oil here.
Looking ahead
15:00 US consumer confidence
21:30 API crude oil stock piles
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
US futures
Dow futures -0.7 % at 33850
S&P futures -0.62% at 4276
Nasdaq futures -0.6% at 13440
In Europe
FTSE +0.7% at 7437
Dax +0.7% at 14020
Euro Stoxx +0.8% at 3790
Twitter headlines dominate
US stocks are set for a weaker start, after a solid finish in the previous session and ahead of the start of big tech earnings. Inflation has been a key theme throughout earnings season so far and investors will continue to look for insights into the impact of inflation and consumer spending as the results roll in.
On the data from US durable goods were weaker than forecast rising 0.8% in March, up from 1.7% in February, but still short of the 1% forecast.
Looking ahead US consumer confidence data is due later this afternoon and is expected to rise to 108.00 from a 10-month low. This would mark the first time that it improves in four months, amid surging inflation. Interestingly despite consumer confidence plunging Americans haven’t stopped spending, with retail sales still holding relatively firm.
In corporate news:
Twitter rises 0.2% premarket as investors continue digesting the news that Elon Musk has bought the social media firm after the board agreed to the $44 billion deal to take the company private. Elon Musk has already hinted that he may not look to make Twitter more monetizable, in fact, his aim is quite different, to make it a more transparent fairer platform for free speech.
Looking ahead, earnings will step up a notch with big tech earnings moving into focus. Broadly speaking, earnings growth is expected to slow. Although, Microsoft, which reports after the close today is set to see record earnings growth. Even so, the share price has underperformed.
Alphabet is also due to report after the close. Expectations are for EPS of $25.63 on revenue of $68.13 billion.
More news on the stocks to watch
Where next for the S&P500?
The S&P500 ran into resistance at the 100 sma at 4510 and rebounded lower breaking below the 50 sma falling to support at 4200. The RSI is below 50 and supports further downside while it trades out of the oversold territory. The zone 4210/4200 could be strong support for the index with a break below here opening the door to 4140. Meanwhile, buyers could be encouraged by the long lower wick on the candle to 4200, suggesting that the price failed to find much acceptance at these lower levels, helping the price higher. Buyers are currently testing resistance at 4280 with a move above here exposing the 50 sma at 4400.

FX markets USD rises, EUR looks to 2020 low.
USD is extending gains, driven by a combination of safe-haven flows and hawkish Fed expectations. Attention will now turn to US consumer confidence data for further clues over the health of the economy
EUR/USD trades below 1.07 as euro bulls shrug off hawkish ECB chatter and USD strength drags the pair lower. There is no high impacting EZ data so the greenback is likely to be the biggest influence on the pair. Bears will look for a move towards 1.0637 the 2020 low.
GBP/USD -0.4% at 1.2643
EUR/USD -0.35% at 1.0673
Oil steadies as demand concerns remain
Oil prices are holding steady after steep losses in the previous session. Concerns over the demand outlook saw oil prices drop over $7 per barrel at one point yesterday before some losses were clawed back and oil settled $2 lower.
China is the largest importer of oil so mass testing across major cities is understandably unnerving the market. China’s demand is already down some 1 million barrels per day with the Shanghai lockdown. Should more districts impose strict lockdown rules then demand will deteriorate further.
Supply remains tight which is keeping the price elevated. Europe appears to be moving closer to putting plans into place to phase out Russian oil and gas imports. Germany has given the go-ahead to do so as soon as possible.
WTI crude trades +0.3% at $98.60
Brent trades +0.6% at $102.80
Looking ahead
15:00 US consumer confidence
21:30 API crude oil stock piles
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Gold forecast: XAU/USD could take a larger dive after the big rise in yields
Gold prices have been falling in the last few days after last week’s post-FOMC pop faded amid rising interest rate expectations, higher oil prices and a strengthening US dollar. As before, I wasn’t convinced gold would thrive in the current macro backdrop.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.