



US Stocks Mixed as Fed Cut Bets Strengthen; DAX Breaks 24,000
US markets ended mixed with S&P 500 flat and Nasdaq slightly higher, while Russell 2000 outperformed. Fed cut odds rose to 87% ahead of next week’s decision. Meta surged on AI focus, Amazon slipped on contract uncertainty. Germany 40 broke above 23,740 and trades near 24,011, signaling bullish momentum toward 24,200. Copper hit record highs on tariff fears; luxury goods and logistics sectors show resilience.
Share this:
US Markets
- US stocks ended mixed: S&P 500 flat, Nasdaq slightly higher, Russell outperformed. Amazon fell 1.4%, limiting gains.
- Meta rose ~3.5% after reports of cutting Metaverse spending by 30% to focus on AI, though index boost was short-lived.
- Labour data: Challenger layoffs and non-farm payroll losses slowed; Chicago Fed unemployment estimate improved slightly; jobless claims hit a 3-year low, easing labour concerns.
- Rate-cut expectations strengthened: markets price 87% chance of a 25bp cut in December, relying on secondary indicators due to delayed payrolls report.
- Corporate movers: Salesforce and Meta up on positive outlooks; Amazon down on USPS contract uncertainty.
- Consumer stocks diverged: Kroger fell on weaker sales outlook; Dollar General surged 14% on profit upgrade; Hormel rose on strong guidance.
- Broader tone constructive: weaker dollar and dovish Fed expectations; focus on delayed PCE inflation data and next week’s Fed decision.
Logistics Sector
- Logistics faces structural change: AI expected to drive growth in route planning, customs, and pricing.
- Growth historically tied to global GDP; analysts see tech and AI accelerating expansion beyond that.
- Industry remains fragmented: Top 20 firms hold only 30–40% share; consolidation could create opportunities.
- Many firms cautious on AI integration; clearer strategies may boost valuations in 2026.
- Global freight and logistics index up ~20% since mid-October; short-term profit-taking possible due to high valuations and trade uncertainty.
Copper Market
- Copper hit record $11,540/ton on LME.
- Drivers: large withdrawals from Asian warehouses amid fears of higher US import tariffs; current 50% tariff applies to semi-finished products, raw ores exempt for now.
- Trump signaled review of exemptions in 2026, prompting US stockpiling.
- Supply disruptions persist: major Congo mine cut forecasts; doubts over restart of Indonesia’s second-largest mine.
- Short-term upside limited: 2026 supply deficit priced in; weaker Chinese demand may cap gains.
European Luxury Goods
- European discretionary sector resilient despite global uncertainty.
- MSCI Europe Consumer Discretionary firms well-positioned for higher margins and shareholder returns.
- EPS expected to grow 48% over next 12 months; valuations stabilized.
- 2026 price-to-book ratio forecast: 16.5.
- Luxury segment offers long-term potential with strong profitability.
DAX Technical Analysis 1 Day Chart
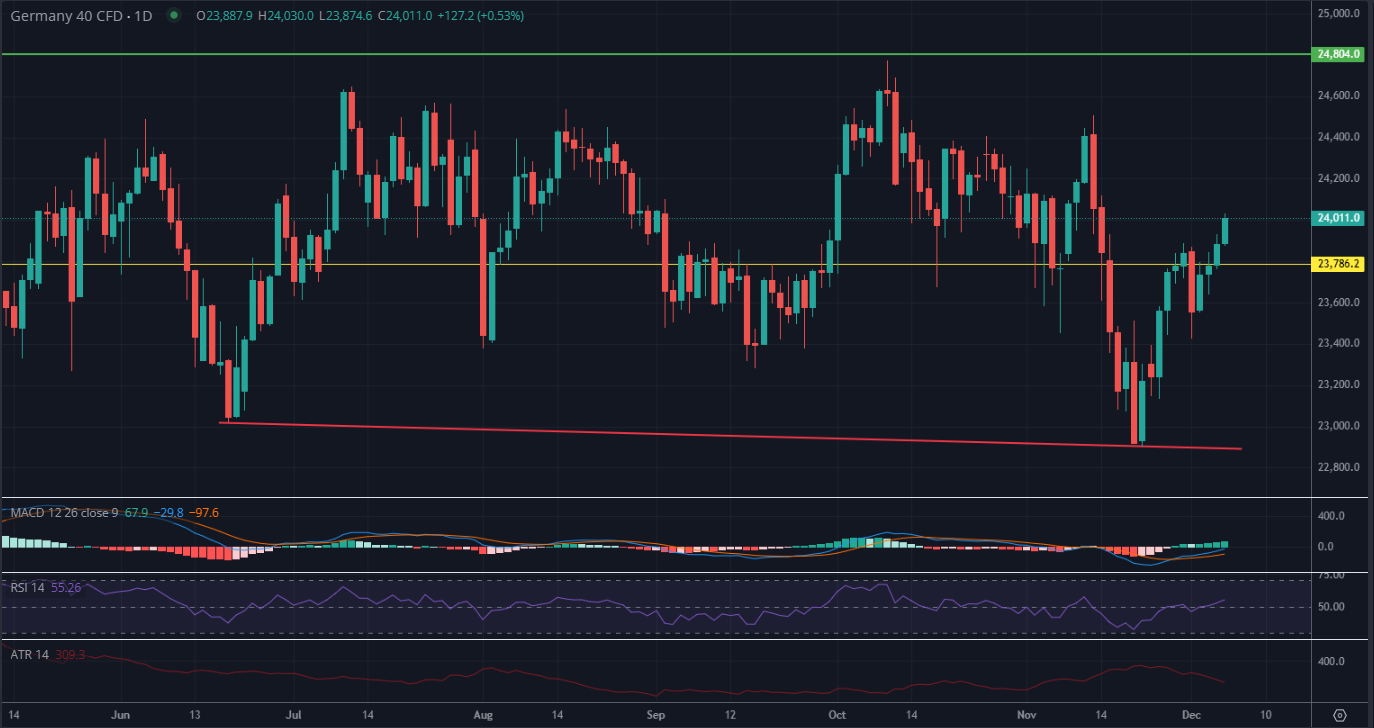
The daily chart shows Germany 40 breaking above the critical pivot level at 23,740 and currently trading near 24,011, signaling a strong bullish continuation from the recent rebound off the 22,900 support zone. This move shifts the short-term bias toward bullish within the broader consolidation range of 22,900 to 24,884. The breakout above 23,740 is significant because it invalidates the prior resistance structure and opens the path toward the next major resistance at 24,200 and ultimately 24,884. Price action now suggests momentum is favoring buyers, but the overall trend remains range-bound until a decisive close above 24,884 confirms a breakout.
Momentum indicators reinforce the bullish outlook. MACD is positive and widening, indicating strengthening upward momentum, while RSI at 55.29 is above neutral but still far from overbought, leaving room for further upside. ATR at 309.3 shows volatility has increased, which aligns with the strong upward move. If price sustains above 24,000, the next target zone is 24,200–24,400; failure to hold this breakout could trigger a pullback toward 23,740, which now acts as support.
Japan Consumer Sector
- Positive outlook: sector represents 17.3% of MSCI Japan Index.
- EPS growth forecast: +25.7% in 2026 after -11.6% decline in 2025.
- Q3 results beat expectations; November sales improved; valuations rising.
- Government stimulus package (€117B) to support domestic demand in retail and electronics.
- Forward P/E: 14.6 for next 12 months.
- Risks: geopolitics and yen volatility remain.
Labor Market
- November data weak:
- ADP reported 32,000 private job losses vs. expected +10,000.
- Employment subindexes for Manufacturing and Services PMIs remain in contraction (10 and 8 months respectively).
- Official November jobs report delayed until after Fed decision.
Economic Activity
- ISM Manufacturing PMI: 48.2 in November → ninth month of contraction.
- Industrial production flat in September: autos -2.2%, aerospace +1.4%, metals +1.4%.
- ISM Services PMI rose to nine-month high → services-led economy persists.
Commodities
- Crude: eased after mild rebound; WTI capped near $60/bbl.
- Gold: dipped below $4,200/oz ahead of PCE data.
- Copper: LME 3-month futures hit fresh record highs.
take care,
Philip Papageorgiou – Market Analyst
X ex Twitter: PhilipForexCom


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

Australian Dollar Forecast: AUD/USD Four-Week Slide Nears Critical Uptrend Support 9 29 2026
Aussie momentum has deteriorated sharply into quarter-end, with inflation, Core PCE and NFP on tap as AUD/USD closes in on a pivotal technical threshold.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.