


Stocks Rally After the Rate Hike but is a Lagging Nasdaq Saying Something?
The response to the rate hike was a strong Thursday outing but ever since Kevin Warsh took over atop the Fed there’s been a shift in equity markets.
Share this:
S&P 500, Nasdaq Talking Points:
- At this point stocks are still in a bullish state, and that can remain the case into Q4 as we head into mid-term elections. But the leader has become a laggard and that has to be taken into account as a higher rate regime can drive a shift in US equities.
- Perhaps more disconcerting is the deduction that companies like NVDA haven’t set all-time-highs in months despite stellar earnings and guidance.
- If US Treasury rates do continue higher, this could, eventually, spell opportunity cost and drive capital away from stocks and into bonds, something that hasn’t really been the case since the lead-in to the financial collapse back in 2006 and 2007.
This content was created by an affiliate of FOREX.com and represents the views and opinions of the author/speakers, not the views and opinions of Forex.com, StoneX Group Inc., or its subsidiaries. The content has not been independently reviewed by FOREX.com.
Forecasting bullish equities has seemingly been a pretty simple call for much of the past 15 years. Sure, there have been a few periods of retracement but, by and large, ever since the Fed figured out they could build a balance sheet and suppress bond yields, thereby driving capital into riskier asset classes such as stocks, bulls have enjoyed one of the brightest backdrops that they’ve ever had in long equities.
Along the way ‘the wealth effect’ seemed to be embraced by the Fed, which states that stronger equity markets drive higher levels of consumer spending, thereby putting the wind to the sails of the central bank’s actions, which makes sense.
This is one of the reasons for the outperformance in technology stocks, as an abundance of capital has pushed into research and development, driving valuations ever-higher; and if there’s little opportunity cost for investors and markets keep humming along, there’s little cause for concern.
More recently, however, a shift has shown, and that’s perhaps ironically taken place as President Trump’s hand-picked successor at the Fed has taken over in a manner much more hawkish than what many were expecting. Warsh has talked a tough game on inflation, and last week he showed up with a rate hike in his first move atop the bank. He also highlighted another move on the horizon, despite his apparent discomfort with forecasts. And while stocks initially sold off, very similar to the July meeting, support soon showed and buyers took over in a big way on the Thursday after the rate decision.
As I looked at coming into this week, there remains a bullish backdrop in the S&P 500 as there’s both a bull flag and a support hit at the 50% mark of the recent major move, the rally that pushed after the July rate decision.
S&P 500 Futures – Daily Chart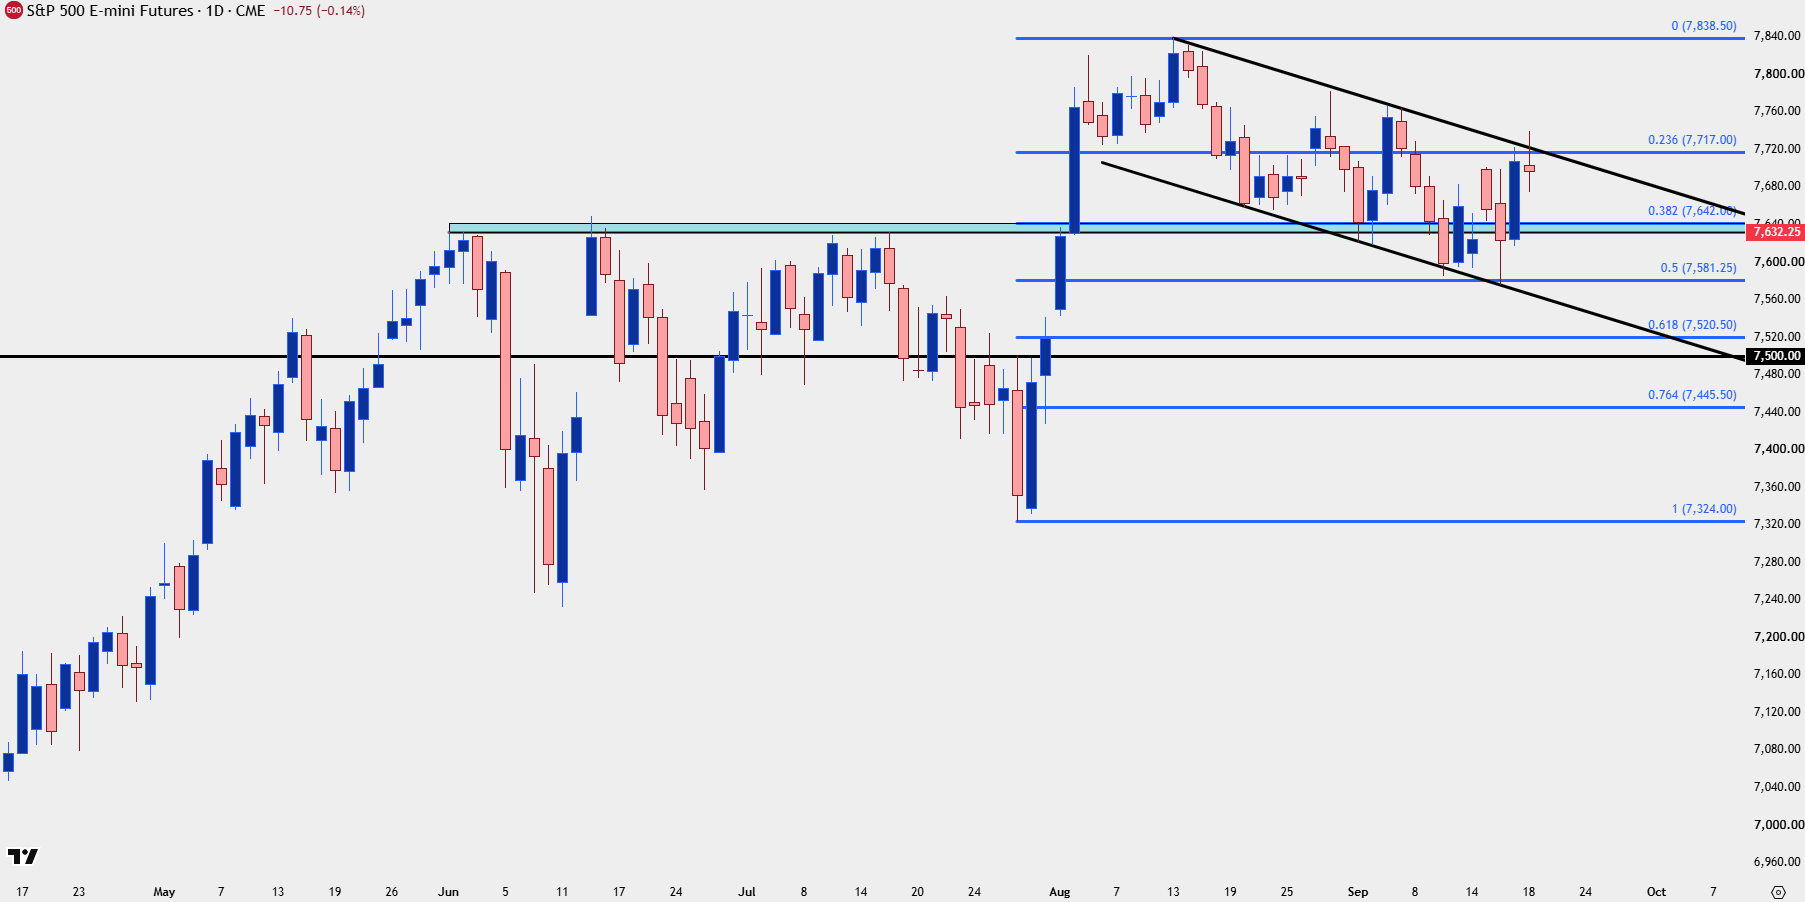
Chart prepared by James Stanley; data derived from Tradingview
Nasdaq
That bullish enthusiasm hasn’t shown to the same degree everywhere. And since the day before Kevin Warsh’s first rate decision at the Fed, the Nasdaq 100 has not set a fresh ATH. The series of lower-highs has remained at a descending trendline, and, to be completely balanced, this can be argued as an inverse head and shoulders formation which can have bullish potential – provided that the neckline, in this case the trendline, gets broken with an upward push. So, bulls still have hope here – but the fact that they haven’t pushed up to fresh highs even as the S&P 500 has, is something that traders should take note of. Because when the leaders become the laggard, there’s often a shift under the surface that can turn into something larger.
There was a similar case back in the year 2000.
Nasdaq 100 Daily Chart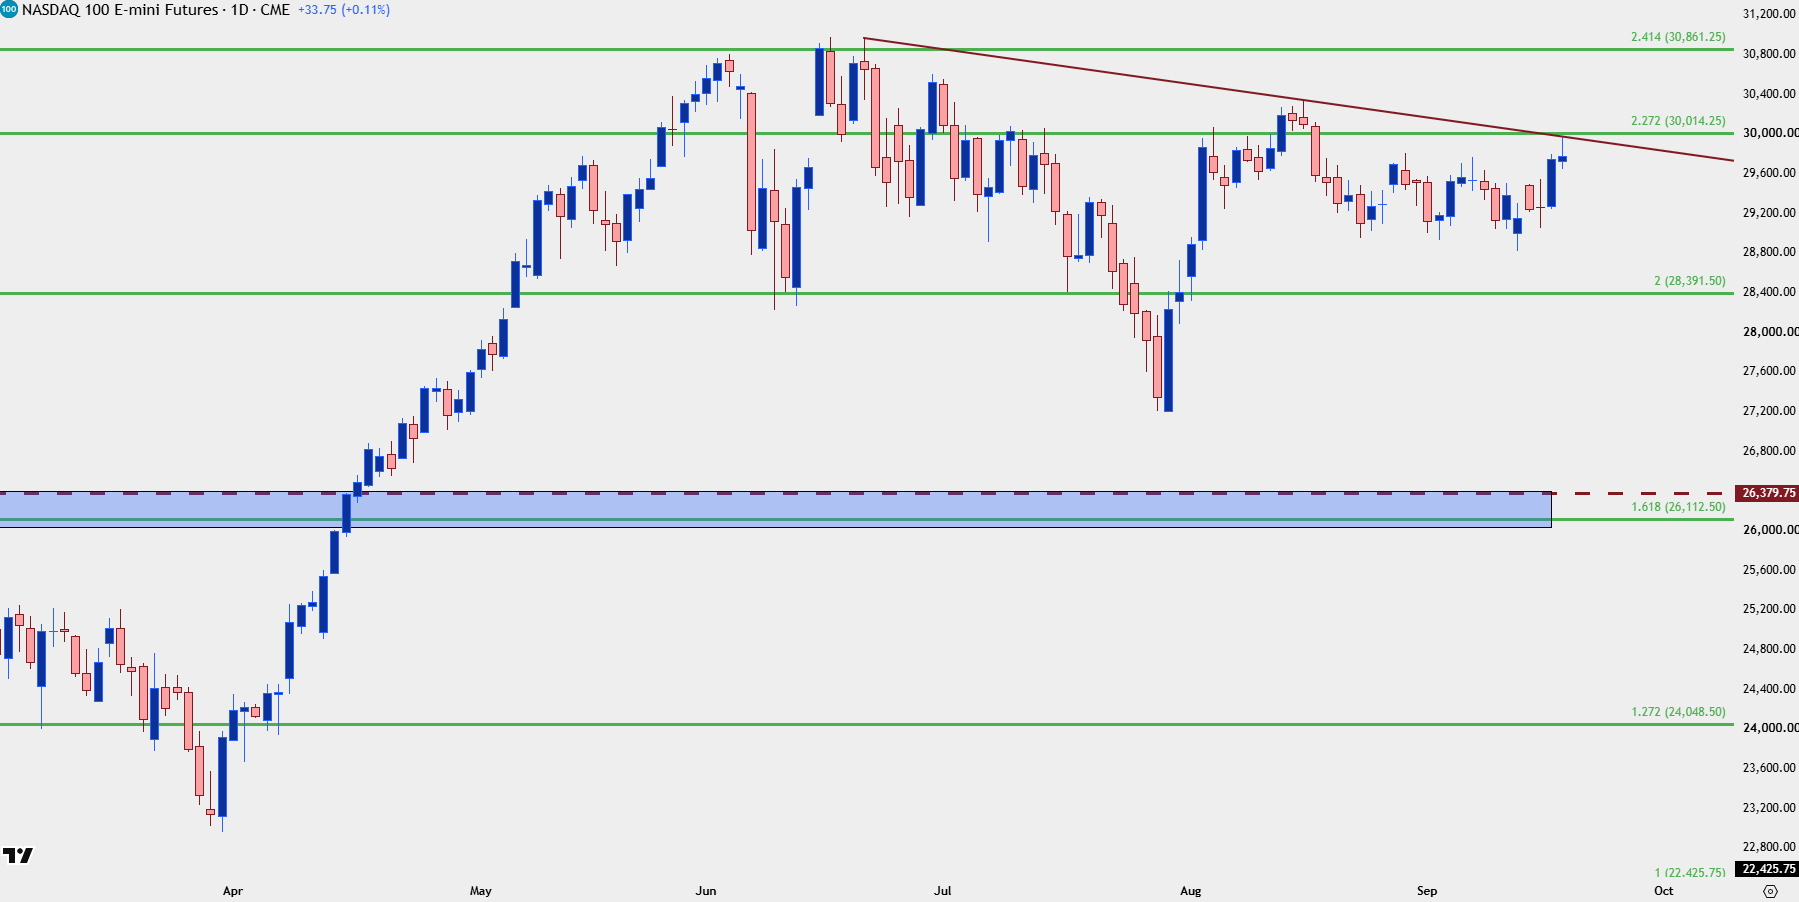
Chart prepared by James Stanley; data derived from Tradingview
A Look Back
Back in the year 2000 there was a similar theme in technology stocks, only instead of AI changing the world, it was the internet and dot coms. There’s several parallels here and I started looking into that beginning with the 2025 forecast on equity indices. I was looking for continued strength in stocks because as I said at the time coming into last year, timing a bubble popping is a perilous quest, and with a Fed set to remain accommodative there wasn’t really a push point to prod the pin to pop any bubble.
But that may be starting to shift. And a look at how this went down back in the year 2000 is informative as the Fed hiked rates by 25 bps in February, and stocks powered higher. They hiked again in March, and that set off a massive sell-off in the Nasdaq that saw the index lose as much as 41% over the next two months.
A 50 bp hike from the Fed actually helped to set a low in May of that year, which was followed by a 44% rally, as recovery took over. But that’s when the big ‘boom’ set forth as the Nasdaq then lost 81% over the next two years.
It was like a slow-motion trainwreck in hindsight, but living through it, there was mania on both sides particularly the rally after the 50 bp hike in May. But – what makes this matter today is how the S&P fared on a comparable basis where bulls were still bristling towards highs in September before the major leg of weakness started to show.
Nasdaq 100 Sept 1999-2002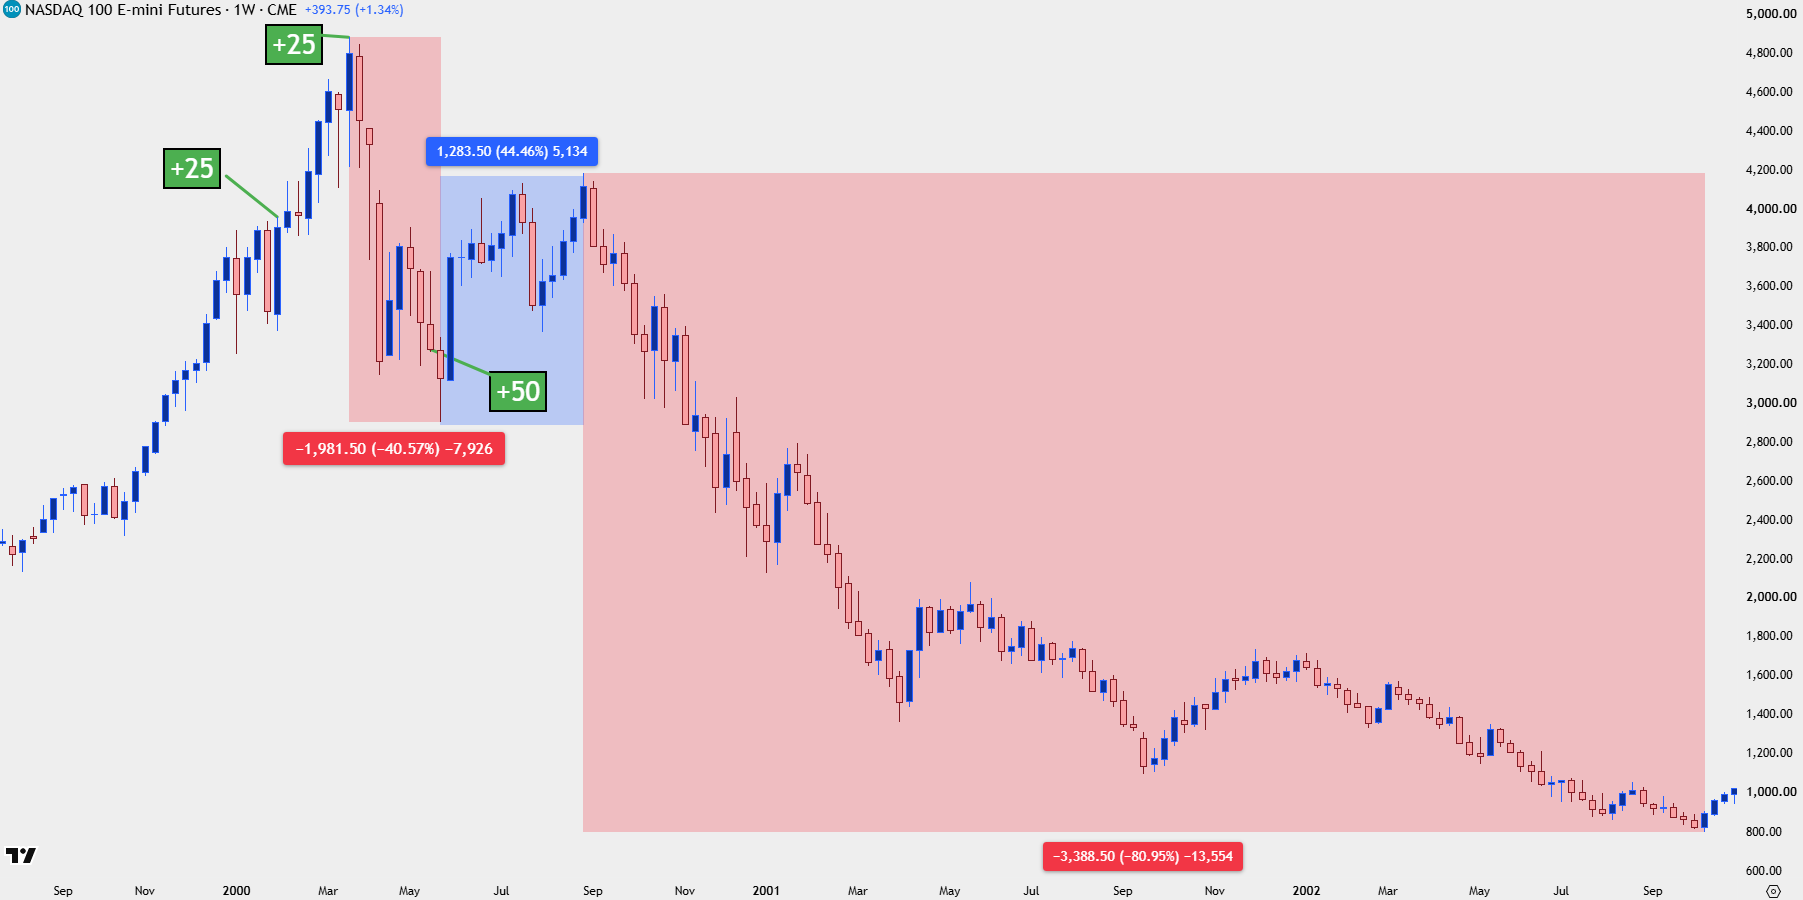
Chart prepared by James Stanley; data derived from Tradingview
Stocks and Opportunity Cost

When the financial collapse hit there was such high desperation that both the Fed and Treasury kept throwing measures at the wall just hoping to get something to stick. This is one reason why we have such dedication to forward guidance, as that was a key ingredient that finally helped bulls to take over larger recoveries in 2011.
But if you think about it forward guidance makes zero sense in a rising rate environment. Sure, if rates will stay low for a long time the central bank telling markets that rates will stay low for a long time compels investors to take on more risk. It also helps investors that are holding bonds to keep holding them, as they have little fear that the bottom will fall out and that prices will fall and yields will soar.
But if rates are going up – what is the point in scaring market participants out of holding bonds? You’re practically saying to investors that if you’re holding longer-term paper, well, get ready for a loss, because higher rates mean lower prices. But because the Fed had incorporated this as a part of their communication strategy and because it hadn’t yet blown up in their face, they just kept doing it.
And this is the kind of change that Kevin Warsh seems to want to represent.
But, with that said, it was another change around the financial collapse that has dominated and driven markets in a way that sets forth moral hazard, and that’s the prospect of the central bank buying and holding bonds. This is, in essence, subsidization of government debt, and it removes the market mechanism that punishes a government for spending too much. This artificial suppression of US government yields, both in Treasuries and mortgage backed securities, has created a monstrous problem as any effort towards ‘normalization’ has been attempted.
There’s also the risk side of that coin, as suppressed yields have driven more and more capital into stocks, riskier stocks, and this, like we saw going into the year 2000, has created outlandish valuations that are historically difficult to justify.
As yields go higher, many investors, for the first time in their careers, will have an actual opportunity cost: Should they bid the 7th or 8th pullback in AI tech stocks that are still at stretched valuations? Or, should they just lock up a 5% or 5.25% 10-year yield while getting some upside potential in the event that yields ultimately fall?
And on that, it’s difficult to imagine that yields remain at this high level for too long as a heavily indebted US government simply can’t afford it. They either have to force massive tax hikes to finance increasingly large deficits, or they have to spend considerably less, and more likely, with debt-to-GDP where it’s at, force a combination of the two.
But good luck getting elected on that platform of austerity where the pledge is ‘we will tax you more and give you less!’
That just feels incredibly unlikely.
What does seem more probabilistic is an eventual return to central bank bond buying but for that to even be an option, inflation first has to be tamed and that seems to be the primary prerogative of Kevin Warsh now.
At this point, the lifeblood of markets is US government debt and while we haven’t seen a massive move in equities yet, these are the types of things that take time, and from the 10-year yield chart below, this is not something I would want to be short of, at the moment, as yields look ready to break out in a very big way.
US 10-Year Note Treasury Yields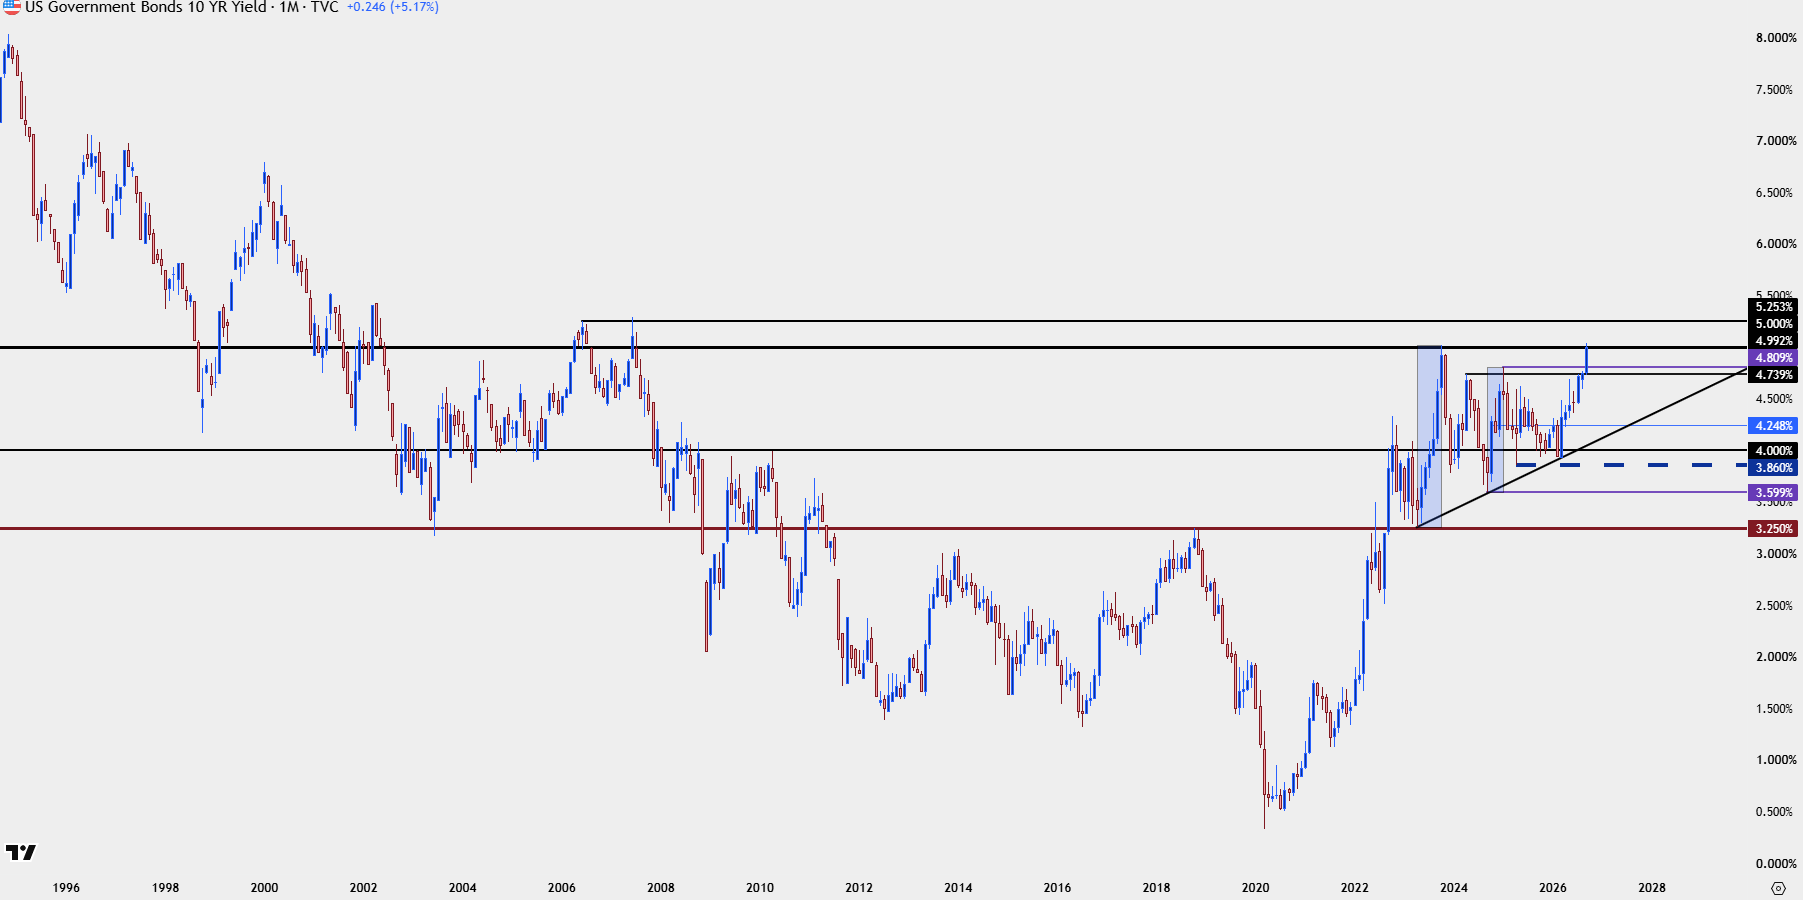
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nvidia Holds Support Ahead of Earnings as Nasdaq 100 Rebounds
Nvidia shares approach major support as selling pressure eases, while the Nasdaq 100 rebounds. Could upcoming earnings fuel a broader recovery?
Nasdaq 100 Outlook: Slingshot rally or false dawn?
Nasdaq 100 futures are threatening to reclaim the 200-day moving average following their largest initial breakdown in more than 26 years. History suggests getting back above it is one thing, staying there another.

US Dollar Price Action Setups: USD/JPY, USD/CAD, EUR/USD, GBP/USD
The US Dollar has an open door for a breakout test but whether that theme pushes through likely revolves back to the USD/JPY breakout setup, even with EUR/USD set up for a breakdown.
The information on this web site is not targeted at the general public of any particular country. It is not intended for distribution to residents in any country where such distribution or use would contravene any local law or regulatory requirement. The information and opinions in this report are for general information use only and are not intended as an offer or solicitation with respect to the purchase or sale of any currency or CFD contract. All opinions and information contained in this report are subject to change without notice. This report has been prepared without regard to the specific investment objectives, financial situation and needs of any particular recipient. Any references to historical price movements or levels is informational based on our analysis and we do not represent or warranty that any such movements or levels are likely to reoccur in the future. While the information contained herein was obtained from sources believed to be reliable, author does not guarantee its accuracy or completeness, nor does author assume any liability for any direct, indirect or consequential loss that may result from the reliance by any person upon any such information or opinions.
Futures, Options on Futures, Foreign Exchange and other leveraged products involves significant risk of loss and is not suitable for all investors. Losses can exceed your deposits. Increasing leverage increases risk. Spot Gold and Silver contracts are not subject to regulation under the U.S. Commodity Exchange Act. Contracts for Difference (CFDs) are not available for US residents. Before deciding to trade forex, commodity futures, or digital assets, you should carefully consider your financial objectives, level of experience and risk appetite. Any opinions, news, research, analyses, prices or other information contained herein is intended as general information about the subject matter covered and is provided with the understanding that we do not provide any investment, legal, or tax advice. You should consult with appropriate counsel or other advisors on all investment, legal, or tax matters. References to FOREX.com or GAIN Capital refer to StoneX Group Inc. and its subsidiaries. Please read Characteristics and Risks of Standardized Options.