




030920 US Pre Open
US futures dip a bit after S&P500 and Nasdaq posted new records yesterday.
Share this:

US Futures are consolidating after Nasdaq 100 advanced for a fourth straight session yesterday, and S&P 500 jumped 1.5%, both hitting fresh records.
Later today, investors will focus on the Institute for Supply Management's Services PMI for August (57.0 expected) and initial jobless claims for the week ending August 29 (0.95 million expected). The Commerce Department will report July trade balance (58 billion dollars deficit expected). Research firm Markit will publish final readings of August Services PMI, expected at 54.7. In Canada, July Balance of Trades will be expected at CAD 2.5 billion deficit.
European indices remain strongly bullish. Research firm Markit has published final readings of August Services PMI for the eurozone at 50.5 (vs 50.1 expected), for Germany at 52.5 (vs 50.8 expected), for France at 51.5 (vs 51.9 expected) and for the U.K. at (vs 60.1 expected). The European Commission has reported July retail sales at -1.3% (vs +1.0% on month expected).
Asian indices closed mixed as Australian ASX and Japanese Nikkei were up when Hong Kong HSI and Chines CSI closed in the red. Data released this morning showed that China's Caixin Services PMI slipped to 54.0 in August (53.9 expected) from 54.1 in July.
WTI Crude Oil futures are on the downside, pressured by the rebound in the U.S. dollar. Meanwhile, the U.S. Energy Information Administration (EIA) reported that crude oil inventories dropped 9.36M barrels in the week ending August 28 (-2.14 million barrels expected). Besides, the U.S. crude oil production dropped to 9.7 million barrels per day from 10.8 million barrels per day. Iraq may seek a two month extension to implement the extra production cuts for OPEC+ deal, reported Bloomberg.
Gold is still consolidating while the US dollar tries to pursue its rebound on economic recovery optimism.
Gold fell 12.89 dollars (-0.66%) to 1930.03 dollars while the dollar index rose 0.15pt to 93.
US Equity Snapshot
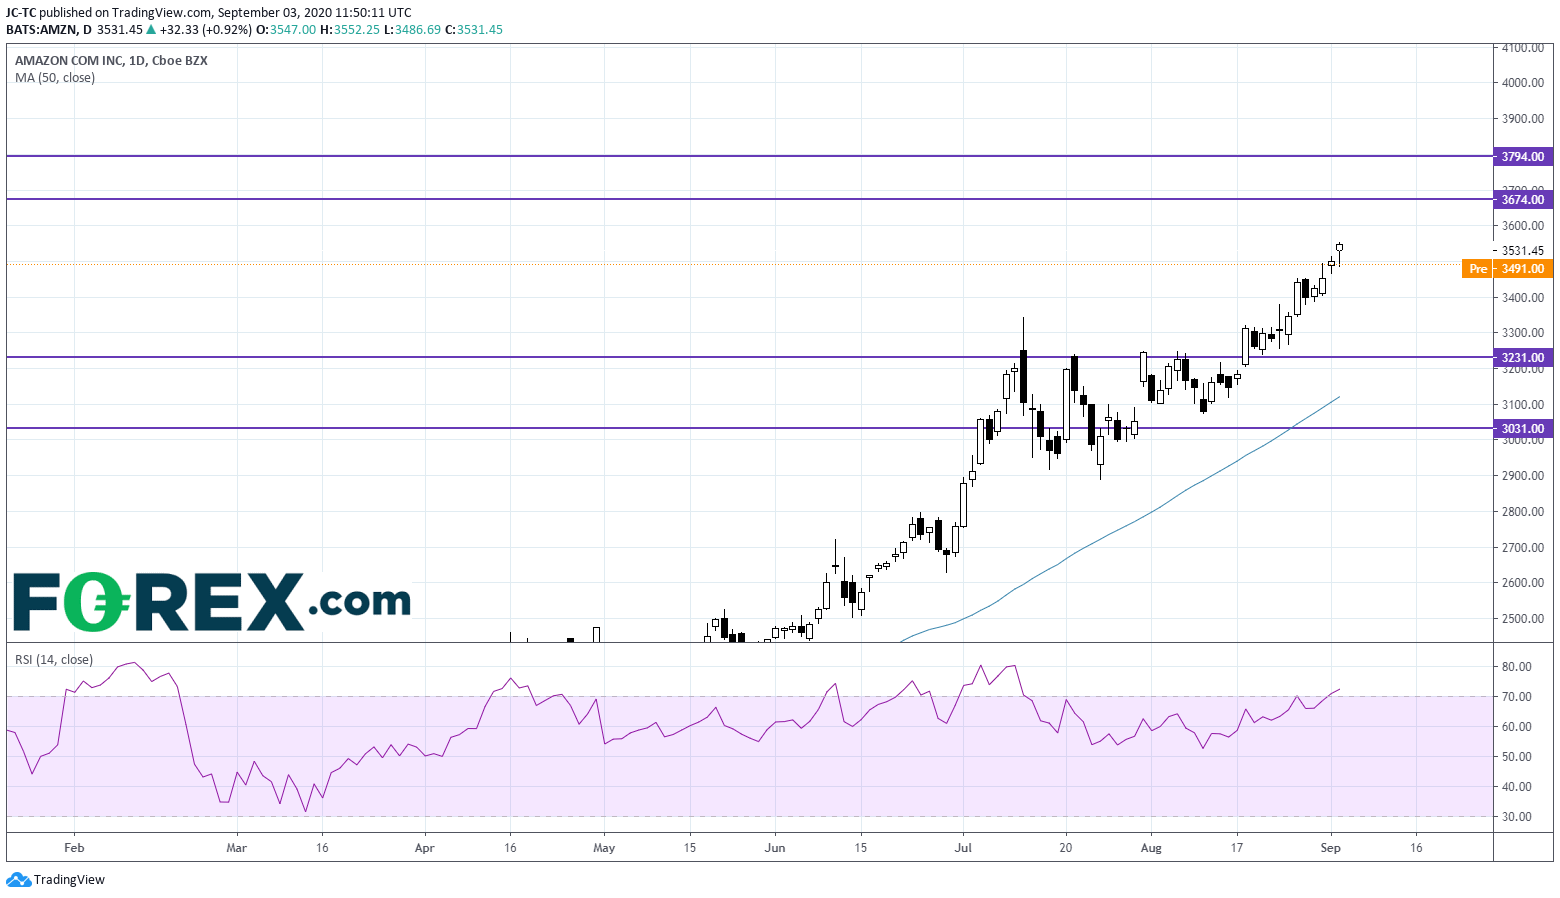
Amazon.com (AMZN), the e-commerce giant, plans to create 10 000 jobs in UK this year.
Source : TradingVIEW, Gain Capital
Campbell Soup (CPB), a manufacturer of branded food products, posted fourth quarter adjusted and current quarter adjusted EPS forecast that both beat estimates.
JPMorgan (JPM) and Bank of America (BAC), the banking groups, were both upgraded to "buy" from "hold" at Deutsche Bank.
Fedex (FDX), the package delivery service company, was upgraded to "buy" from "hold" at Berenberg. On the other hand, rival UPS (UPS) was downgraded to "sell" from "hold", still at Berenberg.
Eli Lilly (LLY), a developer and producer of pharmaceuticals, was upgraded to "overweight" from "equalweight" at Morgan Stanley.
PVH (PVH), a designer and global marketer of branded apparel, released second quarter adjusted EPS of 0.13 dollar, above forecasts, down from an EPS of 2.10 dollars a year ago, on revenue of 1.6 billion dollars, better than anticipated, down from 2.4 billion dollars a year earlier.
US Futures are consolidating after Nasdaq 100 advanced for a fourth straight session yesterday, and S&P 500 jumped 1.5%, both hitting fresh records.
Later today, investors will focus on the Institute for Supply Management's Services PMI for August (57.0 expected) and initial jobless claims for the week ending August 29 (0.95 million expected). The Commerce Department will report July trade balance (58 billion dollars deficit expected). Research firm Markit will publish final readings of August Services PMI, expected at 54.7. In Canada, July Balance of Trades will be expected at CAD 2.5 billion deficit.
European indices remain strongly bullish. Research firm Markit has published final readings of August Services PMI for the eurozone at 50.5 (vs 50.1 expected), for Germany at 52.5 (vs 50.8 expected), for France at 51.5 (vs 51.9 expected) and for the U.K. at (vs 60.1 expected). The European Commission has reported July retail sales at -1.3% (vs +1.0% on month expected).
Asian indices closed mixed as Australian ASX and Japanese Nikkei were up when Hong Kong HSI and Chines CSI closed in the red. Data released this morning showed that China's Caixin Services PMI slipped to 54.0 in August (53.9 expected) from 54.1 in July.
WTI Crude Oil futures are on the downside, pressured by the rebound in the U.S. dollar. Meanwhile, the U.S. Energy Information Administration (EIA) reported that crude oil inventories dropped 9.36M barrels in the week ending August 28 (-2.14 million barrels expected). Besides, the U.S. crude oil production dropped to 9.7 million barrels per day from 10.8 million barrels per day. Iraq may seek a two month extension to implement the extra production cuts for OPEC+ deal, reported Bloomberg.
Gold is still consolidating while the US dollar tries to pursue its rebound on economic recovery optimism.
Gold fell 12.89 dollars (-0.66%) to 1930.03 dollars while the dollar index rose 0.15pt to 93.
US Equity Snapshot
Amazon.com (AMZN), the e-commerce giant, plans to create 10 000 jobs in UK this year.
Source : TradingVIEW, Gain Capital
Campbell Soup (CPB), a manufacturer of branded food products, posted fourth quarter adjusted and current quarter adjusted EPS forecast that both beat estimates.
JPMorgan (JPM) and Bank of America (BAC), the banking groups, were both upgraded to "buy" from "hold" at Deutsche Bank.
Fedex (FDX), the package delivery service company, was upgraded to "buy" from "hold" at Berenberg. On the other hand, rival UPS (UPS) was downgraded to "sell" from "hold", still at Berenberg.
Eli Lilly (LLY), a developer and producer of pharmaceuticals, was upgraded to "overweight" from "equalweight" at Morgan Stanley.
PVH (PVH), a designer and global marketer of branded apparel, released second quarter adjusted EPS of 0.13 dollar, above forecasts, down from an EPS of 2.10 dollars a year ago, on revenue of 1.6 billion dollars, better than anticipated, down from 2.4 billion dollars a year earlier.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500, Nasdaq, Dow Forecast: Rising Yields Test Rally Ahead of Nvidia, Fed 8 22 2026
S&P 500, Nasdaq and Dow test key technical levels as momentum fades, raising the risk of a deeper correction heading into a pivotal week.

Magnificent Seven Earnings Preview: Can Big Tech Reclaim AI Leadership?
The Magnificent Seven enter earnings with far more divided performance than in previous years, as investors increasingly distinguish between companies supplying the AI buildout and those funding it - what does that mean heading into earnings season?

USD/JPY unwind accelerates as GPIF headlines spark yen buying
Japanese assets are rallying after the government floated the prospect of the GPIF investing more heavily at home. While the proposal could have significant implications for global capital flows, it does not yet change the broader forces driving Japanese bond yields and USD/JPY.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.