



29 07 US PRE OPEN
The S&P 500 Futures are slightly rebounding after they ended in the red yesterday
Share this:

The S&P 500 Futures are slightly rebounding after they ended in the red yesterday. Market sentiment was dampened by ongoing political negotiations concerning a new $1 trillion coronavirus stimulus bill proposed by Senate Republicans. And investors exercised caution following mixed quarterly results from large firms.
Later today, reports on Wholesale Inventories (June preliminary reading -0.5% on month expected) and Pending Homes Sales (June annualized rate +15.0% on month expected) will be released. The Federal Reserve is expected to keep its benchmark interest rates unchanged at 0.00%-0.25%.
European indices try to remain positive. In Germany, June Import prices were released at +0.6% vs +0.3% in May. They were expected at +0.5%. The Bank of England has reported the number of Mortgage Approvals for June at 40,000 (vs 35,000 expected). France's National Statistics Office has released July Consumer Confidence Indicator at 94 (vs 99 expected, 97 in June).
Asian indices closed in dispersed order. Hong Kong HSI and Chinese CSI closed in the green when Japanese Nikkei and Australian ASX closed on the downside.
WTI Crude Oil futures are on the upside. The American Petroleum Institute (API) reported that U.S. crude stockpiles dropped 7M bbl for the week ended July 24. Later today, the Energy Information Administration (EIA) will release official crude oil inventories data for the same week (+4.892M bbl expected).
Gold remains firm near fresh all-time highs on virus fears and hopes of stimulus while the US dollar consolidates close to a two-year low before Fed.
Gold fell 2.88 dollars (-0.15%) to 1955.55 dollars. The dollar index declined 0.15pt to 93.543.
U.S. Equity Snapshot
Starbucks (SBUX), the global specialty coffee chain, disclosed third quarter adjusted LPS of 0.46 dollar, narrower than estimated, vs an EPS of 0.78 dollar a year ago, on net revenue of 4.2 billion dollars, just ahead of forecasts, down from 6.8 billion dollars a year earlier. The Co also reported that same-store sales declined 40.0%, slightly better than anticipated.
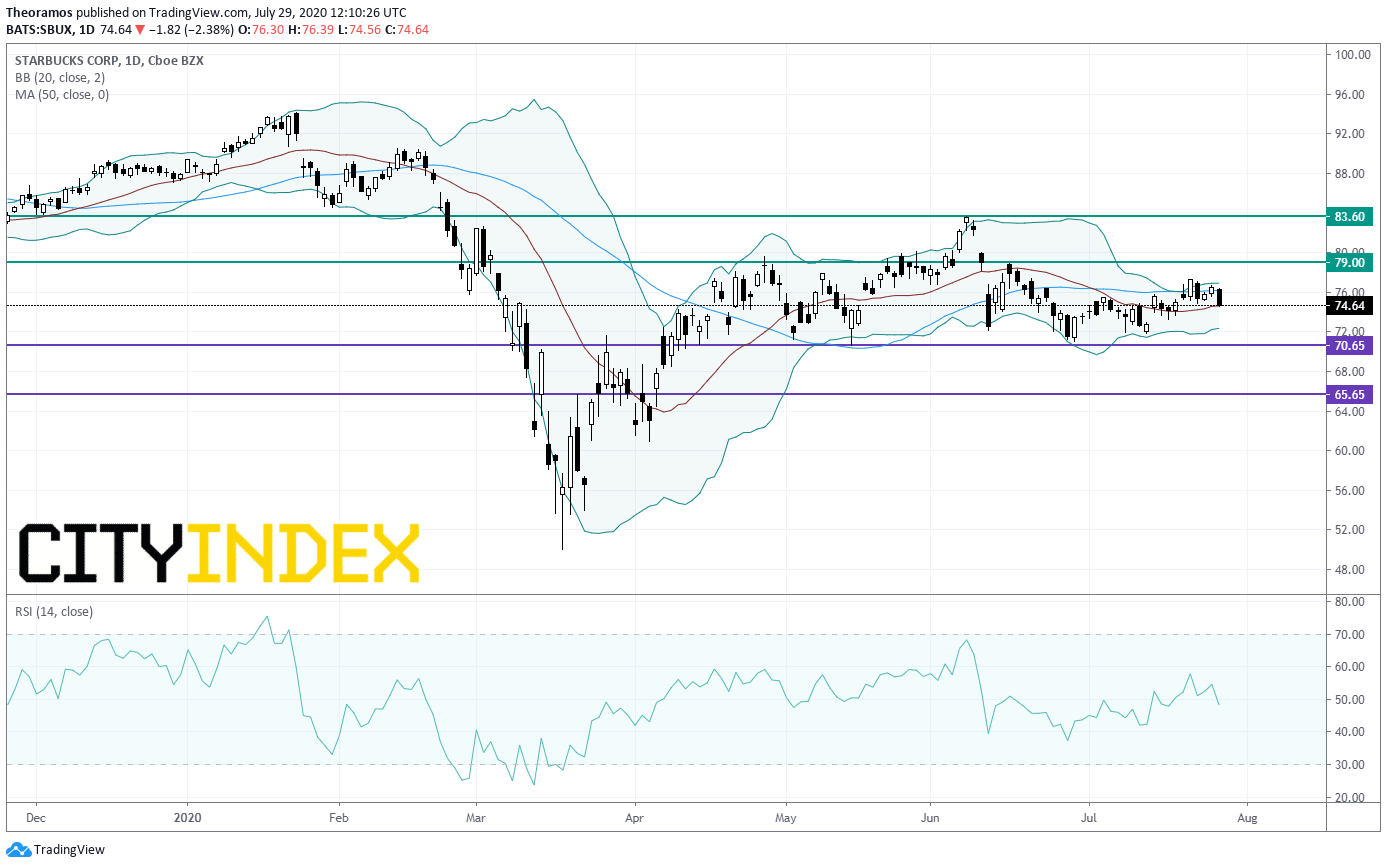
Source: TradingView, Gain Capital
General Motors (GM) is gaining ground before hours after posting quarterly earnings above expectations.
Boeing (BA), the aircraft maker, is edging higher before hours as quarterly free cash flow was less negative than forecast.
General Electric (GE), the industrial conglomerate, is gaining some ground before hours after posting quarterly sales and free cash flow that beat estimates.
Advanced Micro Devices (AMD), a designer and producer of microprocessors, announced second quarter adjusted EPS of 0.18 dollar, above estimates, up from 0.08 dollar a year ago on revenue of 1.9 billion dollars, as expected, up from 1.5 billion dollars a year earlier.
Visa (V), the credit card company, revealed third quarter adjusted EPS of 1.06 dollar, just beating estimates, down from 1.37 dollar a year ago on revenue of 4.8 billion dollars, in line with forecasts, down from 5.8 billion dollars a year earlier.
Spotify (SPOT), the music streaming specialist, is losing some ground before hours after reporting a wider than expected quarterly loss and sales that missed estimates.
Amgen (AMGN), a developer of biotechnology medicines, posted second quarter adjusted EPS of 4.25 dollars, beating estimates, up from 3.97 dollars a year ago, on revenue of 6.2 billion dollars, in line with the consensus, up from 5.9 billion dollars a year earlier.
eBay (EBAY), the global electronic commerce platform, released second quarter adjusted EPS of 1.08 dollar, slightly above forecasts, up from 0.66 dollar a year ago, on net revenue of 2.9 billion dollars, exceeding the consensus, up from 2.4 billion dollars a year earlier.
Later today, reports on Wholesale Inventories (June preliminary reading -0.5% on month expected) and Pending Homes Sales (June annualized rate +15.0% on month expected) will be released. The Federal Reserve is expected to keep its benchmark interest rates unchanged at 0.00%-0.25%.
European indices try to remain positive. In Germany, June Import prices were released at +0.6% vs +0.3% in May. They were expected at +0.5%. The Bank of England has reported the number of Mortgage Approvals for June at 40,000 (vs 35,000 expected). France's National Statistics Office has released July Consumer Confidence Indicator at 94 (vs 99 expected, 97 in June).
Asian indices closed in dispersed order. Hong Kong HSI and Chinese CSI closed in the green when Japanese Nikkei and Australian ASX closed on the downside.
WTI Crude Oil futures are on the upside. The American Petroleum Institute (API) reported that U.S. crude stockpiles dropped 7M bbl for the week ended July 24. Later today, the Energy Information Administration (EIA) will release official crude oil inventories data for the same week (+4.892M bbl expected).
Gold remains firm near fresh all-time highs on virus fears and hopes of stimulus while the US dollar consolidates close to a two-year low before Fed.
Gold fell 2.88 dollars (-0.15%) to 1955.55 dollars. The dollar index declined 0.15pt to 93.543.
U.S. Equity Snapshot
Starbucks (SBUX), the global specialty coffee chain, disclosed third quarter adjusted LPS of 0.46 dollar, narrower than estimated, vs an EPS of 0.78 dollar a year ago, on net revenue of 4.2 billion dollars, just ahead of forecasts, down from 6.8 billion dollars a year earlier. The Co also reported that same-store sales declined 40.0%, slightly better than anticipated.
Source: TradingView, Gain Capital
General Motors (GM) is gaining ground before hours after posting quarterly earnings above expectations.
Boeing (BA), the aircraft maker, is edging higher before hours as quarterly free cash flow was less negative than forecast.
General Electric (GE), the industrial conglomerate, is gaining some ground before hours after posting quarterly sales and free cash flow that beat estimates.
Advanced Micro Devices (AMD), a designer and producer of microprocessors, announced second quarter adjusted EPS of 0.18 dollar, above estimates, up from 0.08 dollar a year ago on revenue of 1.9 billion dollars, as expected, up from 1.5 billion dollars a year earlier.
Visa (V), the credit card company, revealed third quarter adjusted EPS of 1.06 dollar, just beating estimates, down from 1.37 dollar a year ago on revenue of 4.8 billion dollars, in line with forecasts, down from 5.8 billion dollars a year earlier.
Spotify (SPOT), the music streaming specialist, is losing some ground before hours after reporting a wider than expected quarterly loss and sales that missed estimates.
Amgen (AMGN), a developer of biotechnology medicines, posted second quarter adjusted EPS of 4.25 dollars, beating estimates, up from 3.97 dollars a year ago, on revenue of 6.2 billion dollars, in line with the consensus, up from 5.9 billion dollars a year earlier.
eBay (EBAY), the global electronic commerce platform, released second quarter adjusted EPS of 1.08 dollar, slightly above forecasts, up from 0.66 dollar a year ago, on net revenue of 2.9 billion dollars, exceeding the consensus, up from 2.4 billion dollars a year earlier.
The S&P 500 Futures are slightly rebounding after they ended in the red yesterday. Market sentiment was dampened by ongoing political negotiations concerning a new $1 trillion coronavirus stimulus bill proposed by Senate Republicans. And investors exercised caution following mixed quarterly results from large firms.
Later today, reports on Wholesale Inventories (June preliminary reading -0.5% on month expected) and Pending Homes Sales (June annualized rate +15.0% on month expected) will be released. The Federal Reserve is expected to keep its benchmark interest rates unchanged at 0.00%-0.25%.
European indices try to remain positive. In Germany, June Import prices were released at +0.6% vs +0.3% in May. They were expected at +0.5%. The Bank of England has reported the number of Mortgage Approvals for June at 40,000 (vs 35,000 expected). France's National Statistics Office has released July Consumer Confidence Indicator at 94 (vs 99 expected, 97 in June).
Asian indices closed in dispersed order. Hong Kong HSI and Chinese CSI closed in the green when Japanese Nikkei and Australian ASX closed on the downside.
WTI Crude Oil futures are on the upside. The American Petroleum Institute (API) reported that U.S. crude stockpiles dropped 7M bbl for the week ended July 24. Later today, the Energy Information Administration (EIA) will release official crude oil inventories data for the same week (+4.892M bbl expected).
Gold remains firm near fresh all-time highs on virus fears and hopes of stimulus while the US dollar consolidates close to a two-year low before Fed.
Gold fell 2.88 dollars (-0.15%) to 1955.55 dollars. The dollar index declined 0.15pt to 93.543.
U.S. Equity Snapshot
Starbucks (SBUX), the global specialty coffee chain, disclosed third quarter adjusted LPS of 0.46 dollar, narrower than estimated, vs an EPS of 0.78 dollar a year ago, on net revenue of 4.2 billion dollars, just ahead of forecasts, down from 6.8 billion dollars a year earlier. The Co also reported that same-store sales declined 40.0%, slightly better than anticipated.
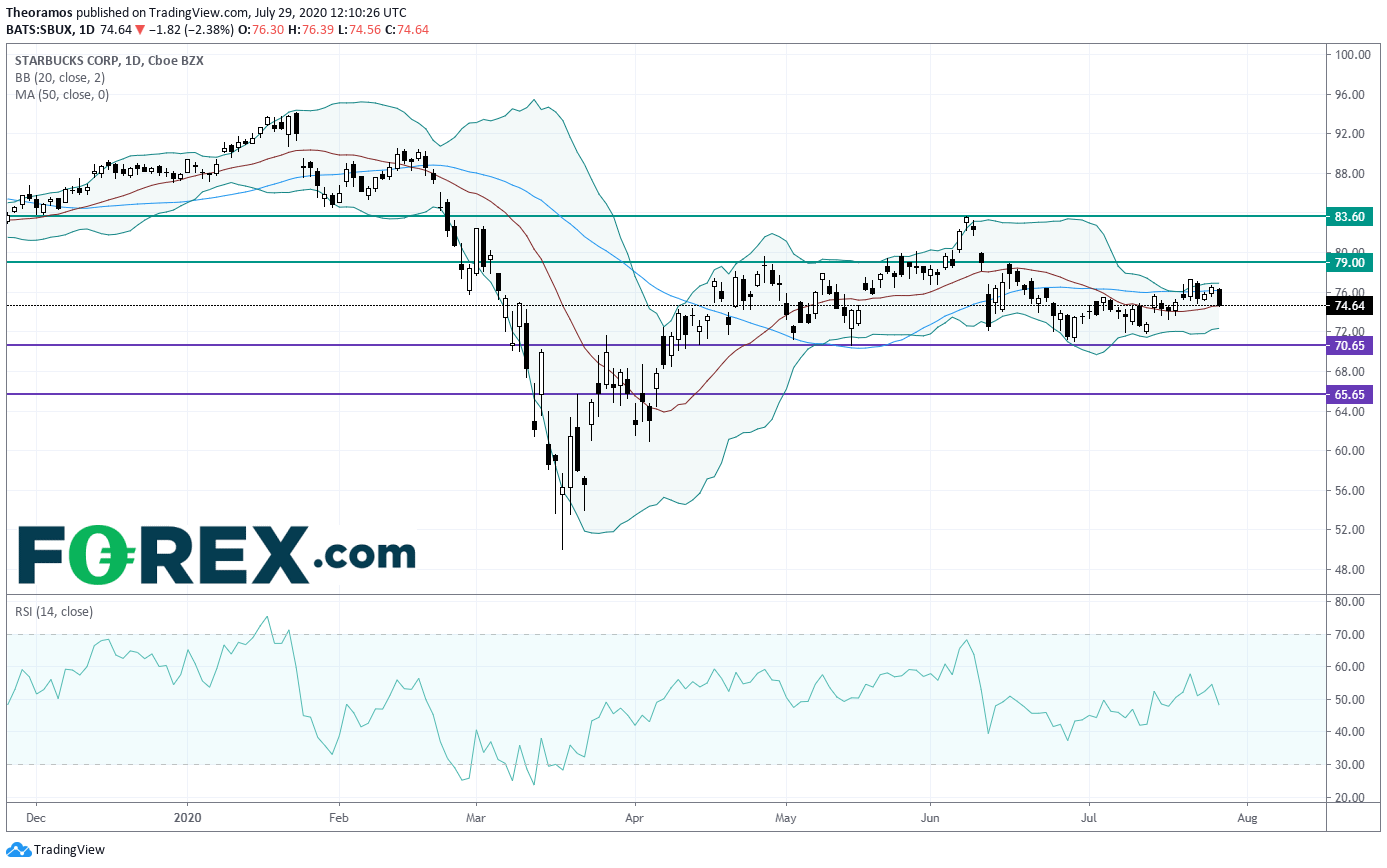
Source: TradingView, Gain Capital
General Motors (GM) is gaining ground before hours after posting quarterly earnings above expectations.
Boeing (BA), the aircraft maker, is edging higher before hours as quarterly free cash flow was less negative than forecast.
General Electric (GE), the industrial conglomerate, is gaining some ground before hours after posting quarterly sales and free cash flow that beat estimates.
Advanced Micro Devices (AMD), a designer and producer of microprocessors, announced second quarter adjusted EPS of 0.18 dollar, above estimates, up from 0.08 dollar a year ago on revenue of 1.9 billion dollars, as expected, up from 1.5 billion dollars a year earlier.
Visa (V), the credit card company, revealed third quarter adjusted EPS of 1.06 dollar, just beating estimates, down from 1.37 dollar a year ago on revenue of 4.8 billion dollars, in line with forecasts, down from 5.8 billion dollars a year earlier.
Spotify (SPOT), the music streaming specialist, is losing some ground before hours after reporting a wider than expected quarterly loss and sales that missed estimates.
Amgen (AMGN), a developer of biotechnology medicines, posted second quarter adjusted EPS of 4.25 dollars, beating estimates, up from 3.97 dollars a year ago, on revenue of 6.2 billion dollars, in line with the consensus, up from 5.9 billion dollars a year earlier.
eBay (EBAY), the global electronic commerce platform, released second quarter adjusted EPS of 1.08 dollar, slightly above forecasts, up from 0.66 dollar a year ago, on net revenue of 2.9 billion dollars, exceeding the consensus, up from 2.4 billion dollars a year earlier.
Later today, reports on Wholesale Inventories (June preliminary reading -0.5% on month expected) and Pending Homes Sales (June annualized rate +15.0% on month expected) will be released. The Federal Reserve is expected to keep its benchmark interest rates unchanged at 0.00%-0.25%.
European indices try to remain positive. In Germany, June Import prices were released at +0.6% vs +0.3% in May. They were expected at +0.5%. The Bank of England has reported the number of Mortgage Approvals for June at 40,000 (vs 35,000 expected). France's National Statistics Office has released July Consumer Confidence Indicator at 94 (vs 99 expected, 97 in June).
Asian indices closed in dispersed order. Hong Kong HSI and Chinese CSI closed in the green when Japanese Nikkei and Australian ASX closed on the downside.
WTI Crude Oil futures are on the upside. The American Petroleum Institute (API) reported that U.S. crude stockpiles dropped 7M bbl for the week ended July 24. Later today, the Energy Information Administration (EIA) will release official crude oil inventories data for the same week (+4.892M bbl expected).
Gold remains firm near fresh all-time highs on virus fears and hopes of stimulus while the US dollar consolidates close to a two-year low before Fed.
Gold fell 2.88 dollars (-0.15%) to 1955.55 dollars. The dollar index declined 0.15pt to 93.543.
U.S. Equity Snapshot
Starbucks (SBUX), the global specialty coffee chain, disclosed third quarter adjusted LPS of 0.46 dollar, narrower than estimated, vs an EPS of 0.78 dollar a year ago, on net revenue of 4.2 billion dollars, just ahead of forecasts, down from 6.8 billion dollars a year earlier. The Co also reported that same-store sales declined 40.0%, slightly better than anticipated.
Source: TradingView, Gain Capital
General Motors (GM) is gaining ground before hours after posting quarterly earnings above expectations.
Boeing (BA), the aircraft maker, is edging higher before hours as quarterly free cash flow was less negative than forecast.
General Electric (GE), the industrial conglomerate, is gaining some ground before hours after posting quarterly sales and free cash flow that beat estimates.
Advanced Micro Devices (AMD), a designer and producer of microprocessors, announced second quarter adjusted EPS of 0.18 dollar, above estimates, up from 0.08 dollar a year ago on revenue of 1.9 billion dollars, as expected, up from 1.5 billion dollars a year earlier.
Visa (V), the credit card company, revealed third quarter adjusted EPS of 1.06 dollar, just beating estimates, down from 1.37 dollar a year ago on revenue of 4.8 billion dollars, in line with forecasts, down from 5.8 billion dollars a year earlier.
Spotify (SPOT), the music streaming specialist, is losing some ground before hours after reporting a wider than expected quarterly loss and sales that missed estimates.
Amgen (AMGN), a developer of biotechnology medicines, posted second quarter adjusted EPS of 4.25 dollars, beating estimates, up from 3.97 dollars a year ago, on revenue of 6.2 billion dollars, in line with the consensus, up from 5.9 billion dollars a year earlier.
eBay (EBAY), the global electronic commerce platform, released second quarter adjusted EPS of 1.08 dollar, slightly above forecasts, up from 0.66 dollar a year ago, on net revenue of 2.9 billion dollars, exceeding the consensus, up from 2.4 billion dollars a year earlier.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.