




Apple Earnings Preview
Apple is due to report favourable earnings on 28th January
Share this:
When:
Tuesday 28th January after US close
Tuesday 28th January after US close
Expectations:
Revenue $85.5 billion - $89.5 billion
EPS $4.53
Revenue $85.5 billion - $89.5 billion
EPS $4.53
A lot to live up to
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
Favourable earnings expected
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Key points to watch for on earnings call:
1. 5G – management comments on plan to capitalise on 5G network
2. Emerging services – comments on financial services, how Apple card is performing, and healthcare could be increasingly important drivers in 2020.
3. Non – smart phone products – after strong Christmas sales of Apple watches and Air Pods Pro
Risks Ahead - Upgrade cycle 2020
Recent optimism surrounding Apple is owing to the upgrade cycle that the broader smart phone market is heading into. For the past few years customers have had little reason to upgrade or replace their phones, hanging onto their devices for longer.
1. 5G – management comments on plan to capitalise on 5G network
2. Emerging services – comments on financial services, how Apple card is performing, and healthcare could be increasingly important drivers in 2020.
3. Non – smart phone products – after strong Christmas sales of Apple watches and Air Pods Pro
Risks Ahead - Upgrade cycle 2020
Recent optimism surrounding Apple is owing to the upgrade cycle that the broader smart phone market is heading into. For the past few years customers have had little reason to upgrade or replace their phones, hanging onto their devices for longer.
With the build out of the 5G network, customers will have a reason to upgrade their phones. 5G and China are expected to be big drivers of growth at Apple. US, UK and Korea will also play their part.
It is this upgrade cycle, the wearables business and Apple’s focus on services, which are the main reasons behind analysts lifting Apple’s price target, helping to lift the share price.
There is of course no guarantee that the 5G upgrade cycle will appear. There is always the possibility that investors won’t be wowed by Apple’s 5G iPhone or simply aren’t interested in upgrading to 5G. iPhone shipments actually declined during the move from 3G to 5G.
As demand expectations have helped lift Apple shares to $319.99, should that demand fail to materialise across the coming year, Apple’s share price take a hit.
Chart thoughts
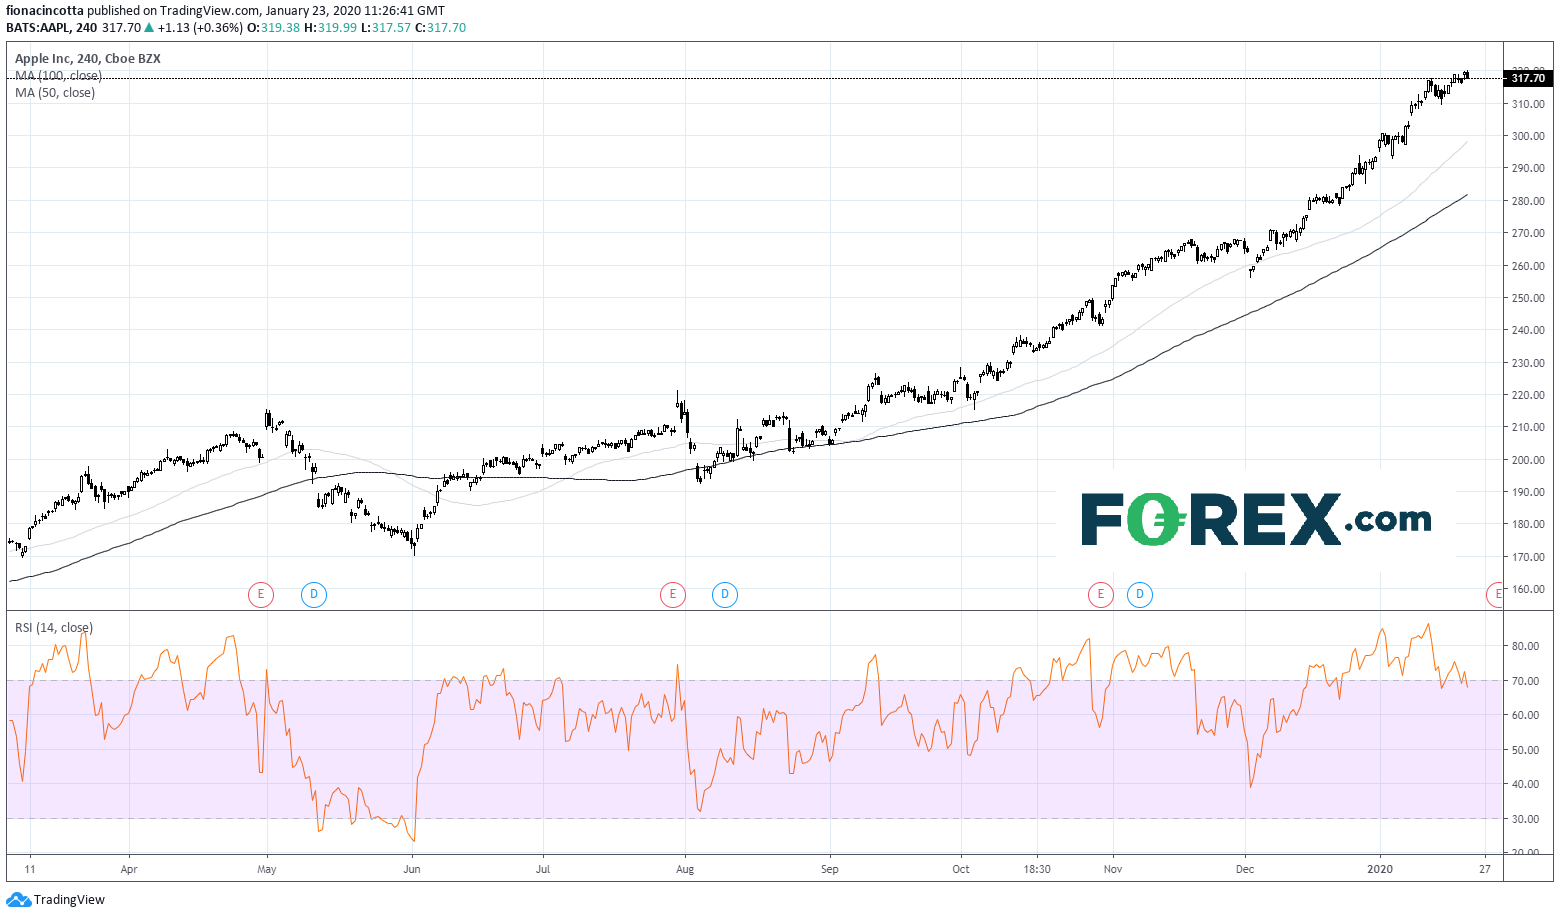
Apple trades firmly above its 50, 100 and 200 sma on a strongly bullish 4 hour chart. On the RSI, it has dipped back below 70 so is no longer in over bought territory. Immediate resistance is at $319.99 the recent all-time high. Immediate support is at the psychological level of $300.
When:
Tuesday 28th January after US close
Tuesday 28th January after US close
Expectations:
Revenue $85.5 billion - $89.5 billion
EPS $4.53
Revenue $85.5 billion - $89.5 billion
EPS $4.53
A lot to live up to
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
Favourable earnings expected
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Key points to watch for on earnings call:
1. 5G – management comments on plan to capitalise on 5G network
2. Emerging services – comments on financial services, how Apple card is performing, and healthcare could be increasingly important drivers in 2020.
3. Non – smart phone products – after strong Christmas sales of Apple watches and Air Pods Pro
Risks Ahead - Upgrade cycle 2020
Recent optimism surrounding Apple is owing to the upgrade cycle that the broader smart phone market is heading into. For the past few years customers have had little reason to upgrade or replace their phones, hanging onto their devices for longer.
1. 5G – management comments on plan to capitalise on 5G network
2. Emerging services – comments on financial services, how Apple card is performing, and healthcare could be increasingly important drivers in 2020.
3. Non – smart phone products – after strong Christmas sales of Apple watches and Air Pods Pro
Risks Ahead - Upgrade cycle 2020
Recent optimism surrounding Apple is owing to the upgrade cycle that the broader smart phone market is heading into. For the past few years customers have had little reason to upgrade or replace their phones, hanging onto their devices for longer.
With the build out of the 5G network, customers will have a reason to upgrade their phones. 5G and China are expected to be big drivers of growth at Apple. US, UK and Korea will also play their part.
It is this upgrade cycle, the wearables business and Apple’s focus on services, which are the main reasons behind analysts lifting Apple’s price target, helping to lift the share price.
There is of course no guarantee that the 5G upgrade cycle will appear. There is always the possibility that investors won’t be wowed by Apple’s 5G iPhone or simply aren’t interested in upgrading to 5G. iPhone shipments actually declined during the move from 3G to 5G.
As demand expectations have helped lift Apple shares to $319.99, should that demand fail to materialise across the coming year, Apple’s share price take a hit.
Chart thoughts
Apple trades firmly above its 50, 100 and 200 sma on a strongly bullish 4 hour chart. On the RSI, it has dipped back below 70 so is no longer in over bought territory. Immediate resistance is at $319.99 the recent all-time high. Immediate support is at the psychological level of $300.
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

S&P 500, Nasdaq 100 Forecast for the Week Ahead
A hawkish Fed and 10-Year Notes on the verge of a push above 5%, yet stocks have so far shrugged off that fear. But can it continue?


Hang Seng Tech rout nears make-or-break zone
The technical damage is clear, but with Hang Seng Tech now deeply stretched and approaching major support, the risk-reward is becoming more two-sided.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.