




Deutsche discovers deeper downside
Deutsche Bank manages to pull out fresh negative surprises
Share this:

Deutsche Bank manages to pull out fresh negative surprises
That is despite the lender having signalled continued operational weakness when it launched its latest revamp plan just weeks ago. The battered shares, down 90% since June 2007, have ceded the remainder of gains made in what was looking like one of their better years, with a rise of as much as 17% by March on turnaround hopes. On Tuesday, the stock fell almost 6% at one point as it became clearer that such hopes are, again, forlorn.
Key points from Q2 results
- Larger than previously forecast €3.2bn net loss, partly due to an also bigger than guided restructuring charge: €3.8bn
- Worst-amongst-peers trading result with revenues down 12% vs. -8% average markets business declines at Wall Street rivals
Equities (to be wound down) - down about 30%; some clients exited before finalisation of a deal to transfer part of the book to BNP Paribas
Bonds - a historically strong business that will be retained, down 11%
- Soon-to-be-carved-out ‘global transaction bank’ - down 6%
Deutsche execs have taken the opportunity to warn that ECB and Fed rate cuts could yet upend the latest in a string of turnaround targets. Shares barely reacted favourably to DB’s plans outlined earlier in July, signalling deep scepticism from years of missed goals remains. Wednesday’s management comments can only undermine the credibility of the latest plans even further. Pledges to increase adjusted group revenues by 2% per annum and improve return on tangible equity to 8% from around 2% currently could be judged as has having a no better than 50% chance of being honoured. The bias for the stock should therefore indicate further reversal of optimistic gains made in the first half of 2019.
Chart thoughts
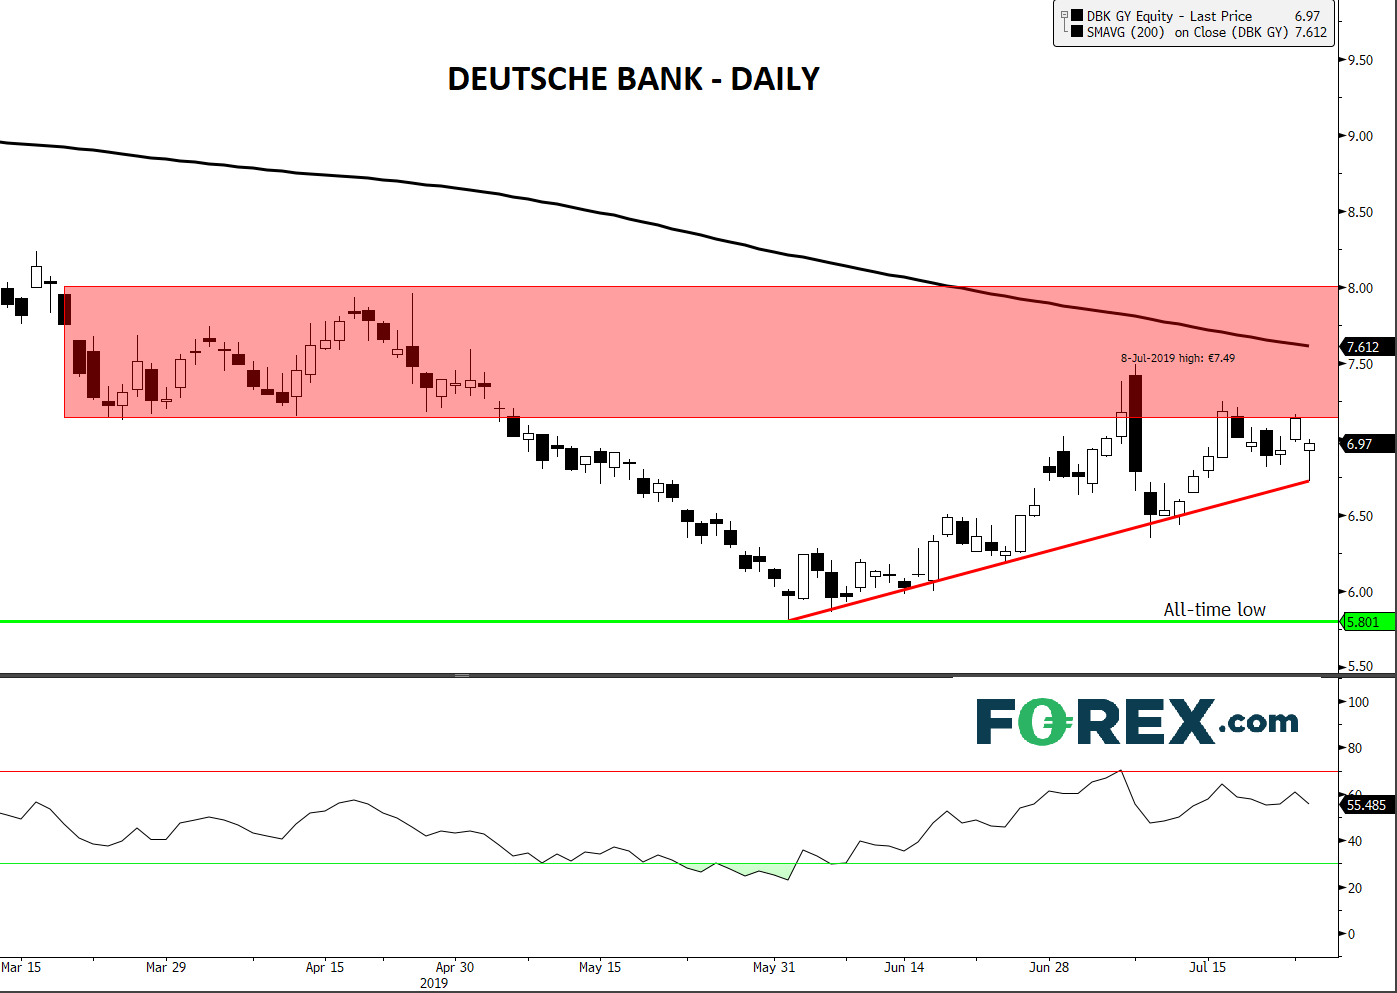
DBK remains a moveable feast for bears, despite a confident-looking advance earlier in the year, apparently triggered by the stock’s lowest ever price of €5.801 in May. That is not a solid basis for gains in itself, so after a defeat at the hands of a fairly innocuous looking resistance zone topped by €8 in March, the shares are now testing rising trend line support created by the upswing. Below here—assuming the RSI’s downwards drift is a reliable signal—the obvious near-term base case would be a return towards €5.80. To disrupt this theme, DB would first need to somehow escape the totemic-looking failure high of €7.49 on 8th July, before tackling the declining 200-day moving average. The chances of that happening in the near term are almost certainly minimal.
Deutsche Bank AG – Daily
Source: Bloomberg/FOREX.com
Deutsche Bank manages to pull out fresh negative surprises
That is despite the lender having signalled continued operational weakness when it launched its latest revamp plan just weeks ago. The battered shares, down 90% since June 2007, have ceded the remainder of gains made in what was looking like one of their better years, with a rise of as much as 17% by March on turnaround hopes. On Tuesday, the stock fell almost 6% at one point as it became clearer that such hopes are, again, forlorn.
Key points from Q2 results
- Larger than previously forecast €3.2bn net loss, partly due to an also bigger than guided restructuring charge: €3.8bn
- Worst-amongst-peers trading result with revenues down 12% vs. -8% average markets business declines at Wall Street rivals
Equities (to be wound down) - down about 30%; some clients exited before finalisation of a deal to transfer part of the book to BNP Paribas
Bonds - a historically strong business that will be retained, down 11%
- Soon-to-be-carved-out ‘global transaction bank’ - down 6%
Deutsche execs have taken the opportunity to warn that ECB and Fed rate cuts could yet upend the latest in a string of turnaround targets. Shares barely reacted favourably to DB’s plans outlined earlier in July, signalling deep scepticism from years of missed goals remains. Wednesday’s management comments can only undermine the credibility of the latest plans even further. Pledges to increase adjusted group revenues by 2% per annum and improve return on tangible equity to 8% from around 2% currently could be judged as has having a no better than 50% chance of being honoured. The bias for the stock should therefore indicate further reversal of optimistic gains made in the first half of 2019.
Chart thoughts
DBK remains a moveable feast for bears, despite a confident-looking advance earlier in the year apparently triggered by the stock’s lowest ever price of €5.801 in May. That is not a solid basis for gains in itself, so after a defeated at the hands of by a fairly innocuous looking resistance zone topped by €8 in March, the shares are now testing rising trendline support created by the upswing. Below here—assuming the RSI’s downwards drift is a reliable signal—the obvious near-term base case would be a return towards €5.80. To disrupt this theme, DB would need to first somehow escape the totemic-looking failure high of €7.49 on 8th July, before tackling the declining 200-day moving average. The chances of that happening in the near term are almost certain to be minimal.
Deutsche Bank AG – Daily
Source: Bloomberg/City Index
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD Update: Will Fed Expectations Keep Pressure on the Euro?
The week continues to present challenges for the euro's short-term strength. This is reflected in the recent performance of EUR/USD, which has declined by nearly 0.6% over the last three trading sessions

EUR/USD Forecast: Euro Extends Losses Ahead of Fed Rate Decision
The euro has started to face a more challenging period in the short term. The EUR/USD pair has already declined by nearly 0.81% over the last four trading sessions, a move that has begun to reinforce a meaningful bearish bias in favor of the U.S. dollar.
EUR/USD Analysis: Euro Attempts to Recover Following the ECB Decision
Today's session has been particularly relevant for the euro's performance in the short term. After the EUR/USD registered a decline of nearly 0.3% during the session, the European currency has managed to recover a large part of its losses.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.