




USD/JPY and USD/CAD continue to slide ahead of US CPI and BOC meeting
USD/JPY is trying to notch up its fifth daily decline (which would be its first this year) whilst USD/CAD also falls on bets of weak US inflation and a BOC hike today.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 22 points (0.31%) and currently trades at 7,130.90
- Japan's Nikkei 225 index has fallen by -198.64 points (-0.62%) and currently trades at 32,203.57
- Hong Kong's Hang Seng index has risen by 215.34 points (1.15%) and currently trades at 18,875.17
- China's A50 Index has risen by 12.94 points (0.1%) and currently trades at 12,613.00
UK and Europe:
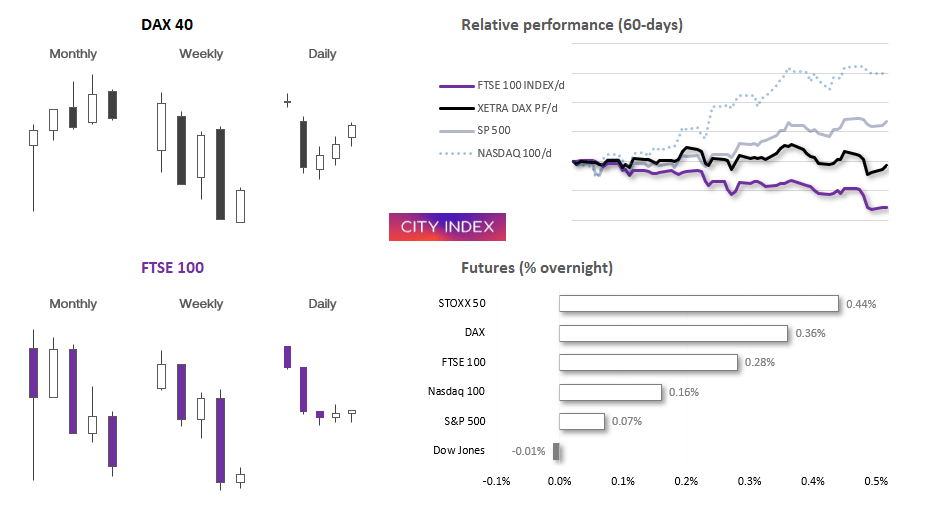
- UK's FTSE 100 futures are currently up 21 points (0.29%), the cash market is currently estimated to open at 7,303.52
- Euro STOXX 50 futures are currently up 18 points (0.42%), the cash market is currently estimated to open at 4,304.56
- Germany's DAX futures are currently up 55 points (0.35%), the cash market is currently estimated to open at 15,845.34
US Futures:
- DJI futures are currently down -9 points (-0.03%)
- S&P 500 futures are currently up 2.5 points (0.06%)
- Nasdaq 100 futures are currently up 21.75 points (0.14%)

- The RBNZ held interest rates at 5.5%, which is their first pause after 12 consecutive hikes totalling 525bp. Their statement maintained a dovish stance, which keeps expectations for the peak rate at 5.5%
- From 2024, the RBA are to implement changes recommended by an independent review, such as reducing monetary policy meetings from 11 per year to 8, releasing the SOMP (statement on monetary policy) alongside a meeting and holding a media conference after each meeting
- The DAX rose for a third day as it joined European shares hopes of a softer US inflation print (despite economic data for Germany and the eurozone_ and index futures markets are also higher ahead of the open
- The US dollar is currently the weakest major as traders continue to place bets of a weak inflation report, which could lead to some disappointment, short-covering and USD buying if inflation throws a curve-ball and comes in hot
- Canada’s strong employment report on Friday has bolstered bets of another 25bp BOC hike today at 15:00 BST, which leaves the question as to whether it will be a ‘one and done’ affair or it includes a hawkish undertone to tease with further hikes.
- USD/CAD has touched a 2-week low ahead of today’s BOC meeting, where a hawkish hike alongside soft US inflation could send it further towards the June low
- Stronger UK wages data all but confirms another 50bp BOE hike and for a terminal rate above 6%, which saw the pound continue to strengthen during the Asian session and push GBP/USD to a 15-month high and just shy of our 1.3000 target
- EUR/GBP closed at an 11-month low yesterday and now trades within a tight range near yesterday’s lows. Whilst this runs the risk of a countertrend stop run after the UK open, bears may be waiting to renter shorts at higher levels to rive the pair lower
- USD/CHF broke to a fresh YTD low yesterday on hopes of a soft US CPI report and now trades just 20-pips above the 2021 low (the next line of defence for bulls)
USD/JPY daily chart:
The selloff on USD/JPY continues and is within its fifth day lower during the Asian session. Whilst we need to see how US inflation goes to confirm the fifth day, it is worth noting that it has not closed lower for five days since December (and the time prior to that was in April 2021). This metric alone has us on guard for a potential inflection point. And the fact that it is also within its worst 5-day run in seven months whilst the decline is fast approaching several technical support levels simply adds to the conviction that an inflection point may be close.
Does not make it a great entry for bulls to consider? Perhaps, but not necessarily. But it should at least serve as a warning to bears to reconsider before loading up at what could become cycle lows. At a minimum we suspect a pause in trend, but if prices are to bounce it is difficult to say how far or for how long.
A meaningful countertrend rally could require a particularly strong inflation report from the US coupled (which seems unlikely). Therefore, traders may want to refer to lower timeframes to seek opportunities, whilst keeping in mind the bigger picture levels nearby.


USD/CAD daily chart:
USD/CAD has fallen to a 2-week low in line with our bearish bias which was outlined on Monday. We didn’t see much of a pullback inside Friday’s range, but Tuesday’s break of Friday’s bearish engulfing candle has confirmed the two-bar reversal, which formed almost perfectly at the 50% retracement level and 200-day EMA. Ad as the reversal came at the end of the third wave, we’re looking for a retest and break beneath the June low and run for 1.3000. A hawkish BOC hike and soft US inflation report could likely help with that bias.


View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.

Gold Q4 2026 outlook: Resilience in the face of rallying dollar and yields
As we headed towards the latter stages of Q3 and into Q4, the Fed had just hiked rates in a hawkish FOMC meeting, while the likes of the ECB and BoJ had also tightened their respective policies. Oil prices remained elevated amid the prolonged US-Iran conflict. Meanwhile, bond yields were breaking out, and the dollar was higher across the board. Yet, remarkably, gold was still holding in the positive territory for the third quarter, even if it had weakened somewhat in September.

EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.