



European Open Trading Volumes To Return to Europe NZD firm ahead of RBNZ
With parts of Europe to return to their desks after their 3-day weekends then trading activity (and therefore volumes) should rise today. Also take note that RBNZ hold their policy meeting overnight.
Share this:
Nerves are getting the better of markets again as the summit looms
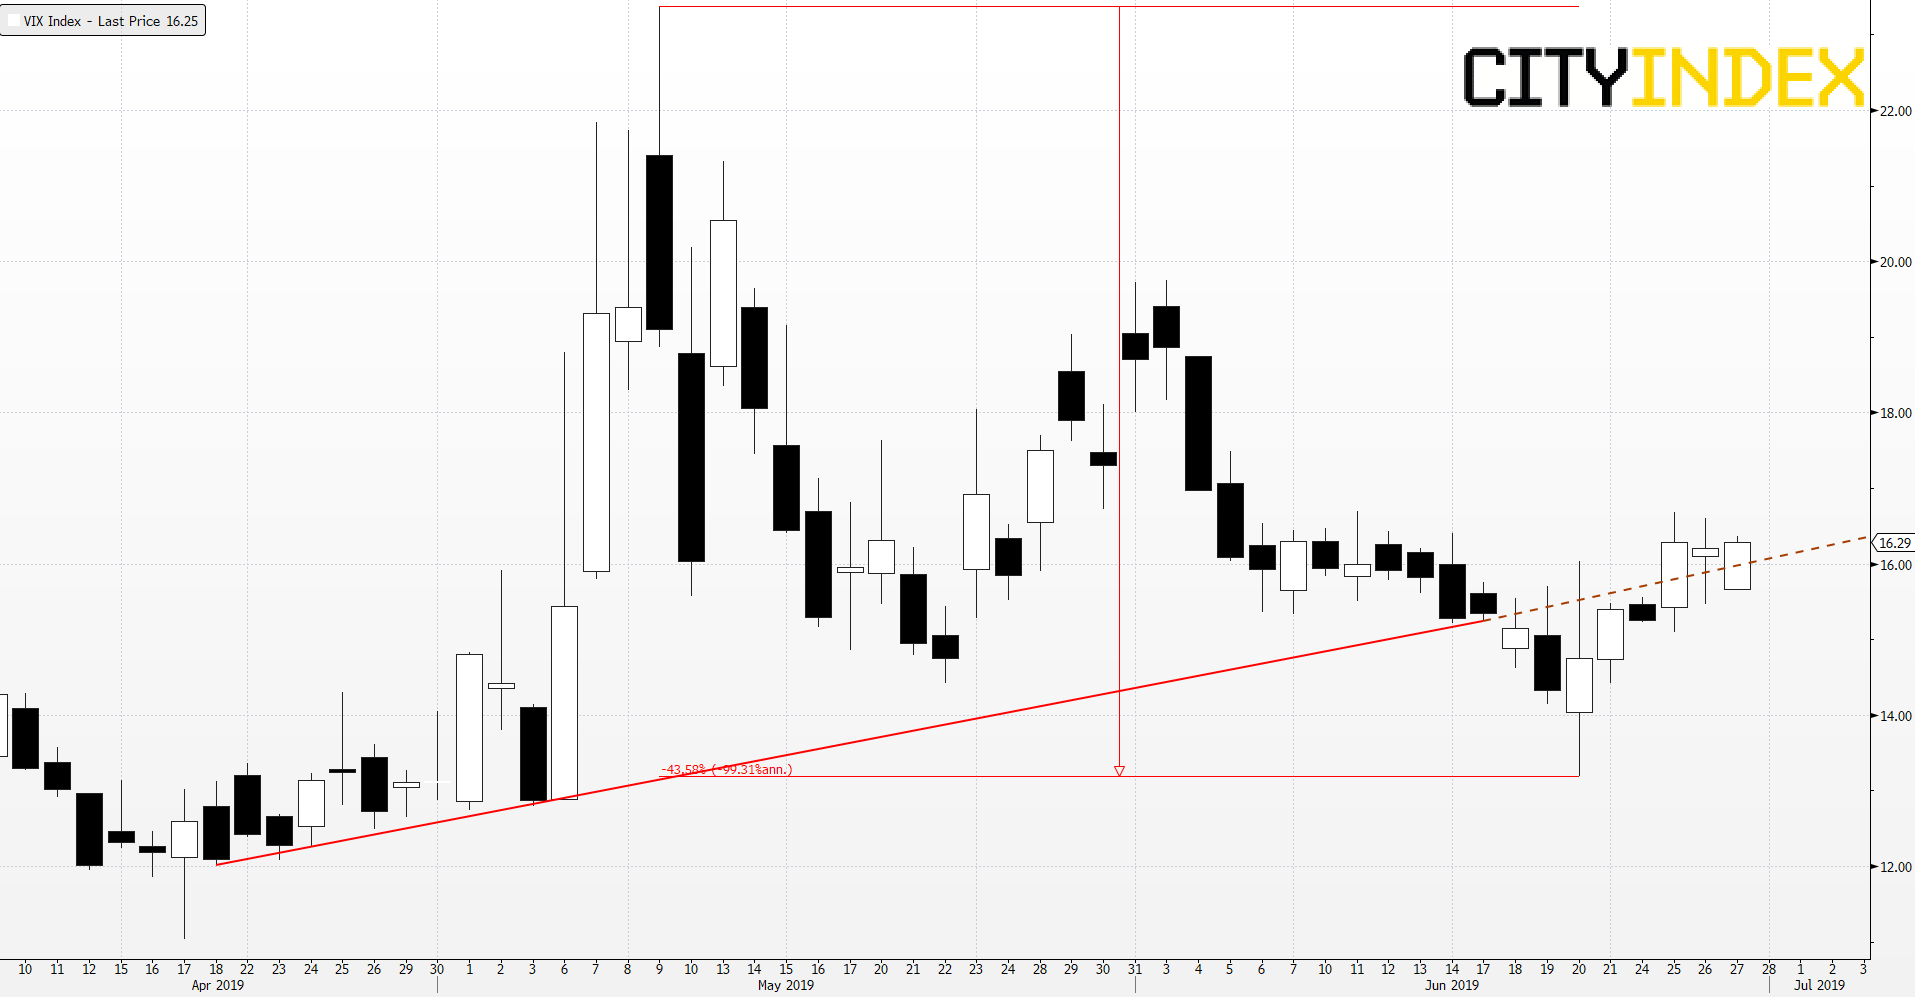
An optimistic tint over European and Asia Pacific markets was also reflected in Wall Street futures for most of Thursday morning. As the start of U.S. trading approaches though, futures there look more mixed and Europe’s confidence has again evaporated. That’s after U.S. shares saw a similar early ramp fizzle towards the end of their prior session, succumbing to the same jitters that capped Continental markets on Wednesday. The return of higher variance was marked by a spring back in implied volatility nominally projected by CBOE’s VIX gauge. Circumstantially, the lack of follow-through that typically follows reversion of this indicator to its recent baseline could be indicative. So could observations that the VIX is attempting to retake values above the floor of its rising trend since April.
CBOE VIX – daily [27-11-2019 1118 BST]
Source: Bloomberg/City Index
In short, there are decent signs that the apparent return of poise to risky assets may not run deep. As a re-cap, the logic underpinning the optimistic case ahead of this weekend’s G20 summit is as follows:
- Although the pattern of commentary that typically emanates from Washington ahead of trade talks is evident—reiterated threats combined with constructive affirmations—the U.S. has maintained a relatively consistent stance into the negotiations. U.S. Commerce Secretary Wilbur Ross noted last week that the G20 was too broad for detailed progress. And markets have been prepared for weeks for a best-case scenario that would merely see further tariffs suspended. Contained expectations ought to mean that any disappointment will also be limited
- In itself, the fact that there are concrete plans for a meeting at all has reduced the risk of further escalation. Donald Trump’s repeated boast of a warm relationship with Xi should also reduce dangers that their dispute will deepen in Osaka. Trump has twice agreed to postpone tariff hikes: with the European Union’s Jean-Claude Juncker last July and with Xi in December
The negative case, and the one which appears to have largely prevailed on this side of the Atlantic, is that U.S. President Donald Trump’s recent remark that he was ‘in no hurry’ to seal a trade deal with China might carry more weight than appeared on the surface. The STOXX Europe 600 Auto & Parts index continues to sharply underperform the broader market on a year-to-date basis, including the monetarily implicated STOXX Banks index. Automobiles is the only sector singled out explicitly for possible U.S. tariffs. Although a decision was deferred in May for up to six months, the terms of the suspension keep the threat of levies on the table. The basics of the pessimistic case:
- Mexico’s agreement to further clamp downs on illegal border crossings after tariff threats may have emboldened White House trade hawks to continue apply the strategy against China
- Furthermore, the likelihood of monetary easing may convince the President that the U.S. will soon have an economic cushion. Given his evident desire for rate cuts, he may even see a chance of killing two birds with one stone
Whilst the highest probability outcome remains a suspension of tariffs, the broader picture continues hint at a ‘June Swoon’ (or an early July swoon) regardless of trade relief. Aside from telling equity fund outflows in recent weeks and chart technical indications, another intimation is that allocations to U.S. government and prime funds have soared in 2019 to more than $3 trillion. That’s the most since the financial crisis. Ostensibly, this has been driven by U.S. short-term yields exceeding those of longer-maturing bonds. However the trend also depicts cash resolving to the side lines in a way that’s typical of rising uncertainty.


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

Japanese Yen Outlook: USD/JPY, GBP/JPY, AUD/JPY Setups
USD/JPY and GBP/JPY show signs of stabilising, while AUD/JPY remains vulnerable as yen crosses deliver mixed technical signals.


S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.