




FTSE Turns Positive
European bourses are heading lower in early trade on Monday as investors pause for breath after a phenomenal rally across the month of November. Some European benchmark indices have surged over 20% higher. The FTSE, which has reversed earlier losses is outperforming its peers.
Share this:
European bourses are heading lower in early trade on Monday as investors pause for breath after a phenomenal rally across the month of November. Some European benchmark indices have surged over 20% higher. The FTSE, which has reversed earlier losses
Vaccine optimism has driven risk appetite and stock markets higher across November. Over the past month Pfizer, Moderna and AstraZeneca have all revealed upbeat results from their clinical trials. A vaccine is the quickest and surest way for global growth to return to pre-pandemic levels.
News that the UK regulators could approve the Pfizer vaccine in the coming days is keeping optimism surrounding UK stocks buoyant. The FTSE is outperforming its European peers, pushing into positive territory.
JD Sports is a clear winner, topping the as investors cheer the athleisure retailer stepping back from talks with Debenhams. JD Sports jumps 6.7%, even as trouble on the high street brews.
Oil drops 1%, oil majors decline
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Gold has lost its shine
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
Coming up
Looking ahead, UK mortgage approvals will keep house builders in focus. Approvals have been particularly strong across recent months as prospective buyers look to take advantage of the government’s stamp duty holiday scheme, which is set to run until March.
German inflation data is also due later. Expectations are for inflation to remain subdued in disinflation as the Eurozone’s largest economy extends its lockdown until 20th December.
Looking ahead, UK mortgage approvals will keep house builders in focus. Approvals have been particularly strong across recent months as prospective buyers look to take advantage of the government’s stamp duty holiday scheme, which is set to run until March.
German inflation data is also due later. Expectations are for inflation to remain subdued in disinflation as the Eurozone’s largest economy extends its lockdown until 20th December.
FTSE Chart
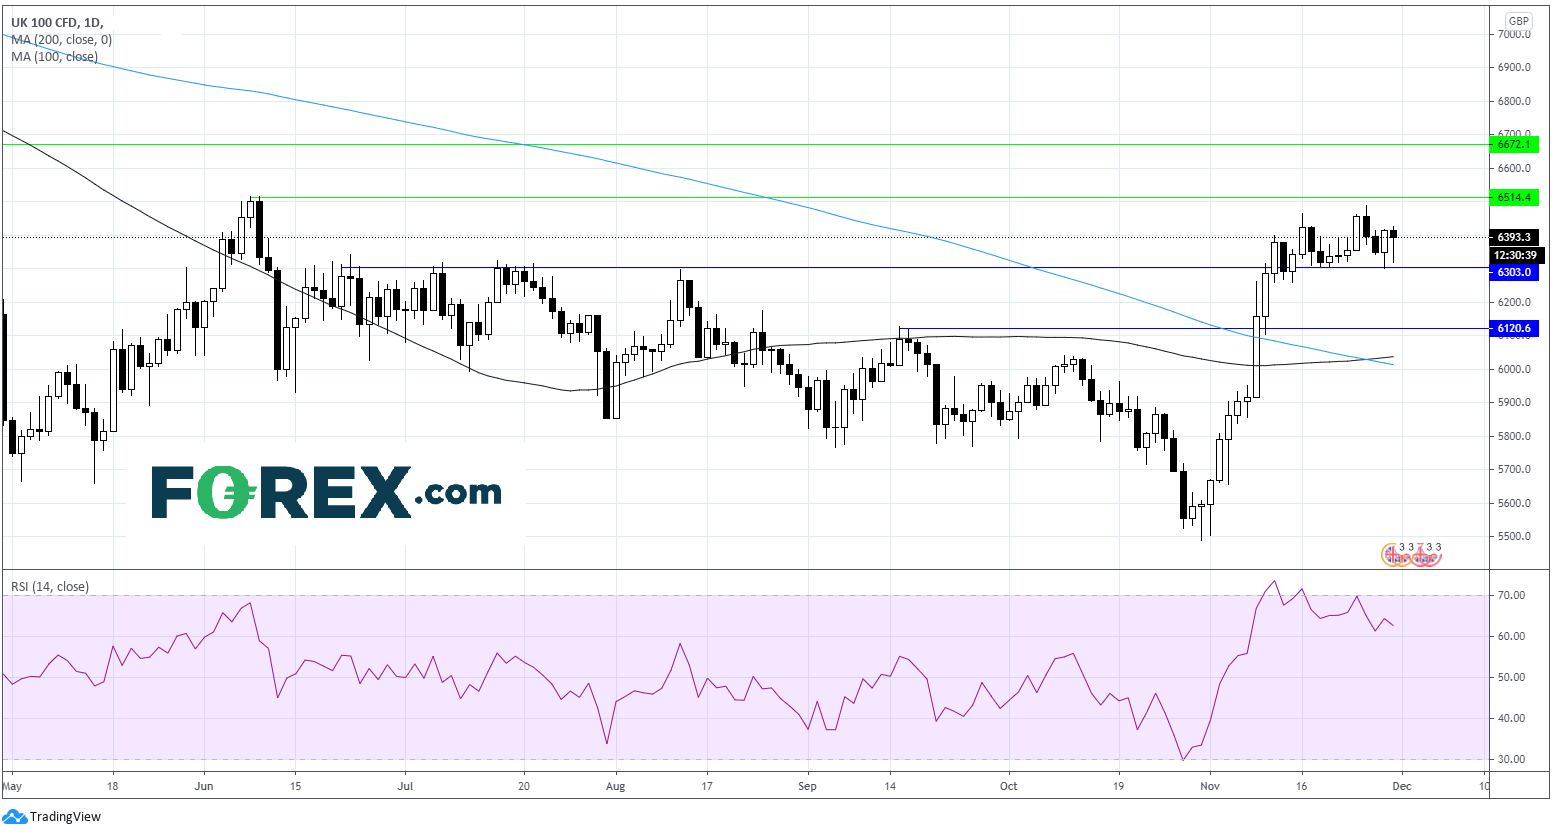
The FTSE continues to consolidate in the horizontal channel 6300 – 6515. The index rebounded off the lower band of the channel at the end of last week and is heading back towards the upper band at 6515. A break above this level could see the FTSE advance to 6670 a level last seen in March. On the flip side immediate a break through 6300 could open the door to horizontal support at 6120 prior to 200 day moving average and psychological support at 6000.
European bourses are heading lower in early trade on Monday as investors pause for breath after a phenomenal rally across the month of November. Some European benchmark indices have surged over 20% higher. The FTSE, which has reversed earlier losses
Vaccine optimism has driven risk appetite and stock markets higher across November. Over the past month Pfizer, Moderna and AstraZeneca have all revealed upbeat results from their clinical trials. A vaccine is the quickest and surest way for global growth to return to pre-pandemic levels.
News that the UK regulators could approve the Pfizer vaccine in the coming days is keeping optimism surrounding UK stocks buoyant. The FTSE is outperforming its European peers, pushing into positive territory.
JD Sports is a clear winner, topping the as investors cheer the athleisure retailer stepping back from talks with Debenhams. JD Sports jumps 6.7%, even as trouble on the high street brews.
Oil drops 1%, oil majors decline
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Oil stocks are the biggest drag on the FTSE with the likes of BP and Royal Dutch Shell – over 2%, tracing the commodity lower. Oil has dropped almost 1% after an informal OPEC meeting on Sunday revealed that divisions remains over whether to extend production cuts beyond January. The group will meet today to hammer out plans for output in the new year, failure for the group to agree a new deal means that the originally planned output increase of 2 million more barrels a day will come into effect.
Gold has lost its shine
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
As risk sentiment rose across the previous week a demand for stocks rose, safe haven Gold fell out of favour, closing below its 200 day moving average for the first time since January in an ominous sign. Precious metal miner Fresnillo is under pressure down 3.4% in the first hour of trading.
Coming up
Looking ahead, UK mortgage approvals will keep house builders in focus. Approvals have been particularly strong across recent months as prospective buyers look to take advantage of the government’s stamp duty holiday scheme, which is set to run until March.
German inflation data is also due later. Expectations are for inflation to remain subdued in disinflation as the Eurozone’s largest economy extends its lockdown until 20th December.
Looking ahead, UK mortgage approvals will keep house builders in focus. Approvals have been particularly strong across recent months as prospective buyers look to take advantage of the government’s stamp duty holiday scheme, which is set to run until March.
German inflation data is also due later. Expectations are for inflation to remain subdued in disinflation as the Eurozone’s largest economy extends its lockdown until 20th December.
FTSE Chart
The FTSE continues to consolidate in the horizontal channel 6300 – 6515. The index rebounded off the lower band of the channel at the end of last week and is heading back towards the upper band at 6515. A break above this level could see the FTSE advance to 6670 a level last seen in March. On the flip side immediate a break through 6300 could open the door to horizontal support at 6120 prior to 200 day moving average and psychological support at 6000.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.


Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.