





Market Brief Asian Equities Solidify Gains
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- China vowed to retaliate after the US House voted to pass a human rights bills, which effectively provides support to pro-democracy protesters in Hong Kong. Risk came off a little with E-mini futures dropping slightly and JPY gaining inflows, making it today’s strongest major. Although we’ll need to see if the senate passes the bill for it to have any meaningful impact.
New Zealand CPI slowed to 1.5% YoY from 1.7% prior, yet shortly after RBNZ said their own measure of CPI remained at 1.7%. Still, RBNZ suggested further cuts may be needed and that they continue to undertake prep work on ‘less conventional’ (QE) tools should they be required. NZD and AUD are currently the weakest majors on the session, which are also being weighed down by the pro-democratic bill voted by the US House of Representatives. - The British pound wavered as doubts again grew whether a Brexit deal could be reached, seeing GBP retrace a tad after its best 4-day rally since 2016. With yen taking inflows, GBP/JPY was the third biggest mover, whilst NZD/JPY was the only pair to reach its typical daily range and is today’s biggest mover (so perhaps the move is overdone?)
Equity Brief:
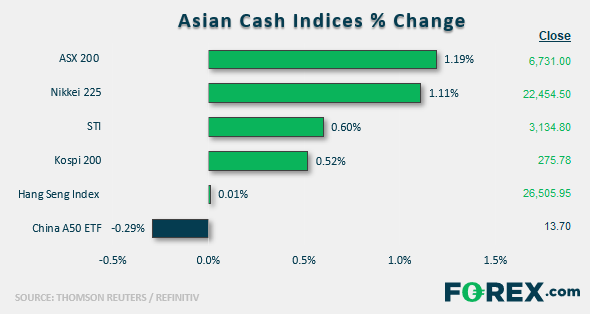
- Most Asian stock markets have continued to solidify their gains since the start of the week taking the cue from the U.S. stock market where both the S&P 500 and Nasdaq 100 have rallied by 1.00% and 1.28% respectively on the backdrop of Q3 earnings optimism.
- China and Hong Kong’s stock markets do not manage to sail along the “bullish wave”. The political situation in Hong Kong has become the latest flash point between U.S. and China on top of an on-going trade war. The U.S. House of Representatives has just passed a bill that offer support to pro-democracy protestors in Hong Kong. A similar bill is now in front of the Senate (the upper house of the U.S. Congress) for voting. China has threatened to retaliate if U.S. Congress passes the bill that can complicate the on-going negotiation talks to put “Phase 1 of the U.S.-China trade deal” in writing.
- The Japan stock market has continued to shine where the Nikkei 225 is upped by 1.19% for a second consecutive session. It also rallied to a 10-month high at 22615 led by semiconductor related stocks reinforced by the positive sentiment seen in the U.S. Philadelphia Semiconductor Index that has surged to a fresh all-time high in terms of closing level yesterday. Tokyo Electron and Advantest have outpaced the Nikkei 225 with gains of 1.8% and 3.7% respectively.
- The S&P 500 E-Mini futures have continued to pull-back in today’s Asian session after a test on the 3000 psychological level in yesterday U.S. session. It has dropped by -0.30% to print a current intraday low of 2986.
Up Next
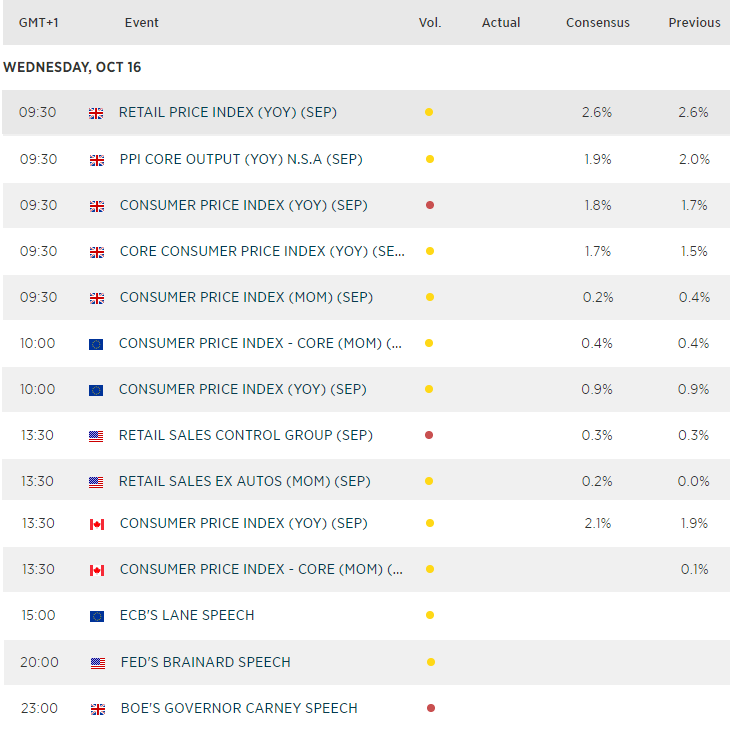
- UK inflation, producer and retail prices make up the baulk of UK data, with prices mostly being expected to soften. Still, it’s more likely Brexit headlines which could make a material impact on GBP crosses over the next couple of days.
- US retail sales provides a feel for consumer spending, which is expected to rise 0.2% from 0% prior.
Matt Simpson and Kelvin Wong both contributed to this article
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
- China vowed to retaliate after the US House voted to pass a human rights bills, which effectively provides support to pro-democracy protesters in Hong Kong. Risk came off a little with E-mini futures dropping slightly and JPY gaining inflows, making it today’s strongest major. Although we’ll need to see if the senate passes the bill for it to have any meaningful impact.
New Zealand CPI slowed to 1.5% YoY from 1.7% prior, yet shortly after RBNZ said their own measure of CPI remained at 1.7%. Still, RBNZ suggested further cuts may be needed and that they continue to undertake prep work on ‘less conventional’ (QE) tools should they be required. NZD and AUD are currently the weakest majors on the session, which are also being weighed down by the pro-democratic bill voted by the US House of Representatives. - The British pound wavered as doubts again grew whether a Brexit deal could be reached, seeing GBP retrace a tad after its best 4-day rally since 2016. With yen taking inflows, GBP/JPY was the third biggest mover, whilst NZD/JPY was the only pair to reach its typical daily range and is today’s biggest mover (so perhaps the move is overdone?)
Equity Brief:
- Most Asian stock markets have continued to solidify their gains since the start of the week taking the cue from the U.S. stock market where both the S&P 500 and Nasdaq 100 have rallied by 1.00% and 1.28% respectively on the backdrop of Q3 earnings optimism.
- China and Hong Kong’s stock markets do not manage to sail along the “bullish wave”. The political situation in Hong Kong has become the latest flash point between U.S. and China on top of an on-going trade war. The U.S. House of Representatives has just passed a bill that offer support to pro-democracy protestors in Hong Kong. A similar bill is now in front of the Senate (the upper house of the U.S. Congress) for voting. China has threatened to retaliate if U.S. Congress passes the bill that can complicate the on-going negotiation talks to put “Phase 1 of the U.S.-China trade deal” in writing.
- The Japan stock market has continued to shine where the Nikkei 225 is upped by 1.19% for a second consecutive session. It also rallied to a 10-month high at 22615 led by semiconductor related stocks reinforced by the positive sentiment seen in the U.S. Philadelphia Semiconductor Index that has surged to a fresh all-time high in terms of closing level yesterday. Tokyo Electron and Advantest have outpaced the Nikkei 225 with gains of 1.8% and 3.7% respectively.
- The S&P 500 E-Mini futures have continued to pull-back in today’s Asian session after a test on the 3000 psychological level in yesterday U.S. session. It has dropped by -0.30% to print a current intraday low of 2986.
Up Next
- UK inflation, producer and retail prices make up the baulk of UK data, with prices mostly being expected to soften. Still, it’s more likely Brexit headlines which could make a material impact on GBP crosses over the next couple of days.
- US retail sales provides a feel for consumer spending, which is expected to rise 0.2% from 0% prior.
Matt Simpson and Kelvin Wong both contributed to this article
*Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.