




Market Brief Mild Risk On From Trade Optimism
A summary of news and snapshot of moves from today’s Asia session.
Share this:

View our guide on how to interpret the FX Dashboard
FX Brief:
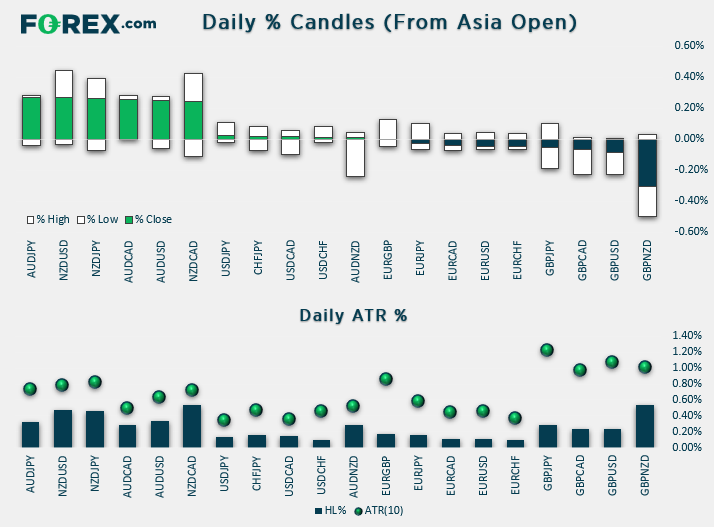
- NZD spiked lower on comments from New Zealand’s Treasury that they suspect S&P may remove their positive ratings outlook. Still, it currently trades just off a 2-day high.
- US Treasury are considering whether to further delay tariffs on $34 billion in Chinese goods, allowing USD to remain supported on trade optimism.
- DXY (US dollar index) trades in a narrow range and within yesterday’s bearish candle, AUD/USD hit s 3-day high and USD/JPY briefly touched an intraday 3-month high.
- AUD and NZD are the strongest majors. All pairs remain well within their typical daily ranges, with the overall average daily range at just 39% of its 10-day ATR.

Equity Brief:

- Most Asian stock markets have continued to extend their gains in place since last week reinforced by the increased possibility of a “Phase 1 U.S-China trade deal” being signed off by mid Nov when President Trump meets his counterpart, China’s Xi at the APEC Summit on 16-17 Nov. In addition, key U.S. benchmark stock indices; the S&P 500 and Nasdaq 100 have also broken new record highs.
- Singapore’s Strait Times Index (STI) has continued to rally for a 3rd consecutive session after a public holiday break yesterday, it is upped by 0.53% as at today’s Asian mid-session ahead of the big three banks Q3 earnings releases with UOB out on Fri, 01 Nov follow by OCBC on 05 Nov and lastly, DBS on 11 Nov.
- The current up move of the STI has hit a 3 -month high of 3227 on an intraday basis led by Jardine Matheson Holdings and Jardine Strategic Holdings that has rallied by 2.5% and 1.7% respectively.
- Hong Kong’s Hang Seng Index has continued to underperform, down by -0.40% after its failure to breach above the 27000 psychological level. Banks and heaving weight component stocks are the main drag where HSBC and Hang Seng Bank have declined by -1.66% and -1.57% respectively. Asia largest technology firm, Tencent which is also the 2nd largest component stock in the HSI has shed -1.49% to print an intraday low of 317.00, a whisker away from a major support level of 316.80.
- In addition, a Hong Kong key official, Financial Secretary Paul Chan has written a blog post that has highlighted the 4-month long street protests have caused Hong Kong to enter into a technical recession; Hong Kong will announce its Q3 GDP data on Thurs, 31 Oct.
Up Next
- UK parliament are set to vote again on Boris Johnson’s proposed Dec 12th election, GBP crosses will be the main focus.
- Quiet in terms of economic data, so ranges may be limited without a catalyst.
- RBA's Governor Philip Lowe is due to speak at 6:45am GMT
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
View our guide on how to interpret the FX Dashboard
- NZD spiked lower on comments from New Zealand’s Treasury that they suspect S&P may remove their positive ratings outlook. Still, it currently trades just off a 2-day high.
- US Treasury are considering whether to further delay tariffs on $34 billion in Chinese goods, allowing USD to remain supported on trade optimism.
- DXY (US dollar index) trades in a narrow range and within yesterday’s bearish candle, AUD/USD hit s 3-day high and USD/JPY briefly touched an intraday 3-month high.
- AUD and NZD are the strongest majors. All pairs remain well within their typical daily ranges, with the overall average daily range at just 39% of its 10-day ATR.
Equity Brief:
Up Next
- UK parliament are set to vote again on Boris Johnson’s proposed Dec 12th election, GBP crosses will be the main focus.
- Quiet in terms of economic data, so ranges may be limited without a catalyst.
- RBA's Governor Philip Lowe is due to speak at 6:45am GMT
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


EUR/USD Q4 2026 Outlook: Euro at a Crossroads as Fed, ECB Tighten 9 25 2026
EUR/USD enters Q4 at a pivotal inflection point as competing Fed-ECB policy paths and persistent inflation risks collide with major technical support.

AUD/USD Q4 Outlook: RBA and Fed Hikes Set the Tone
AUD/USD enters Q4 with RBA and Fed hikes in focus as sticky inflation, rising unemployment and US dollar strength shape the Australian dollar.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.