






Market Brief Mixed Repsonse From Trade Developments
A summary of news and snapshot of moves from today’s Asia session.
Share this:

- US and China are to resume in person trade talks in September, after Trump said discussion were already on the way later today. On Sunday, the US is set to collect a further 15% on Chinese imports worth over $125 billion.
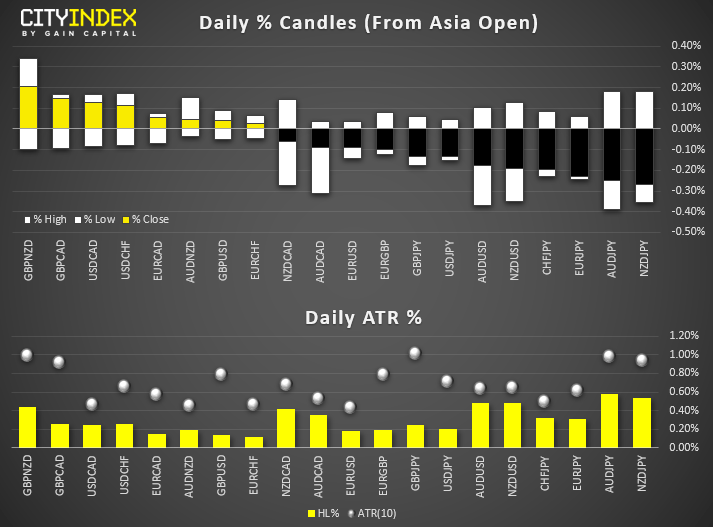
- Whilst this provided a slight tailwind for equities, currency markets were less convinced. AUD and NZD trading firmly lower and are today’s weakest majors (JPY and UD are the strongest). Still, NZD is still reeling form yesterday’s dire business confidence reads, and AUD is under the added pressure of weaker building approvals and housing credit. And looking tariffs which kick on Sunday, along with lower iron ore prices for AUD are also piling on the pressure.
- Mixed data from Japan saw industrial production rebound and retail sales slump. Production rose 1.3% in July (although is -1% % YoY) with expectations for the next 1-2 months at 2.7% and 0.6% respectively, despite concerns over the trade war. Whilst this is good for the business sector, retail sales slumped by 2.5% (fastest contraction since November 2015) to take the YoY rate to -2%. Unemployment fell to 2.2%, its lowest rate since August 1992.
- Asian stock indices have continued to recoup last week’s losses on the theme of “U.S/China trade deal optimism’” where China’s commerce ministry commented yesterday that a Sep meeting was being discussed but added it was important for Washington to cancel a tariff increase. A new round of U.S. tariffs, 15% on US$550 billion worth of Chinese goods is scheduled to take effect on this Sun.
- The best performers are Kospi 200, ASX 200 and Nikkei 225 which have gained by more than 1.00% as at today’s Asian mid-session.
- Interestingly, China A50 has underperformed against the rest where it has inched up only by 0.30%. A firm USD/CNH could be the reason that prevent traders from taking aggressive long positions. The USD/CNH (offshore yuan) has started to recoup yesterday’s losses where it rebounded by 196 pips at the 7.1400/1300 key short-term support to print a current intraday high of 7.1602 in today’s Asia session.
- Hong Kong’s Hang Seng Index’s gains have been lacklustre due to on-going localised social unrest. It has been reported that local police have arrested three prominent protest leaders ahead of planned mass demonstrations this weekend. Key property developer stocks underperformed where Sun Hung Kai Properties, Swire Pacific and CK Assets have traded down by -2.65%, -1.22% and -1.28% respectively.
Up Next
- Hong Kong Retail Sales for Jul out later today at 0830 GMT. Data for Jun came in at -7.6% y/y/ where another round of weak data for Jul is likely to reinforce a technical recession in Q3 for Hong Kong. Q2 GDP came in at -0.4% q/q.
- Canadian GDP is expected to rebound from 0.4% YoY to 3%. Whilst data overall continues to favour BoC not easing, a miss for GDP later today could rattle CAD crosses. However, hittig or exceeding expectations could provide a tailwind for their stock index (TSX 60) which appears to the first of the major indices to break higher form its range.

- US and China are to resume in person trade talks in September, after Trump said discussion were already on the way later today. On Sunday, the US is set to collect a further 15% on Chinese imports worth over $125 billion.
- Whilst this provided a slight tailwind for equities, currency markets were less convinced. AUD and NZD trading firmly lower and are today’s weakest majors (JPY and UD are the strongest). Still, NZD is still reeling form yesterday’s dire business confidence reads, and AUD is under the added pressure of weaker building approvals and housing credit. And looking tariffs which kick on Sunday, along with lower iron ore prices for AUD are also piling on the pressure.
- Mixed data from Japan saw industrial production rebound and retail sales slump. Production rose 1.3% in July (although is -1% % YoY) with expectations for the next 1-2 months at 2.7% and 0.6% respectively, despite concerns over the trade war. Whilst this is good for the business sector, retail sales slumped by 2.5% (fastest contraction since November 2015) to take the YoY rate to -2%. Unemployment fell to 2.2%, its lowest rate since August 1992.
- Asian stock indices have continued to recoup last week’s losses on the theme of “U.S/China trade deal optimism’” where China’s commerce ministry commented yesterday that a Sep meeting was being discussed but added it was important for Washington to cancel a tariff increase. A new round of U.S. tariffs, 15% on US$550 billion worth of Chinese goods is scheduled to take effect on this Sun.
- The best performers are Kospi 200, ASX 200 and Nikkei 225 which have gained by more than 1.00% as at today’s Asian mid-session.
- Interestingly, China A50 has underperformed against the rest where it has inched up only by 0.30%. A firm USD/CNH could be the reason that prevent traders from taking aggressive long positions. The USD/CNH (offshore yuan) has started to recoup yesterday’s losses where it rebounded by 196 pips at the 7.1400/1300 key short-term support to print a current intraday high of 7.1602 in today’s Asia session.
- Hong Kong’s Hang Seng Index’s gains have been lacklustre due to on-going localised social unrest. It has been reported that local police have arrested three prominent protest leaders ahead of planned mass demonstrations this weekend. Key property developer stocks underperformed where Sun Hung Kai Properties, Swire Pacific and CK Assets have traded down by -2.65%, -1.22% and -1.28% respectively.
Up Next
- Hong Kong Retail Sales for Jul out later today at 0830 GMT. Data for Jun came in at -7.6% y/y/ where another round of weak data for Jul is likely to reinforce a technical recession in Q3 for Hong Kong. Q2 GDP came in at -0.4% q/q.
- Canadian GDP is expected to rebound from 0.4% YoY to 3%. Whilst data overall continues to favour BoC not easing, a miss for GDP later today could rattle CAD crosses. However, hittig or exceeding expectations could provide a tailwind for their stock index (TSX 60) which appears to the first of the major indices to break higher form its range.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.