


NZD Hit as Softer CPI Keeps RBNZ Easing in Play
Despite some sticky spots, New Zealand’s latest CPI report points to fading inflation risks—keeping a further RBNZ cut firmly in play.
Share this:
- Q2 CPI rose 2.7% y/y vs 2.8% expected, 2.6% RBNZ forecast
- Core inflation ticked up to 2.7% but stayed within target
- Market sees 85% chance of RBNZ cut in August
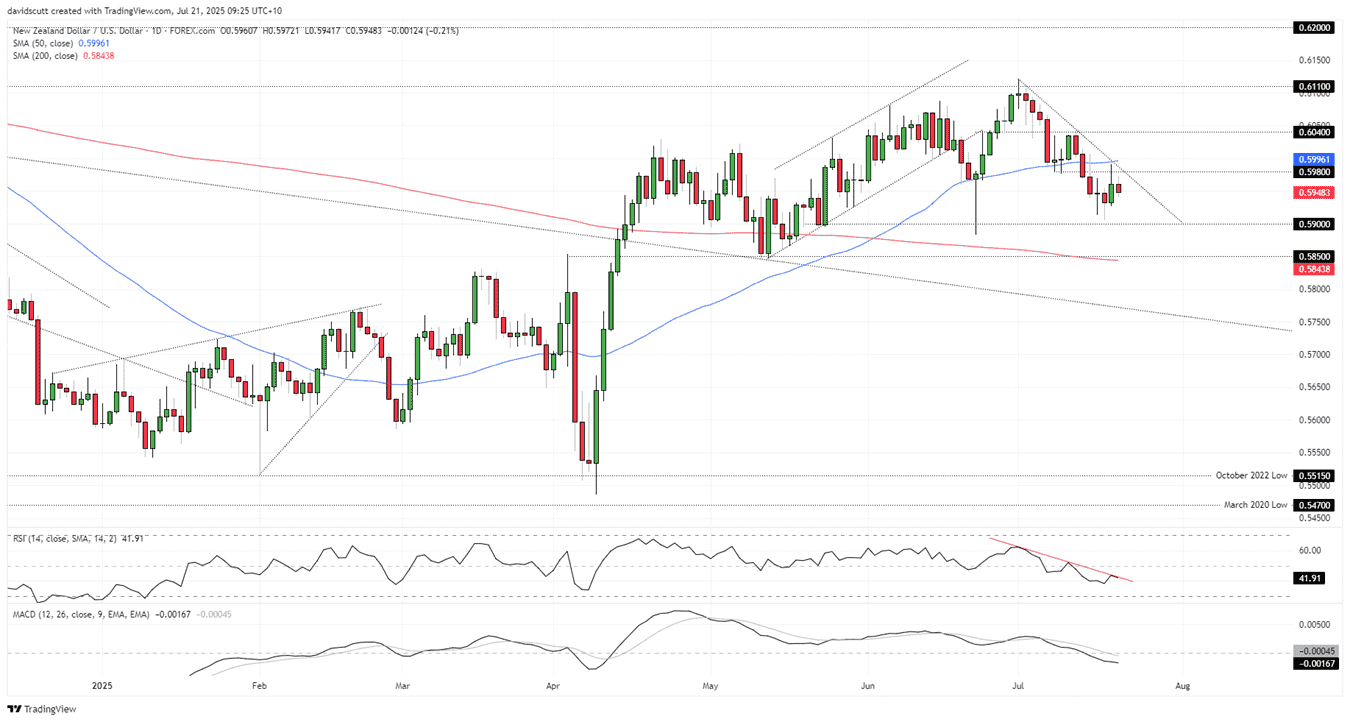
- NZD/USD weaker, stays in firm downtrend
NZD Summary
Consumer prices in New Zealand rose less than forecast in the June quarter, delivering a modest decline in the New Zealand dollar. While marginally above what the Reserve Bank of New Zealand (RBNZ) forecast in May, the underlying detail of the report points to the likelihood of at least one additional rate cut from policymakers over the remainder of the year.
Inflation Remains Contained
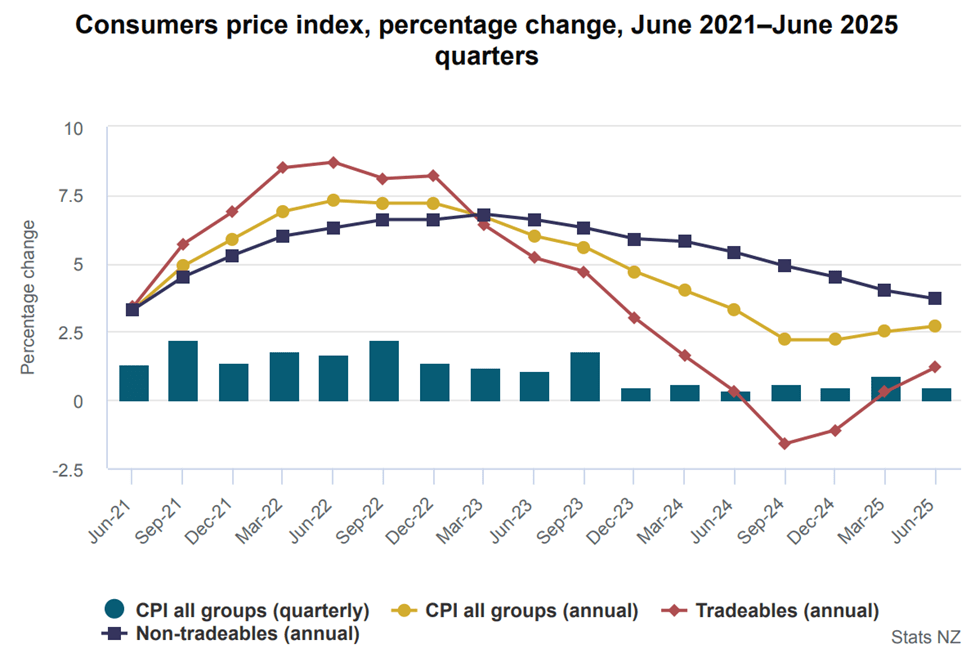
New Zealand’s CPI rose 0.5% in the June quarter and 2.7% over the year, a touch hotter than the RBNZ’s 2.6% forecast but below the 2.8% pace expected by markets. It marked a slight pickup from 2.5% in Q1 but remained within the RBNZ’s 1–3% target band for a fourth consecutive quarter. The biggest driver of the annual increase was local authority rates, up 12.2% and accounting for 13% of the rise—though that lift was captured back in the September 2024 quarter. Petrol prices fell 8% over the year, helping contain the headline result. Excluding petrol, CPI rose 3.2% annually.
Source: StatsNZ
Non-tradeable prices—which typically reflect domestic demand and supply factors—rose 0.7% for the quarter and 3.7% over the year, continuing the disinflationary trend established in early 2023 when it peaked at an annual rate of 6.8%. Tradable prices which largely reflect offshore factors increased by 0.3% for the quarter, seeing the annual pace accelerate modestly to a still-weak 1.2%.
Core inflation, excluding food, household energy and vehicle fuels, rose 0.4% on the quarter and 2.7% over the year, up from 2.6% in Q1 but still within target. The RBNZ’s sectoral factor model, its preferred measure of underlying inflation, will be released at 3pm Wellington (1pm Sydney).
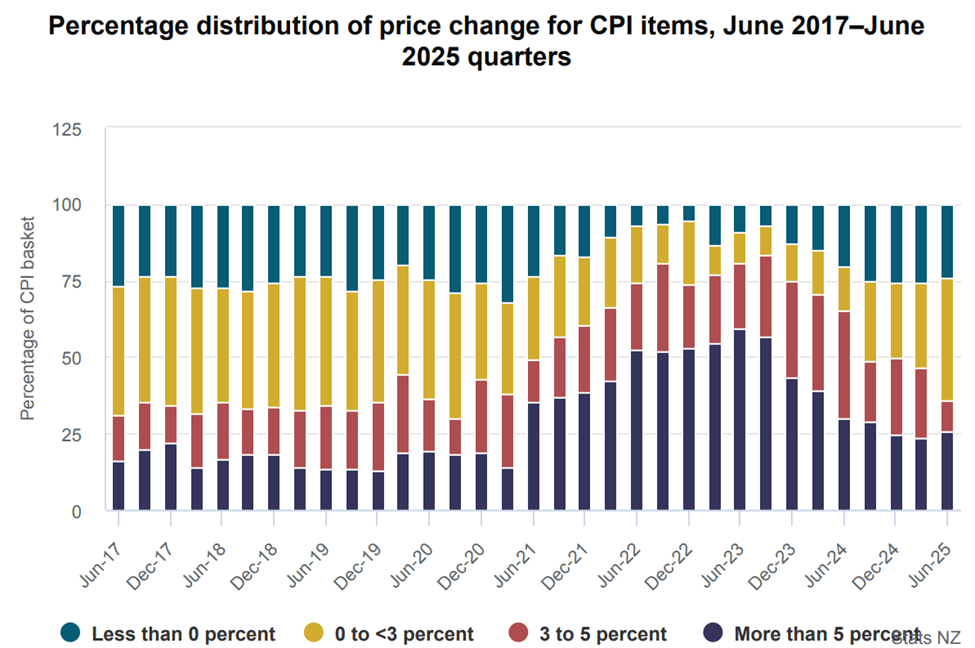
Adding to confidence that inflationary pressures remain contained despite 225 basis points worth of rate cuts from the RBNZ already this cycle, the proportion of the CPI basket with price increases of 3% or less increased to 64.3% in Q2, the highest proportion since Q3 2020.
Source: StatsNZ
Keeping RBNZ Rate Cuts in Play
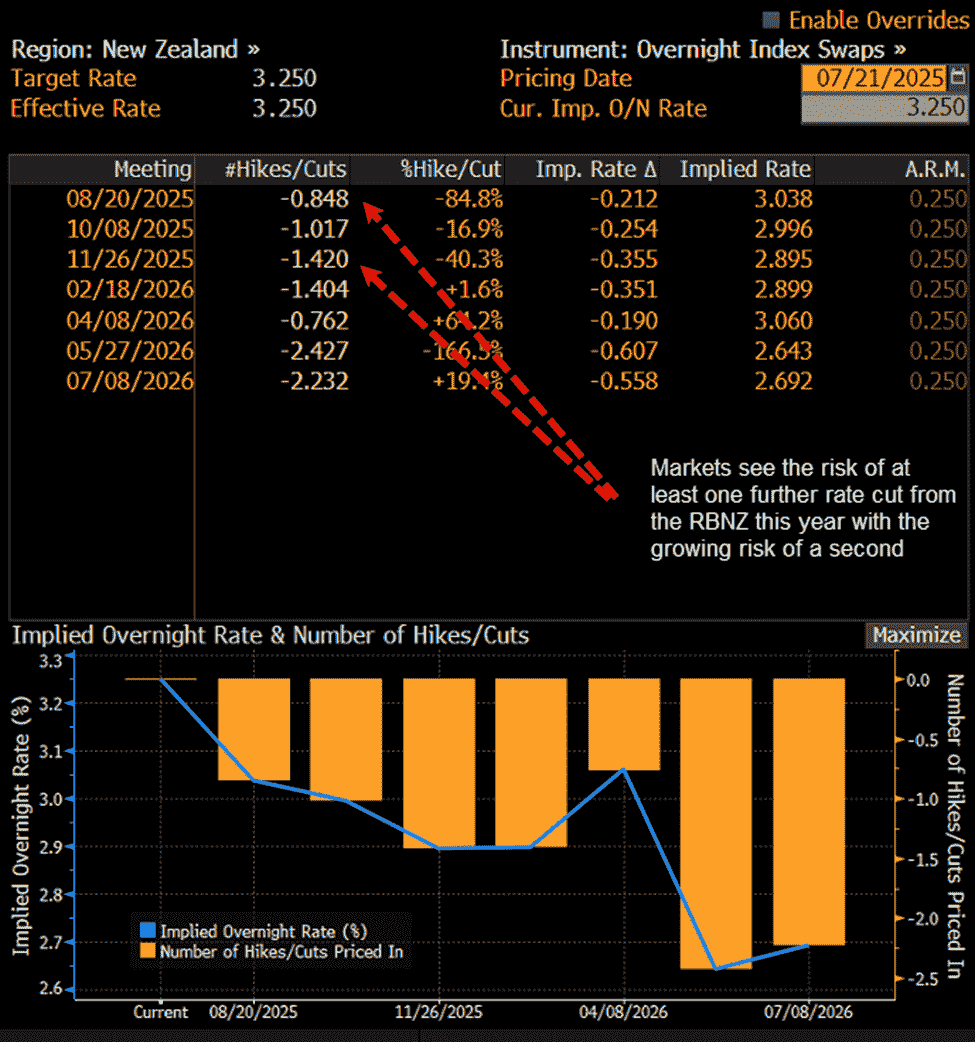
Following the inflation report, swaps markets put the probability of the RBNZ reducing the cash rate by a further 25 basis points to 3% on August 20 at 85%. Looking further out, a full cut it priced by the bank’s October meeting with a 42% probability seen of a second 25-pointed by year-end.
Source: Bloomberg
With markets paring expectations for multiple rate cuts from the Federal Reserve this year, it’s combined with the slightly softer Kiwi inflation report to push NZD/USD weaker in early Asian trade on Monday.
NZD/USD Remains in Downtrend
Source: TradingView
For the moment, NZD/USD remains a sell-on-rallies play, sitting in an established downtrend with momentum indicators like RSI (14) and MACD trending lower and sitting in negative territory, favouring a bearish bias.
Resistance kicks in at .5980 and again at the 50-day moving average located some 16 pips above. On the downside, bids have been noted recently ahead of support at .5900. If they were to be overrun, .5850 and the 200-day moving average would be the next two downside levels of note.
AUD/NZD Key Reversal?
Source: TradingView
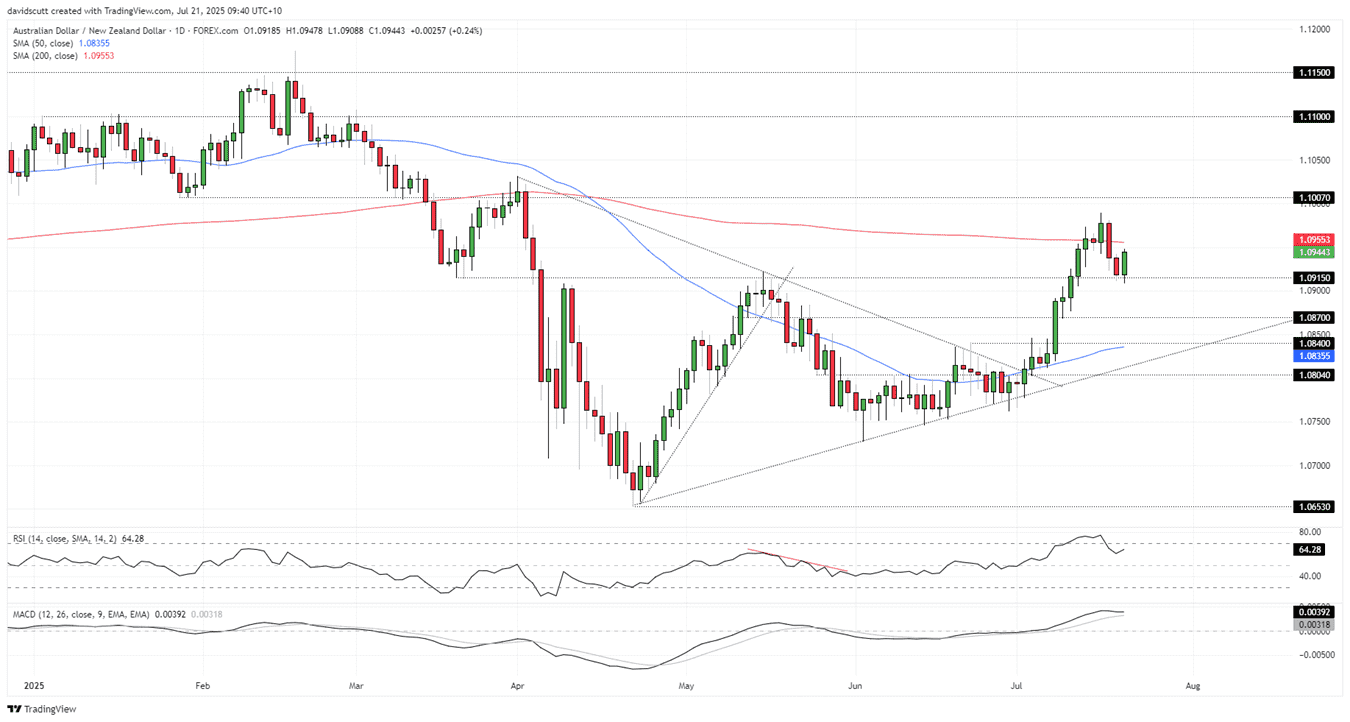
Looking briefly at AUD/NZD, the pair found buying support late last week at 1.0915 and again in early trade on Monday, with the inflation report helping to spark a reversal back above Friday’s opening level. Things could quickly change, but the daily candle will print as a key bullish reversal if it closes at or above these levels, pointing to the potential for further gains ahead should it eventuate.
Levels to watch on the topside include the 200-day moving average, Wednesday’s high around 1.0990, along with horizontal resistance at 1.1007. Benearth 1.0915, 1.0870 and 1.0840 are levels of note.
From a directional perspective, a bullish bias remains favoured with MACD and RSI (14) remaining in positive territory even with the moderation in topside momentum seen in recent days.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.