


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
Share this:
- US front-end rates remain USD/JPY’s dominant fundamental driver
- Intervention risk appears to be building around 158
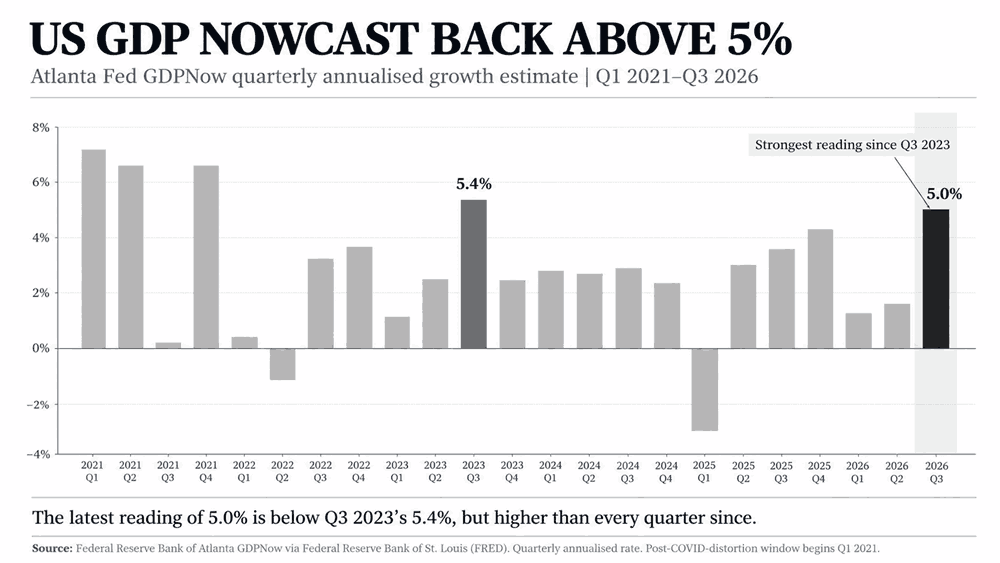
- GDPNow above 5% underlines continued US economic strength
- Friday payrolls could meaningfully challenge hawkish Fed pricing
Fundamentals suggest USD/JPY should be pushing higher, with clear evidence that the US economy continues to outperform other major developed nations, including Japan, keeping upward pressure on yields and reinforcing expectations for further Fed tightening.
However, that force is being countered by the ongoing threat of intervention, not only from Japanese authorities but also the US, with recent behaviour suggesting 160 is no longer the line in the sand for elevated intervention risk, but potentially somewhere lower.
Strip away that threat, though, and the message from short- and medium-term correlations remains clear: the front end of the US rates curve remains the dominant factor influencing the pair’s movements.
That puts the emphasis firmly on Friday’s US non-farm payrolls report for September. The week ahead leaves its biggest event until last.
Has the intervention threshold shifted lower?
Before we look at the key fundamental factors to consider this week, it’s worth starting with the apparent threat of renewed intervention activity in USD/JPY.
As many FX watchers would already know, for a long period moves towards and above 160 were often deemed the line in the sand for Japanese policymakers, typically coinciding with a torrent of warnings, rate checks and, if ignored, actual intervention.
But the behaviour over the past two Fridays suggests that tolerance threshold may have shifted lower.
Last Friday, reports of a rate check helped trigger a sharp reversal after USD/JPY moved above 158. Then this Friday, another push above 158 was met by fresh concern, with Finance Minister Satsuki Katayama revealing that Donald Trump had raised concerns about yen weakness directly with Prime Minister Sanae Takaichi during their meeting on the sidelines of the UN General Assembly in New York.
It’s too early to say 158 is the new line in the sand, but recent behaviour suggests intervention risk is becoming more acute at and around this level, making that a key consideration for traders in the week ahead.
US rates remain the dominant influence
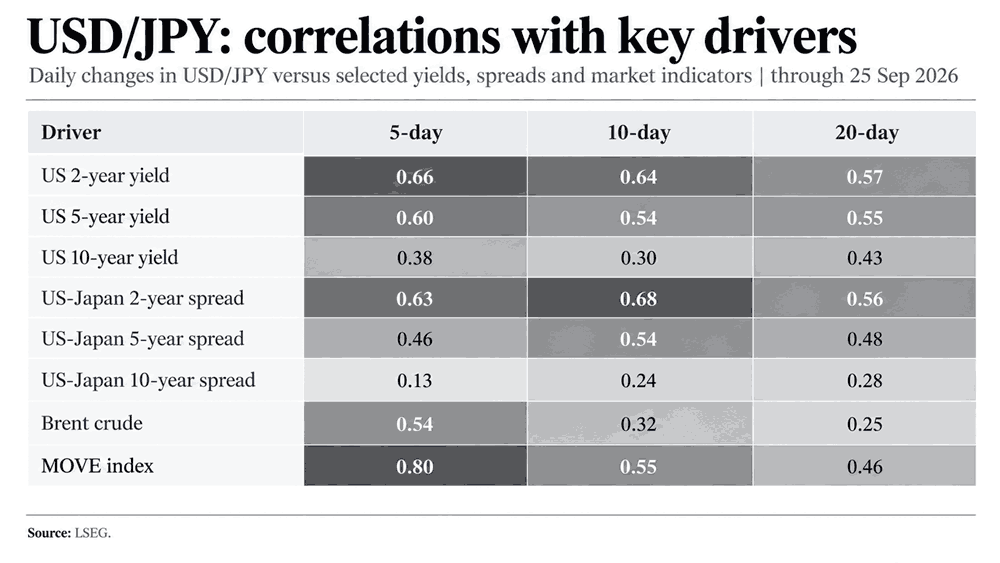
Looking at the correlation matrix below, the strongest relationships continue to sit with the US 2-year yield and the US-Japan 2-year spread, which remain positively correlated with USD/JPY across the five, 10 and 20-day windows.
Source: LSEG
The relationship with longer-dated yields is weaker, while Japanese yields on their own reveal little to no influence over the pair. The strengthening relationship with the MOVE index is also interesting. Similar to the S&P 500 VIX, MOVE measures implied volatility in the US Treasury market over the month ahead. Even so, there’s not enough consistency there yet to suggest the outlook for Treasury volatility is really driving USD/JPY.
The biggest event comes last
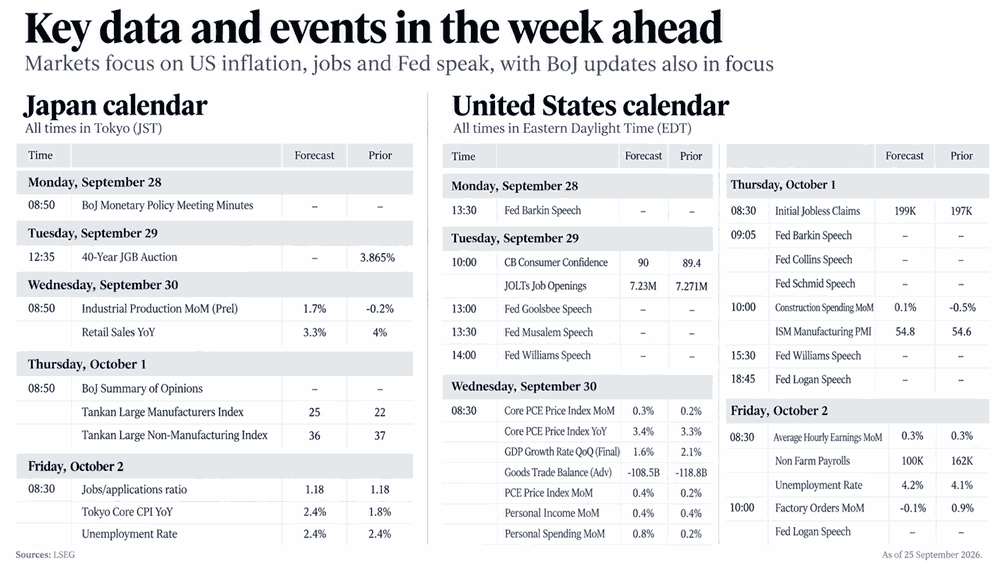
The calendar below looks at the key events in Japan and the United States over the coming days.
Source: LSEG
While we get a smattering of BOJ-related information in Japan, along with the Tokyo CPI report for September, which arrives around three weeks before the national figure and has historically had a strong relationship with it, the real focus this week is the updated report card on the US labour market and whether it is enough to shift what has been a concerted and uniformly hawkish message from Fed officials since the September FOMC meeting.
We also get the Fed’s preferred underlying inflation measure in the core PCE deflator, final Q2 GDP, along with incomes and spending data. But the brutally honest assessment is that Friday’s payrolls report is the event most likely to meaningfully shift Fed pricing.
While it is the price stability side of the Fed’s dual mandate that the FOMC is prioritising right now, any signs of weakness in the labour market, which have not been evident to this point in more timely indicators such as jobless claims, could begin to skew the committee’s reaction function more symmetrically towards both sides of its mandate.
To do that, though, it would likely require a sizeable payrolls undershoot alongside upward pressure on unemployment, particularly if that wasn’t accompanied by a decent lift in labour force participation.
Elsewhere, JOLTS job openings and ISM manufacturing can generate volatility on their day, although both are likely to play second fiddle this week.
US economy remains in beast mode
Underlining why it would likely take a horrendously bad payrolls report to skew the committee’s reaction function, recent US economic data has remained exceptionally strong.
Whether tracked by Citi’s Economic Surprise Index or the Atlanta Fed GDPNow model below, the US economy is in beast mode right now.
Source: FRED
As things currently stand, GDPNow is pointing to a seasonally adjusted annualised growth pace of more than 5% in the third quarter, which, if realised, would mark the strongest reading since Q3 2023.
Clearly, it’s a nowcast model and we still don’t have all the information for the quarter, which isn’t even finished yet. But it just shows the US economy continues to outperform expectations despite high inflation and far higher interest rates, with nominal growth remaining strong.
Source: LSEG
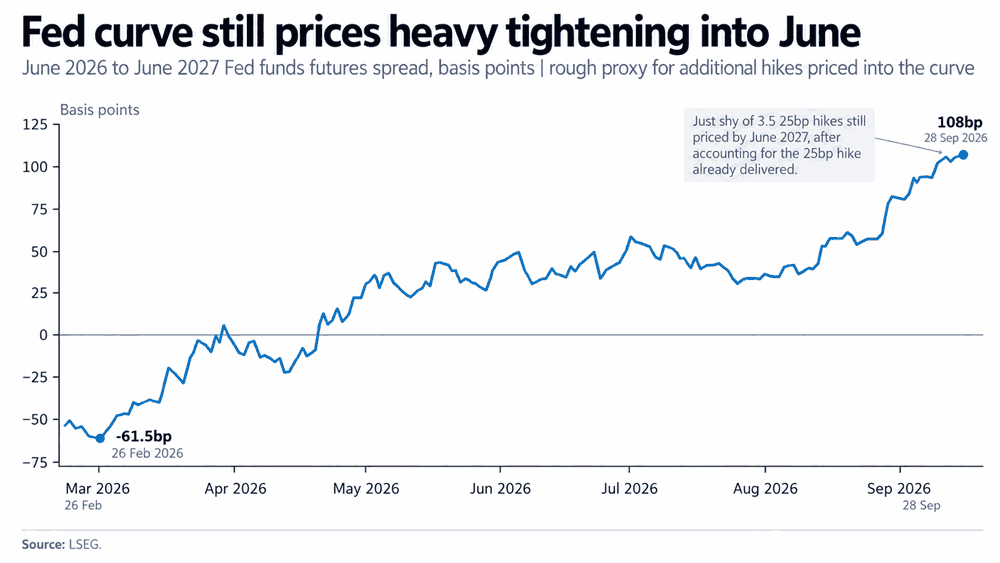
As such, it comes as little surprise that markets still have more than three full rate hikes priced through to the middle of next year, continuing to provide the front-end rate support that remains supportive of upside in USD/JPY.
Intervention clouds the technical picture
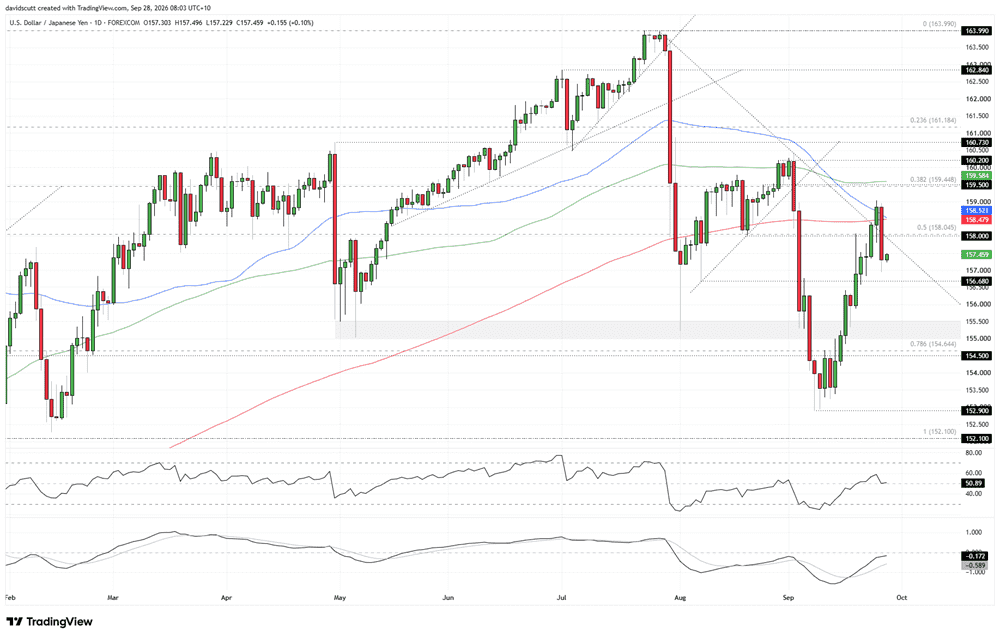
Last Friday’s abrupt reversal is clearly visible on the daily chart, with USD/JPY sliding sharply after briefly tagging 159 on Thursday, having reclaimed both the 50- and 200-day moving averages in the process.
The subsequent move saw the pair fall back beneath 158, a level that has acted as both support and resistance for periods this year and also coincides with the 50% retracement of the 2026 low-high move.
Source: TradingView
Given the ongoing intervention threat, technical signals may not carry as much weight as they normally would. Even so, stepping back, USD/JPY continues to post lower highs and lower lows since late July, while the pair is now back beneath key medium- and long-term moving averages. From a medium-term perspective, that keeps selling into strength as the preferred approach.
Near term, the oscillators remain broadly neutral in their messaging, leaving scope for two-way setups to be considered if the fundamental picture warrants it and the immediate intervention threat is perceived to have lessened.
Below where the pair now trades, 157 is the immediate level to watch, having bounced from there on Friday, followed by 156.68 and then a more pronounced support zone between 155.50 and 155.00.
Overhead, 158 remains the first major hurdle for bulls, followed by the 200-day moving average and 159, where the pair stalled last Thursday. Above there, a more pronounced resistance zone sits around 159.50, where the 38.2% retracement of the 2026 low-high and the 100-day moving average are clustered together.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Yen Weakness Fuels USD/JPY and EUR/JPY Breakouts Ahead of Midterms
Yen weakness drives USD/JPY and EUR/JPY higher despite intervention risks, with traders eyeing 160 and 180 as US midterm results emerge.
US Dollar Short-term Outlook: USD Rally on the Line as Midterms, NFP Loom 11 3 2026
DXY is testing pivotal support, with the weekly range breakout likely to determine the next major leg of the trend as key event risk unfolds.

USD/JPY Analysis: Rising U.S. Yields Leave the Yen on the Defensive
As the first week of November progresses, renewed weakness in the Japanese yen is once again becoming evident in the short term. This dynamic can be seen in the recent performance of USD/JPY, which has posted two consecutive bullish sessions and gained more than 0.7%, reflecting a return of buying interest in the dollar while the yen continues to lose momentum.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.