




Stocks Head Lower Despite UK Unemployment Rate Holding
European bourses are set to open on the back foot as US – Chinese tensions, in addition to worrying trends surrounding the Chinese consumer, drag on market sentiment. Negativity in the market is overshadowing better than expected Chinese economic growth and better than forecast UK jobs data.
Share this:

Asian markets traded lower and European bourses are set to open on the back foot as US – Chinese tensions, in addition to worrying trends surrounding the Chinese consumer, drag on market sentiment. Negativity in the market is overshadowing better than expected Chinese economic growth and better than forecast UK jobs data.
Chinese GDP rebounded strongly in the second quarter, +3.2% from Q1’s record contraction. This was ahead of the +2.5% forecast. However, more worryingly retail sales fell for a 5th straight month. The data highlights the caution being exercised by consumers, who are still choosing to avoid places of possible large crowds and who are reining in their spending over concerns of what lies ahead.
China was the first nation to suffer from covid-19 and go into lockdown. They are ahead of the West on the recovery curve. However, the cautious consumer could well be a signal of what we can expect across the UK or the US and ties in with BoE policy maker Silvana Tenreyo’s forecast that wary consumers and unemployment could prevent a full economic recovery.
UK unemployment remains at 3.9%
For now, Tenreyo’s concerns are not being played out in the labour market. Jobs data continues to defy the reality of the deepest economic downturn in 300 years. Unemployment remained steady at 3.9%, the number of people claiming unemployment benefits actually declined by 28,000 rather than increasing by 250,000 and average earnings excluding bonuses jumped +0.7%.
For now, Tenreyo’s concerns are not being played out in the labour market. Jobs data continues to defy the reality of the deepest economic downturn in 300 years. Unemployment remained steady at 3.9%, the number of people claiming unemployment benefits actually declined by 28,000 rather than increasing by 250,000 and average earnings excluding bonuses jumped +0.7%.
Even with the governments job retention scheme clouding the true impact of the coronavirus crisis on the labour market, these are still robust numbers which defy the reality that the UK economy is 25% smaller now compared to February.
Despite today’s surprise, there is little doubt that the worst is yet to come for the labour market. The support from the government has delayed the impact of the crisis on the labour market, which will start showing through as the furlough scheme tapers. Rishi Sunak will be hoping that the tapering happens in conjunction with rising demand which could save the jobs market from any harsh blows.
But rest assured the unemployment level will rise going forward. The Pound hasn’t been fooled, and GBP/USD trades -0.25%, whilst sterling dropped -0.1% versus the Euro.
US retail sales
US retail sales later today will be watched closely. Expectations are for a 5% mom in June, after a 17.7% surge in May. There is a good chance that we are still seeing pent up demand being released here. However, any weakness particularly after China’s data could deeply unsettle investors.
US retail sales later today will be watched closely. Expectations are for a 5% mom in June, after a 17.7% surge in May. There is a good chance that we are still seeing pent up demand being released here. However, any weakness particularly after China’s data could deeply unsettle investors.
Risk appetite has also taken a hit as US – Chinese tensions have notched up a level as the White House threatens more sanctions on Chinese tech firms, with TikTok and WeChat now in the firing line.
ECB
The Euro is trading on the back foot versus the safe haven USD but advancing versus GBP as investors look ahead to the ECB monetary policy announcement. The ECB are not expected to move on policy after increasing the Pandemic Emergency Purchase Programme by a more than expected €600 billion last month and amid tentative signs of economic recovery in the region. We can expect the ECB to return to the familiar wait and see mode.
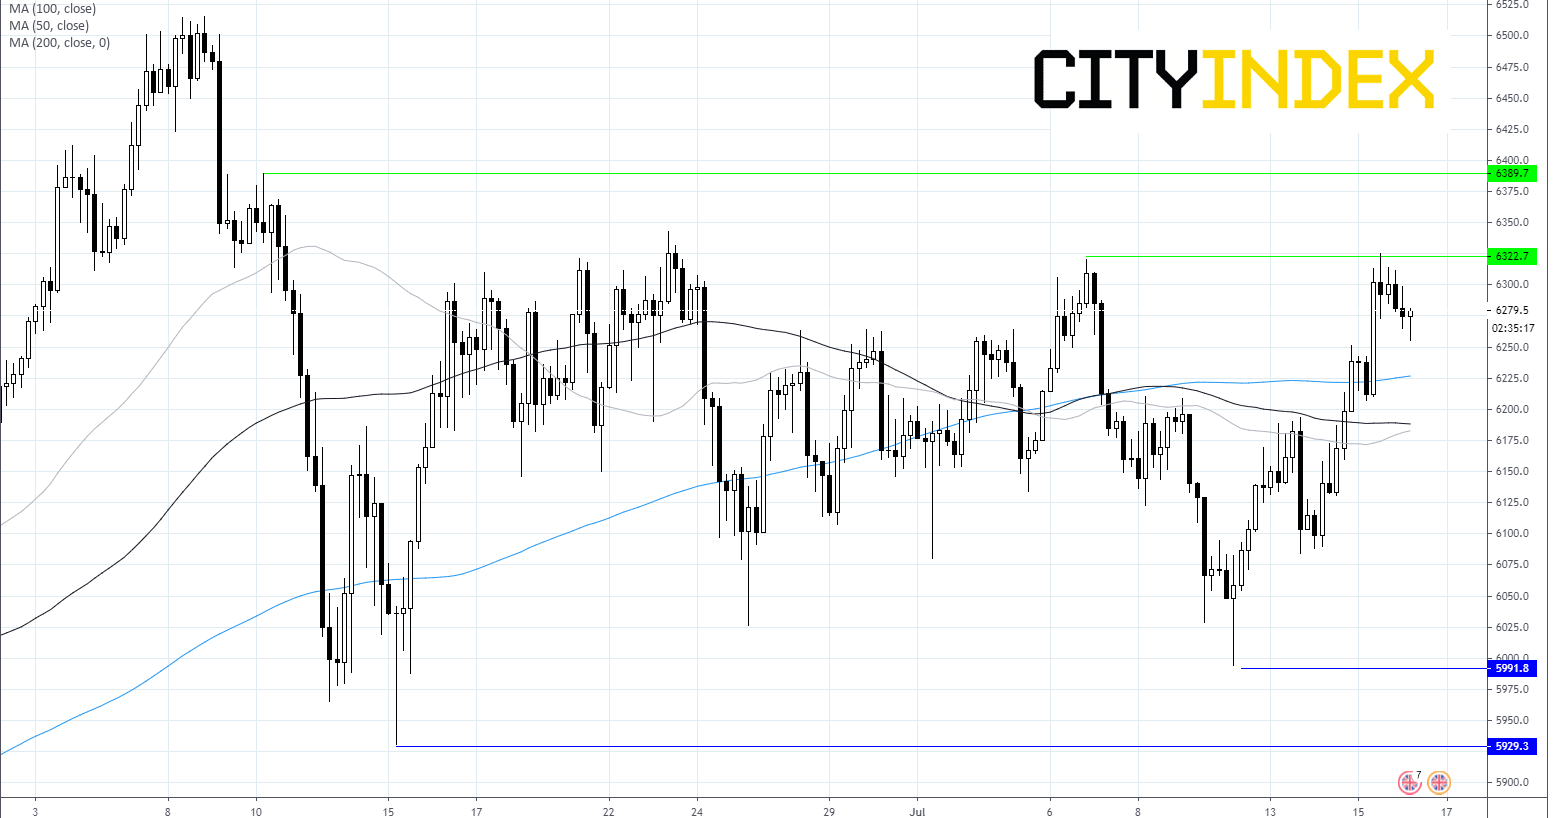
FTSE Chart
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD, FTSE 100 Forecast: Two trades to watch 1507
EUR/USD rises after weaker US CPI, PPI up next. FTSE 100 falls as weak China GDP data hits miners.

FTSE 100, USD/JPY Forecast: Two trades to watch
FTSE eases modestly despite inflation unexpectedly holding steady. USD/JPY drifts lower ahead of the FOMC rate decision.
EUR/USD, FTSE 100 Forecast: Two trades to watch 21-05-26
EUR/USD slips below 1.16 as weak eurozone data weighs on sentiment. FTSE 100 slips as oil prices rebound and caution returns.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.