





Traders Wary as Super Contango Drives WTI Toward 1000
This is the biggest percentage difference between the front two oil contracts in over 40 years!
Share this:

Markets have experienced a tremendous shock as traders try to navigate the fallout of a global pandemic leading to a synchronized halt to commerce worldwide, at least most of the price moves have been generally orderly, if volatile. Beyond some issues with certain illiquid ETFs trading away from their underlying asset values in the peak of the mid-March panic, financial markets have largely fulfilled their role of matching buyers and sellers and facilitating the exchange of assets for cash at a reasonable price over the last couple of months.
While the above is generally true, today’s price action in oil is certainly raising some eyebrows among even the most experienced traders. Using West Texas Intermediate as an example, the May futures contract, which expires tomorrow, is changing hands at just around $11.00 as of writing, down fully 40% today alone! Many less common forms of oil, including Bakken UHC, Alaska North Slope, Edmonton C5 condensate, and Edmonton mixed sweet, are all trading below $5.00 a barrel.
This market distortion is due to a variety of factors, including demand destruction, oversupply, pipeline delays, storage capacity, and popular oil ETFs rolling forward to next month’s June contract, making the May contract far more illiquid. By contrast, the June WTI contract is trading at a (slightly) more reasonable $26.50. This situation, where prices for future delivery are trading above the current spot price, is called contango and is relatively rare. As the chart below shows, this is the biggest percentage difference between the front two oil contracts in over 40 years:
Contango, or “Super Contango” as the case may be, incentivizes traders to take delivery of the physical oil and hold it, thereby capitalizing on the implied appreciation. Concerns about commercial and industrial oil storage capacity have exacerbated the current contango structure, but in the long run, the futures curve term structure is likely to normalize, implying potential appreciation for oil from here once the current temporary issues are resolved.
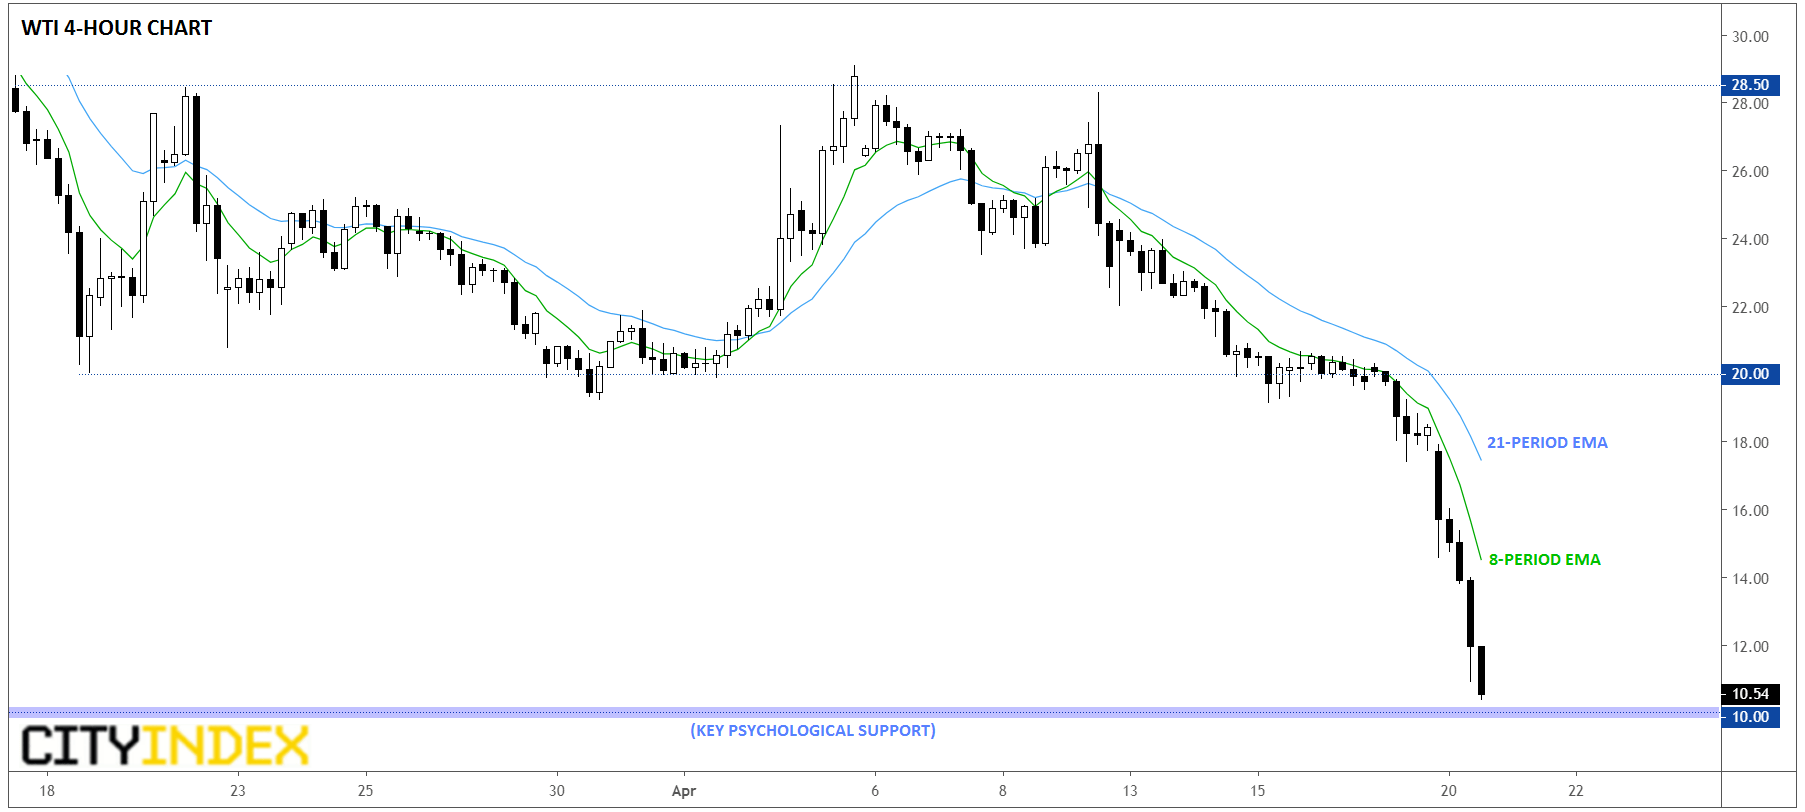
With prices probing 30+ year lows, there’s obviously little in the way of recent support/resistance on a technical basis. That said, traders may watch the $10.00 level as a key area of psychological support over the next couple of days, rationalizing that oil should not be trading a less than a “tenner,” no matter how severe the current market conditions are:
Source: TradingView, GAIN Capital
Even if you don’t trade oil, it’s worth keeping an eye on the market for this critical commodity this week, as further price distortions could hint at stress in the broader financial markets, even if sentiment has stabilized from March’s “peak fear” trading conditions.
Markets have experienced a tremendous shock as traders try to navigate the fallout of a global pandemic leading to a synchronized halt to commerce worldwide, at least most of the price moves have been generally orderly, if volatile. Beyond some issues with certain illiquid ETFs trading away from their underlying asset values in the peak of the mid-March panic, financial markets have largely fulfilled their role of matching buyers and sellers and facilitating the exchange of assets for cash at a reasonable price over the last couple of months.
While the above is generally true, today’s price action in oil is certainly raising some eyebrows among even the most experienced traders. Using West Texas Intermediate as an example, the May futures contract, which expires tomorrow, is changing hands at just around $11.00 as of writing, down fully 40% today alone! Many less common forms of oil, including Bakken UHC, Alaska North Slope, Edmonton C5 condensate, and Edmonton mixed sweet, are all trading below $5.00 a barrel.
This market distortion is due to a variety of factors, including demand destruction, oversupply, pipeline delays, storage capacity, and popular oil ETFs rolling forward to next month’s June contract, making the May contract far more illiquid. By contrast, the June WTI contract is trading at a (slightly) more reasonable $26.50. This situation, where prices for future delivery are trading above the current spot price, is called contango and is relatively rare. As the chart below shows, this is the biggest percentage difference between the front two oil contracts in over 40 years:
Contango, or “Super Contango” as the case may be, incentivizes traders to take delivery of the physical oil and hold it, thereby capitalizing on the implied appreciation. Concerns about commercial and industrial oil storage capacity have exacerbated the current contango structure, but in the long run, the futures curve term structure is likely to normalize, implying potential appreciation for oil from here once the current temporary issues are resolved.
With prices probing 30+ year lows, there’s obviously little in the way of recent support/resistance on a technical basis. That said, traders may watch the $10.00 level as a key area of psychological support over the next couple of days, rationalizing that oil should not be trading a less than a “tenner,” no matter how severe the current market conditions are:
Source: TradingView, GAIN Capital
Even if you don’t trade oil, it’s worth keeping an eye on the market for this critical commodity this week, as further price distortions could hint at stress in the broader financial markets, even if sentiment has stabilized from March’s “peak fear” trading conditions.




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Crude Oil Analysis: Geopolitical Risk Continues to Drive the WTI Barrel Higher
During recent trading sessions, a new wave of buying momentum has continued to gain relevance around WTI crude oil price action. Over the last three trading sessions, the market has maintained a bullish streak and is now up more than 5.5%, highlighting significant buying pressure in the short term.

Crude Oil Forecast WTI Prices Come Under Pressure as Middle East Risks Ease
Over the last two trading sessions, WTI crude oil has once again displayed a notable bearish bias, with prices falling nearly 6%. Part of this renewed selling pressure has been driven by recent developments in the Middle East, which have helped temporarily ease the geopolitical tensions that had supported the oil risk premium in previous weeks.
Crude Oil Analysis WTI barrel remains weak after OPEC+ announcements
Crude oil continues to face difficult trading sessions in the short term. Over the last 5 trading sessions on average, WTI remains down close to -3.5%, with consistent movements below the 70-dollar area. This continues to highlight a selling bias that has remained in place for several weeks.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.