







US Data Dump
The US has front loaded all the month end data because of the Thanksgiving holiday
Share this:

The US has front loaded all the month end data to today because of the upcoming Thanksgiving holiday and the half day session for equities on Friday. The most important data released today was US GDP (Preliminary) for Q2, Chicago PMI for November, Pending Home Sales (MoM) for October and the Core PCE Price Index (YoY), which is one of the Fed’s favorite measures of inflation.
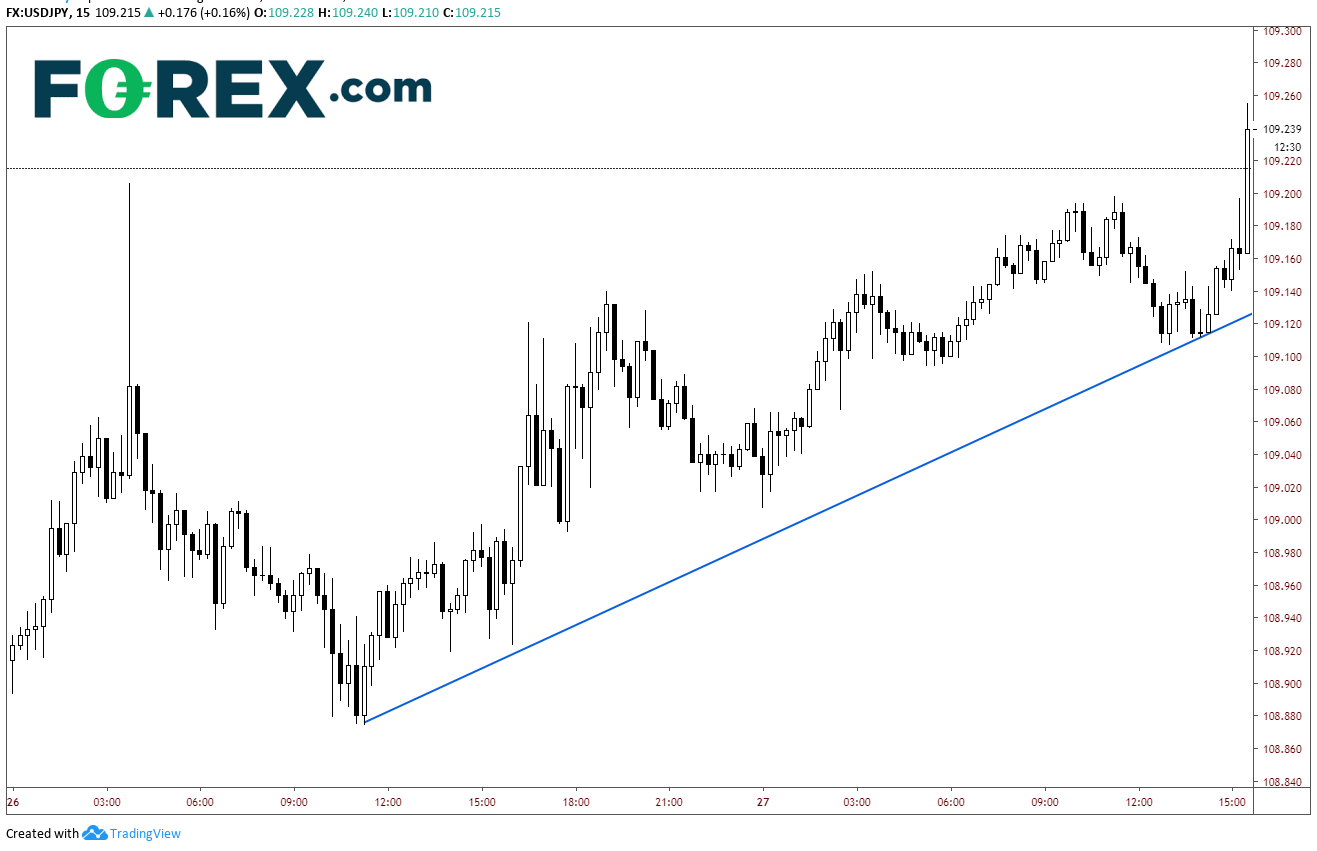
GDP for Q3 (QoQ) was released at 2.1% vs 1.9% expected, however this is the second look at the data, and it is looking at Q3. We are half way through Q4, therefore price didn’t move a great deal on the release. Immediately after the release, USD/JPY spiked 10 pips from 109.15 to 109.25, while the S&P 500 was little changed.
Source: Tradingview, City Index
Chicago PMI was released an hour and fifteen minutes later. The number shows the first solid look at manufacturing data for the month of November. The reading of 43.2 for October was the lowest reading since December 2015. This month’s reading was 46.3 vs 47 expected. Although a touch lower than expected, again prices were close to unchanged upon its release.
Fifteen minutes after that, the headline PCE Price Index (MoM) was 0.2% vs 0.2% expected. However, the Core PCE Price Index (YoY) was 1.6% vs 1.7% expected. The kicker in today’s data was the Pending Home Sales (MoM) for October. +0.2% was expected. The headline number was -1.7%! Upon the release, the US Dollar index fell from 98.44 down to 98.36.
Source: Tradingview, City Index
Watch to see if the US Dollar selling continues. Notice the failure so far in DXY to take out recent highs and the 50% retracement from the October 1st highs to the October 18th lows. If price trades back to 98.20, it will fill the overnight gap and be extremely bearish heading into the holiday. However, if price can hold on to it’s gains and move higher, the DXY will be in good shape heading in to shortened trading day on Friday and into the weekend.
Source: Tradingview, City Index
Over the next few hours, things should begin to slow down as people begin leaving early for the US Thanksgiving holiday. There may be some squaring up on the books as the US heads into a (sort of) long holiday weekend.
The US has front loaded all the month end data to today because of the upcoming Thanksgiving holiday and the half day session for equities on Friday. The most important data released today was US GDP (Preliminary) for Q2, Chicago PMI for November, Pending Home Sales (MoM) for October and the Core PCE Price Index (YoY), which is one of the Fed’s favorite measures of inflation.
GDP for Q3 (QoQ) was released at 2.1% vs 1.9% expected, however this is the second look at the data, and it is looking at Q3. We are half way through Q4, therefore price didn’t move a great deal on the release. Immediately after the release, USD/JPY spiked 10 pips from 109.15 to 109.25, while the S&P 500 was little changed.
Source: Tradingview, FOREX.com
Chicago PMI was released an hour and fifteen minutes later. The number shows the first solid look at manufacturing data for the month of November. The reading of 43.2 for October was the lowest reading since December 2015. This month’s reading was 46.3 vs 47 expected. Although a touch lower than expected, again prices were close to unchanged upon its release.
Fifteen minutes after that, the headline PCE Price Index (MoM) was 0.2% vs 0.2% expected. However, the Core PCE Price Index (YoY) was 1.6% vs 1.7% expected. The kicker in today’s data was the Pending Home Sales (MoM) for October. +0.2% was expected. The headline number was -1.7%! Upon the release, the US Dollar index fell from 98.44 down to 98.36.
Source: Tradingview, FOREX.com
Watch to see if the US Dollar selling continues. Notice the failure so far in DXY to take out recent highs and the 50% retracement from the October 1st highs to the October 18th lows. If price trades back to 98.20, it will fill the overnight gap and be extremely bearish heading into the holiday. However, if price can hold on to it’s gains and move higher, the DXY will be in good shape heading in to shortened trading day on Friday and into the weekend.
Source: Tradingview, FOREX.com
Over the next few hours, things should begin to slow down as people begin leaving early for the US Thanksgiving holiday. There may be some squaring up on the books as the US heads into a (sort of) long holiday weekend.


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


USD/JPY outlook: Hawkish Fed recalibration pressures the yen
Stronger US growth momentum and rising Treasury yields are keeping USD/JPY pointed higher, even as Japanese policymakers try to limit the pressure building across domestic markets.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.