


US open: Stocks rise as GDP & jobless claims beat forecasts
Stocks rise, but come off session highs after US GDP is upwardly revised to -0.7% and jobless claims unexpectedly fall. Attention now turns to the Fed's gathering at the Jackson Hole Symposium.
Share this:

US futures
Dow futures +0.12% at 33025
S&P futures +0.44% at 4160
Nasdaq futures +0.5% at 12999
In Europe
FTSE +0.13% at 7480
Dax +0.18% at 13256
Euro Stoxx +0.09% at 3670
GDP improves, but still in recession
US stocks are heading higher for a second day as investors digested the latest data and looked toward the Federal Reserve’s annual Jackson Hole Symposium.
US GDP was upwardly revised to -0.6% annualized in Q2 up from -0.9% in the initial estimate and ahead of the -0.8% forecast. Although this still shows that the US economy was in a technical recession.
Meanwhile, US jobless claims unexpectedly fell to 243k down from 250k in a sign that the US labour market is holding up despite the US economy being in a technical recession and despite rising inflation.
The central bankers’ gathering kicks off later today and while some clips will be coming through to the market the main focus in on Jerome Powell’s speech tomorrow, which comes just an hour and a half after the latest PCE inflation data.
Powell’s speech will be watched closely and will likely set the tone in the markets until the next FOMC. Heading not the speech inflation is still over 4 times the Fed’s target level so we can expect a reiteration of the Fed’s commitment to cutting inflation. The Fed’s job is clearly not done yet. Expectations of a dovish pivot have been priced out earlier in the week. The risk could be that the Fed is prepared to go bigger for longer.
In corporate news:
Peloton falls 16% pre-market after the exercise bike manufacturer reported a larger than expected net loss in Q4. Rising costs, slow progress in the turnaround and falling demand are hitting the stock.
Tesla rises pre-market after the 3-for-1 stock split. This is the second time that the EV maker has split its stock in 2 years.
Nvidia reports a 19% QoQ drop in revenue mainly due to a slowdown in demand for gaming chips.
Where next for the S&P50?
The S&P500 ran into resistance at 4300 the 200 sma before rebounding lower and finding support at 4100. The price trades caught between the 100 and 200 sma and the RSI is relatively neutral. Sellers will be looking for a move southwards of 4100 horizontal support and 4070 the 100 sma. Buyers will look for a move over 4300 to extend the upside recovery and create a higher high.

FX markets – USD falls, AUD jumps
The USD is falling as risk sentiment continues to improve. The USD had rallied to 109.27 in the previous session matching its 20-year high touched at the start of July as hawkish Fed bets built ahead of the Jackson Hole Symposium.
EUR/USD is rising boosted by better-than-expected data from Germany. German GDP was upwardly revised to 0.1% QoQ in Q2, from 0%. Meanwhile, the German IFO business climate was also better than forecast at 88.5, down from 88.7. However, this is still only marginally above a 2-year low. The ECB minutes didn’t bring anything new to the table.
AUD/USD is outperforming its major peers, boosted by the upbeat market mood and announcement of a huge stimulus plan in China, equating to around 1% of GDP to support the slowing economy.
AUD/USD 1% at 0.6980
EUR/USD +0.23% at 0.9935
Oil holds steady at $100.00
Oil prices are holding steady after strong gains across the past two sessions. On the one hand, oil prices are being supported by the prospect of OPEC cutting oil supply. However, this is being offset by the possibility of Iranian oil returning to the market should the Iran nuclear agreement be revived.
Earlier in the week the Saudi Energy Minister surprised the market by suggesting that a production cut could help stabilize the market. His comments lifted oil prices to a three-week high and reduced the odds of oil prices slipping below $90 in the near term.
A larger than expected draw on crude stock piles is also supporting the price. According to the latest EIA data, stockpiles declined by 3.3 million barrels.
WTI crude trades -0.35% at $92.78
Brent trades -0.1% at $100.35
Looking ahead
15:00 Jackson Hole Symposium
US futures
Dow futures +0.12% at 33025
S&P futures +0.44% at 4160
Nasdaq futures +0.5% at 12999
In Europe
FTSE +0.13% at 7480
Dax +0.18% at 13256
Euro Stoxx +0.09% at 3670
Learn more about trading indices
GDP improves, but still in recession
US stocks are heading higher for a second day as investors digested the latest data and looked toward the Federal Reserve’s annual Jackson Hole Symposium.
US GDP was upwardly revised to -0.6% annualized in Q2 up from -0.9% in the initial estimate and ahead of the -0.8% forecast. Although this still shows that the US economy was in a technical recession.
Meanwhile, US jobless claims unexpectedly fell to 243k down from 250k in a sign that the US labour market is holding up despite the US economy being in a technical recession and despite rising inflation.
The central bankers’ gathering kicks off later today and while some clips will be coming through to the market the main focus in on Jerome Powell’s speech tomorrow, which comes just an hour and a half after the latest PCE inflation data.
Powell’s speech will be watched closely and will likely set the tone in the markets until the next FOMC. Heading not the speech inflation is still over 4 times the Fed’s target level so we can expect a reiteration of the Fed’s commitment to cutting inflation. The Fed’s job is clearly not done yet. Expectations of a dovish pivot have been priced out earlier in the week. The risk could be that the Fed is prepared to go bigger for longer.
In corporate news:
Peloton falls 16% pre-market after the exercise bike manufacturer reported a larger than expected net loss in Q4. Rising costs, slow progress in the turnaround and falling demand are hitting the stock.
Tesla rises pre-market after the 3-for-1 stock split. This is the second time that the EV maker has split its stock in 2 years.
Nvidia reports a 19% QoQ drop in revenue mainly due to a slowdown in demand for gaming chips.
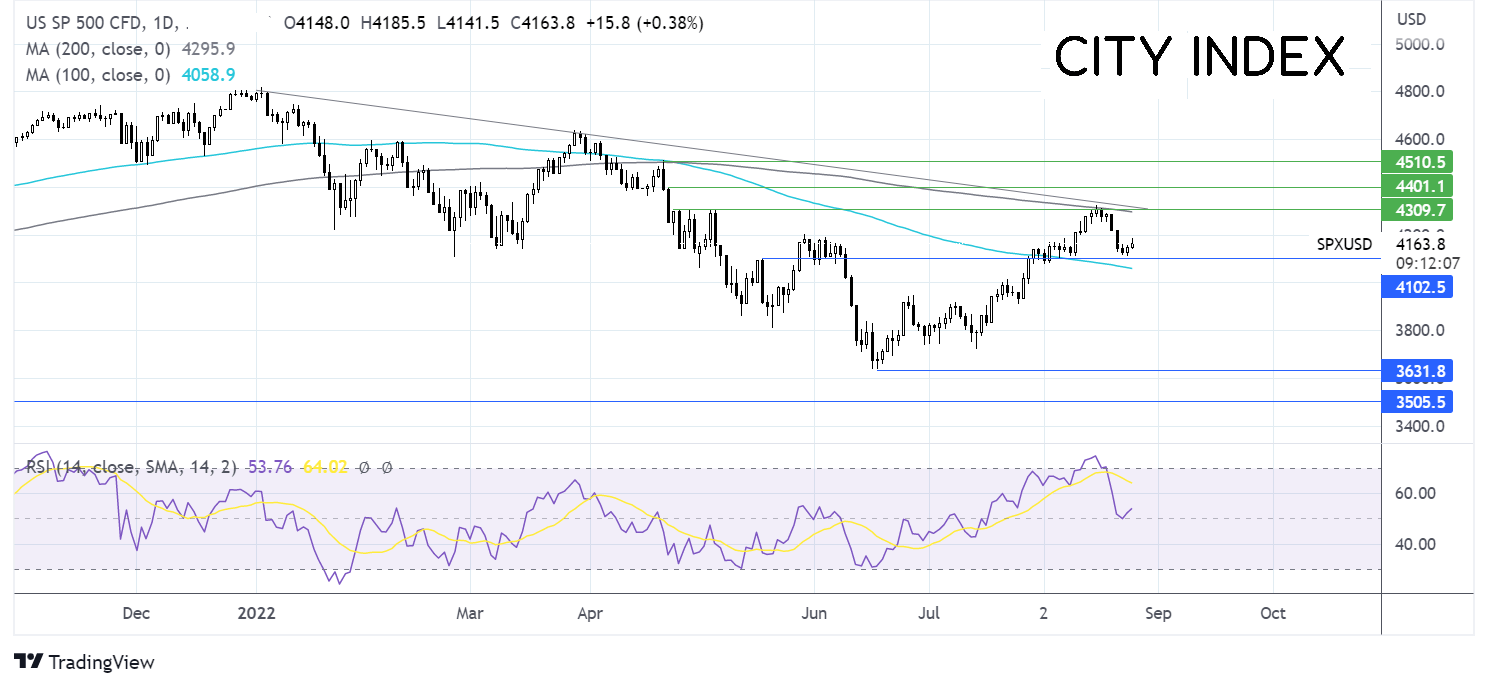
Where next for the S&P500?
The S&P500 ran into resistance at 4300 the 200 sma before rebounding lower and finding support at 4100. The price trades caught between the 100 and 200 sma and the RSI is relatively neutral. Sellers will be looking for a move southwards of 4100 horizontal support and 4070 the 100 sma. Buyers will look for a move over 4300 to extend the upside recovery and create a higher high.
FX markets – USD falls, AUD jumps
The USD is falling as risk sentiment continues to improve. The USD had rallied to 109.27 in the previous session matching its 20-year high touched at the start of July as hawkish Fed bets built ahead of the Jackson Hole Symposium.
EUR/USD is rising boosted by better-than-expected data from Germany. German GDP was upwardly revised to 0.1% QoQ in Q2, from 0%. Meanwhile, the German IFO business climate was also better than forecast at 88.5, down from 88.7. However, this is still only marginally above a 2-year low. The ECB minutes didn’t bring anything new to the table.
AUD/USD is outperforming its major peers, boosted by the upbeat market mood and announcement of a huge stimulus plan in China, equating to around 1% of GDP to support the slowing economy.
AUD/USD 1% at 0.6980
EUR/USD +0.23% at 0.9935
Oil holds steady at $100.00
Oil prices are holding steady after strong gains across the past two sessions. On the one hand, oil prices are being supported by the prospect of OPEC cutting oil supply. However, this is being offset by the possibility of Iranian oil returning to the market should the Iran nuclear agreement be revived.
Earlier in the week the Saudi Energy Minister surprised the market by suggesting that a production cut could help stabilize the market. His comments lifted oil prices to a three-week high and reduced the odds of oil prices slipping below $90 in the near term.
A larger than expected draw on crude stock piles is also supporting the price. According to the latest EIA data, stockpiles declined by 3.3 million barrels.
WTI crude trades -0.35% at $92.78
Brent trades -0.1% at $100.35
Learn more about trading oil here.
Looking ahead
15:00 Jackson Hole Symposium
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum


S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.