



US open yields rise post Fed tech stocks drop
Tech stocks are pointing to a sharp drop on the open as US bond yields charge higher. US jobless claims miss forecasts.
Share this:
US futures
Dow futures -0.03% at 32900
S&P futures -0.6% 3938
Nasdaq futures -1.6%% at 13000
In Europe
FTSE -0.25% at 6745
Dax +0.81% at 14721
Euro Stoxx +0.2% at 3858
Learn more about trading indices
Bond yields shoot higher after Fed forecasts 6.5% growth
The Fed kept rates on hold as expected. The Fed also upped GDP forecast to 6.5% this year up from 4.3%. The inflation forecast was also upped to 2.4% from 2%, although the Fed said that this was expected to be temporary.
The Fed doubled down on its accommodative stance. The dot plot was more dovish than expected with most policy members not expecting a rate rise until 2024. Although 7 of the 18 members now expect a rate hike in 2023.
US bond yields have surged on the upgraded growth forecast and have grabbed onto the slight shift in voting at the Fed. Yields om the 10 year hit 1.75% a fresh 13 month high.
US jobless claims miss forecast
The number of people filing for unemployment benefits in the US rose unexpectedly to 770k vs 725k the previous week. This was above the 700k forecast. Despite the blip the US labour market is showing signs of improving as states reopen. The data had little impact on the USD or futures.
Stocks set for a mixed start, tech under pressure
After the S&P500 and the Dow Jones reached fresh all times highs in the previous session, stocks are pointing to a broadly lower start.
The tech sector is once again set to fall lower on the open on the back on the rising yields. High growth tech stocks are particularly sensitive to interest rate expectations.
However, the Dow Jones is pointing higher as cyclicals remain firmly in favour, supported by the Fed’s forecast of super strength economic growth this year.
Stocks in focus
Apple – trades -1.4% in the tech selloff and despite announcing that it could be releasing a new line of iPads as soon as next month.
Tesla – trades -3% pre-market as part of the broader tech selloff and after reports that its most popular model in the UK Model 3 will no longer be covered under the UK government’s subsidy programme. The news comes as Volkswagen & BMW ramp up their EV targets.
Nike – trades -0.6% lower pre-market and is due to report earnings after the close. Nike is expected to release another set of strong earnings as business continues to bounce back from the pandemic. Strong growth from China, the US and from digital sales is expected to underpin the numbers. However guidance will be key particularly with the outlook in Europe as stores start to reopen.
Where next for Nike share price?
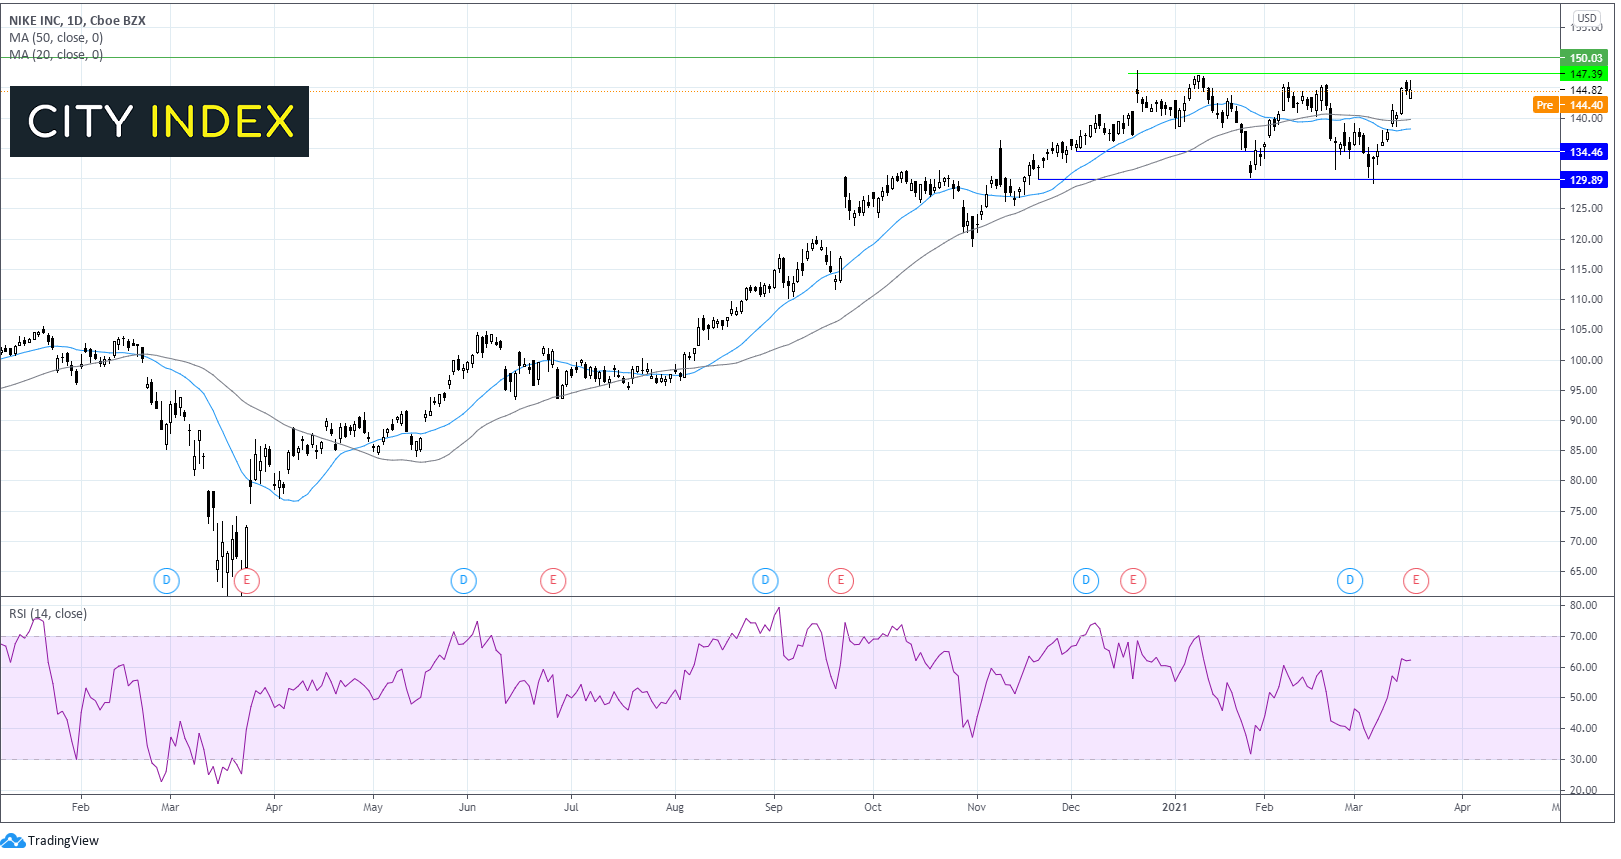
After posting strong gains across 2020, the bullish run has run out of steam and the price has been consolidating since the start of the year. The price trades range bound capped by 147 the all time high on the upside and 130 on the lower band.
The price trades towards the upper band of the holding channel, the RSI is indicative of further gains but the 147 resistance is pricing a tough nut to crack. A strong set of numbers could help Nike clear the 147 barrier and target 150 the round number.
Weakness in today’s numbers could see Nike’s share price move back towards 140 the 20 & 50 sma on the daily chart, before targeting 134 and 130.
FX – GBP/USD slips slightly as BoE keeps rates on hold
The US Dollar is pushing higher paring losses from the previous session. The DXY settled -0.5% lower on Wednesday after the Dovish Fed. However, bond yields are on the rise again and the greenback is tracing them higher.
GBP/USD – As expected the Bank of England kept interest rates on hold and the bond buying programme unchanged. The Pound slipped after the BoE said that it will not tighten monetary policy until there is clear evidence that significant progress is being made towards achieving 2% inflation target.
GBP/USD-0.2% at 1.3936
EUR/USD trades -0.4% at 1.1932
Oil extends losses for a fifth straight session
Oil is once again under pressure, slipping lower for a fifth straight session amid an increase in oil inventories, concerns over the deteriorating covid situation in Europe clouding the demand outlook cand on the back of a stronger US Dollar.
Yesterday’s EIA stock pile data showed that crude inventories increase for a fourth straight week after US refineries were forced to shut during an usually cold weather front. Inventories rose by 2.4 million barrels last week disappointing the market. API data earlier in the week had estimated a 1 million barrel draw.
US crude trades -1.1% at $63.94
Brent trades -1% at $67.04
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
There is no high impacting data due to be released.
US futures
Dow futures -0.03% at 32900
S&P futures -0.6% 3938
Nasdaq futures -1.6%% at 13000
In Europe
FTSE -0.25% at 6745
Dax +0.81% at 14721
Euro Stoxx +0.2% at 3858
Learn more about trading indices
Bond yields shoot higher after Fed forecasts 6.5% growth
The Fed kept rates on hold as expected. The Fed also upped GDP forecast to 6.5% this year up from 4.3%. The inflation forecast was also upped to 2.4% from 2%, although the Fed said that this was expected to be temporary.
The Fed doubled down on its accommodative stance. The dot plot was more dovish than expected with most policy members not expecting a rate rise until 2024. Although 7 of the 18 members now expect a rate hike in 2023.
US bond yields have surged on the upgraded growth forecast and have grabbed onto the slight shift in voting at the Fed. Yields om the 10 year hit 1.75% a fresh 13 month high.
US jobless claims miss forecast
The number of people filing for unemployment benefits in the US rose unexpectedly to 770k vs 725k the previous week. This was above the 700k forecast. Despite the blip the US labour market is showing signs of improving as states reopen. The data had little impact on the USD or futures.
Stocks set for a mixed start, tech under pressure
After the S&P500 and the Dow Jones reached fresh all times highs in the previous session, stocks are pointing to a broadly lower start.
The tech sector is once again set to fall lower on the open on the back on the rising yields. High growth tech stocks are particularly sensitive to interest rate expectations.
However, the Dow Jones is pointing higher as cyclicals remain firmly in favour, supported by the Fed’s forecast of super strength economic growth this year.
Stocks in focus
Apple – trades -1.4% in the tech selloff and despite announcing that it could be releasing a new line of iPads as soon as next month.
Tesla – trades -3% pre-market as part of the broader tech selloff and after reports that its most popular model in the UK Model 3 will no longer be covered under the UK government’s subsidy programme. The news comes as Volkswagen & BMW ramp up their EV targets.
Nike – trades -0.6% lower pre-market and is due to report earnings after the close. Nike is expected to release another set of strong earnings as business continues to bounce back from the pandemic. Strong growth from China, the US and from digital sales is expected to underpin the numbers. However guidance will be key particularly with the outlook in Europe as stores start to reopen.
Where next for Nike share price?
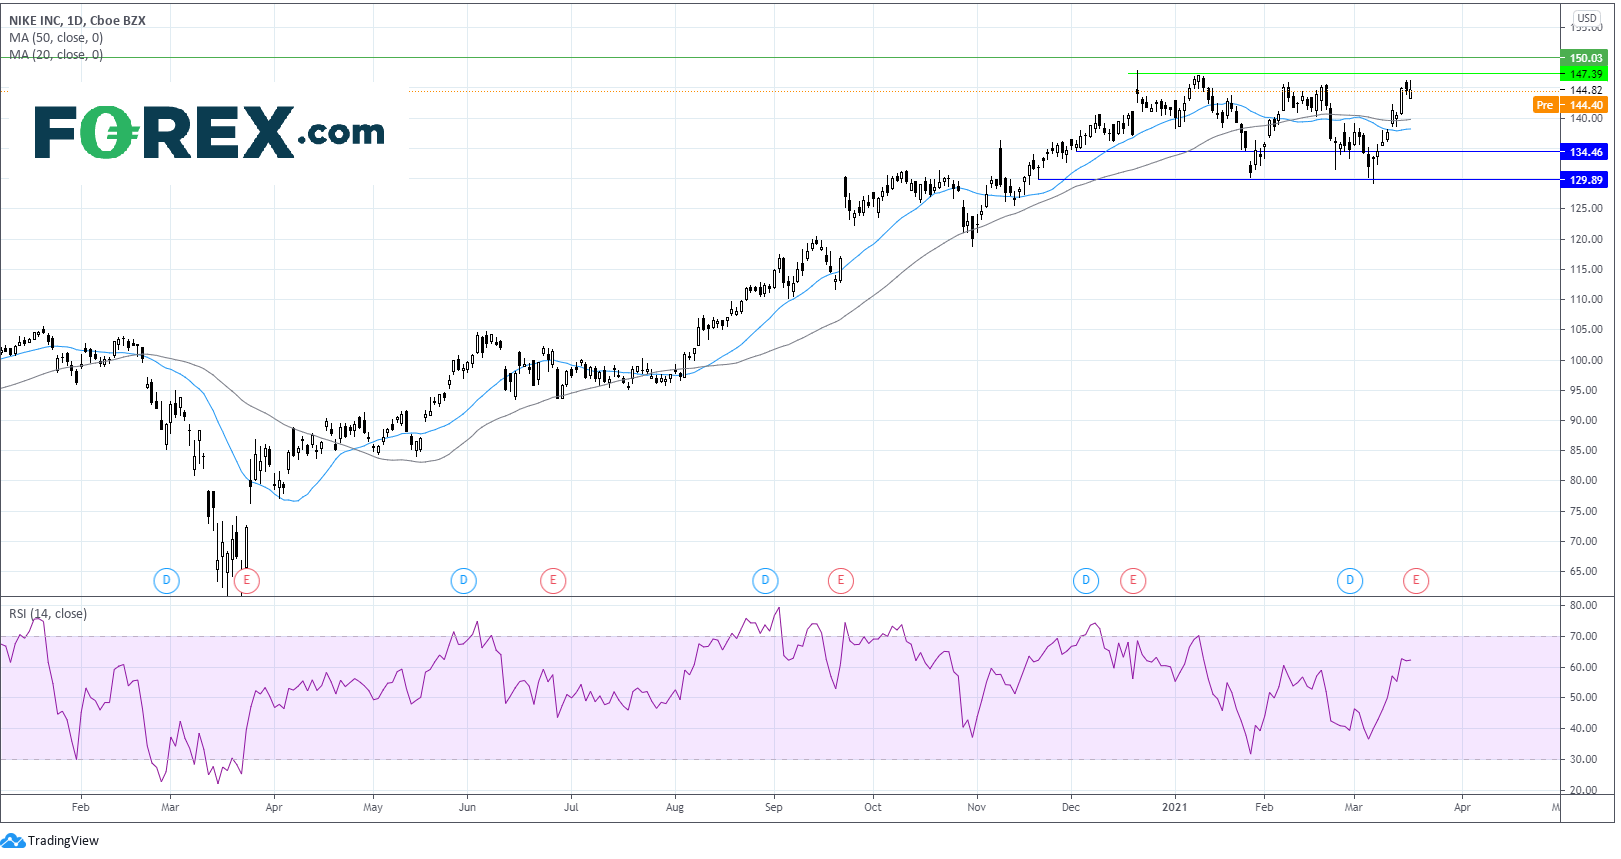
After posting strong gains across 2020, the bullish run has run out of steam and the price has been consolidating since the start of the year. The price trades range bound capped by 147 the all time high on the upside and 130 on the lower band.
The price trades towards the upper band of the holding channel, the RSI is indicative of further gains but the 147 resistance is pricing a tough nut to crack. A strong set of numbers could help Nike clear the 147 barrier and target 150 the round number.
Weakness in today’s numbers could see Nike’s share price move back towards 140 the 20 & 50 sma on the daily chart, before targeting 134 and 130.
FX – GBP/USD slips slightly as BoE keeps rates on hold
The US Dollar is pushing higher paring losses from the previous session. The DXY settled -0.5% lower on Wednesday after the Dovish Fed. However, bond yields are on the rise again and the greenback is tracing them higher.
GBP/USD – As expected the Bank of England kept interest rates on hold and the bond buying programme unchanged. The Pound slipped after the BoE said that it will not tighten monetary policy until there is clear evidence that significant progress is being made towards achieving 2% inflation target.
GBP/USD -0.2% at 1.3936
EUR/USD trades -0.4% at 1.1932
Oil extends losses for a fifth straight session
Oil is once again under pressure, slipping lower for a fifth straight session amid an increase in oil inventories, concerns over the deteriorating covid situation in Europe clouding the demand outlook cand on the back of a stronger US Dollar.
Yesterday’s EIA stock pile data showed that crude inventories increase for a fourth straight week after US refineries were forced to shut during an usually cold weather front. Inventories rose by 2.4 million barrels last week disappointing the market. API data earlier in the week had estimated a 1 million barrel draw.
US crude trades -1.1% at $63.94
Brent trades -1% at $67.04
Learn more about trading oil here.
The complete guide to trading oil markets
Looking ahead
There is no high impacting data due to be released.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Outlook: AUD/USD Holds 70c Ahead of RBA and CPI
AUD/USD faces an expected RBA hike and Australian CPI before attention turns to US PCE, ISM and nonfarm payrolls later in the week.

EUR/USD weekly outlook: Oil, inflation and NFP in focus
After coming under significant pressure in recent weeks, the EUR/USD came off its lows to finish the week on a positive note on Friday, albeit with only a mild rebound. That was not enough to prevent the exchange rate falling for the third consecutive week, as the US dollar and bond yields rallied across the board.


USD/JPY Weekly Outlook: Payrolls loom as US rates remain the dominant driver
Strong US growth and hawkish Fed pricing continue to support USD/JPY, while intervention risk appears to be kicking in at lower levels
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.