



Weekly EUR/USD outlook: US CPI and ECB in focus after strong jobs data
At the time of writing, the US dollar looked set to finish the week on a strong footing after a much stronger-than-expected labour market report prompted investors to reassess the outlook for Federal Reserve policy, sending yields higher.
Share this:
This weekly EUR/USD outlook was written before the end of European session on Friday and was therefore subject to some volatility during the NY session. At the time of writing, the US dollar looked set to finish the week on a strong footing after a much stronger-than-expected labour market report prompted investors to reassess the outlook for Federal Reserve policy, sending yields higher. The EUR/USD was easing down to 1.1500 area after relentless post-NFP selling pressure. Looking ahead, we have US CPI and ECB rate decisions looming in the week ahead. Traders are also eying a potential deal between the US and Iran to open the Strait of Hormuz, which explains why oil prices fell more than 3% at the time of writing.
Robust payrolls data reinforces dollar strength
Non-farm payrolls rose by 172,000 in May, comfortably ahead of expectations for 85,000, while revisions added a further 93,000 jobs to the previous two months of data.
The unemployment rate held steady at 4.3%, matching its lowest level since August and remaining well below the long-term average of 5.7%. Meanwhile, annual wage growth came in at 3.4%, suggesting that while inflationary pressures from the labour market have moderated, demand for workers remains resilient.
Taken together, the figures point to a labour market that has regained momentum during the first half of 2026, reducing concerns about an imminent slowdown in economic activity.
Markets reacted swiftly. Traders now fully price in a quarter-point Federal Reserve rate increase by year-end, a notable shift from expectations just a few weeks ago. Treasury yields moved higher, the dollar strengthened across the board, and rate-sensitive assets came under pressure.
EUR/USD breaks trend support as US rate expectations shift
The repricing of Fed expectations caused the dollar to rally, and this weighed heavily on assets like gold and the euro. The, EUR/USD took a plunge below the 1.16 level, with the widening divergence between US and European interest rate expectations helping to support the greenback.
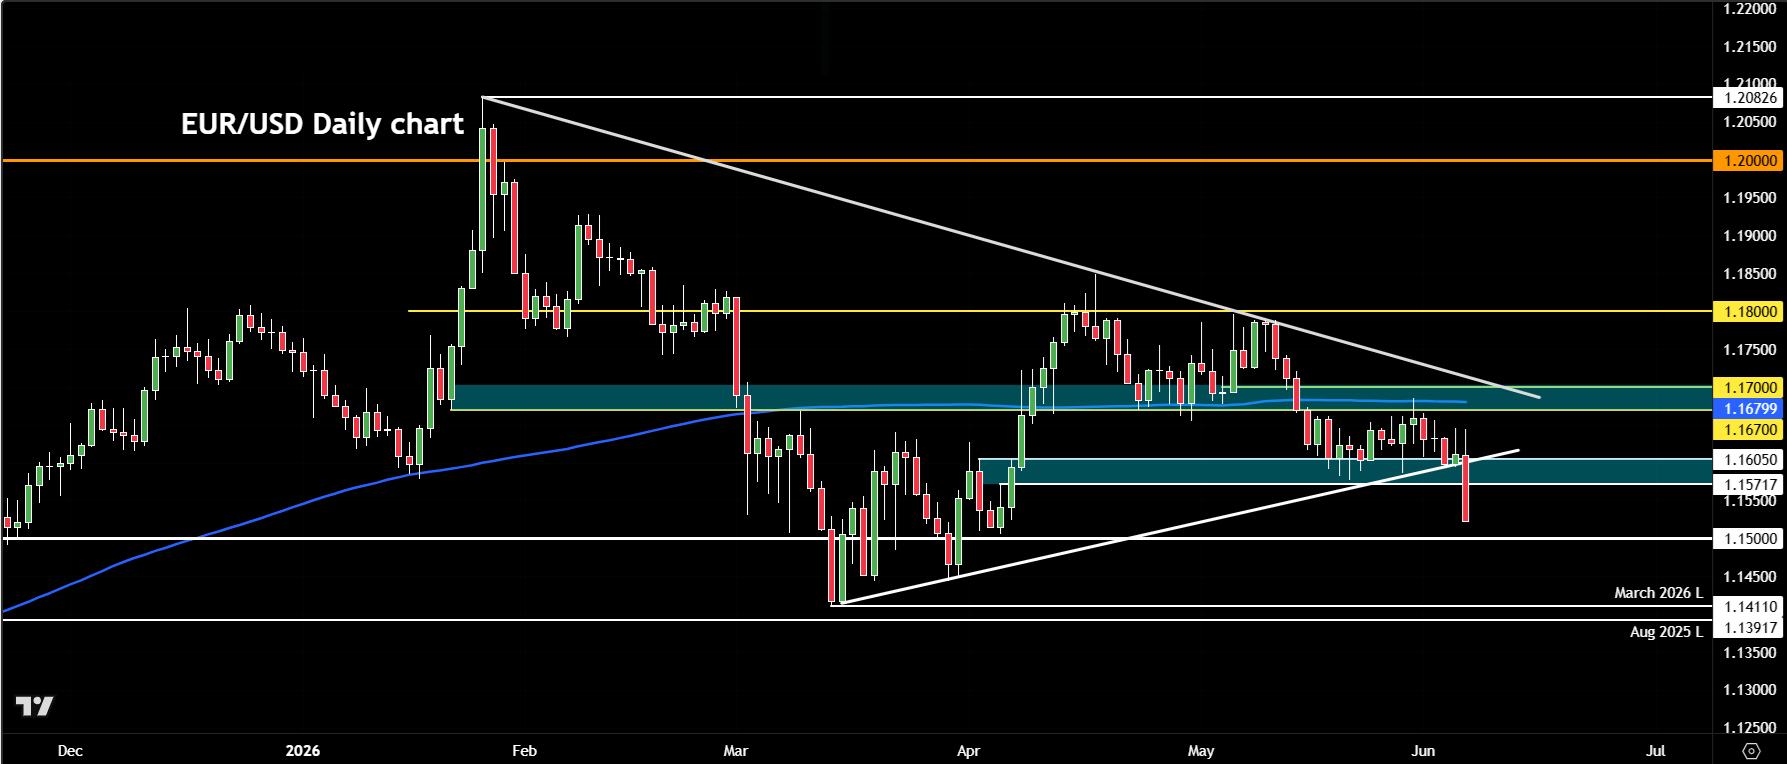
The technical breakdown means 1.1500 and possibly the March low of 1.1410 could be hit next week, barring a plunge in oil prices – say as a result of a deal between the US and Iran to re-open the Strait of Hormuz.
Resistance is now seen around 1.1600 area, followed by 1.1670 and then 1.1700.
While the euro faces its own set of catalysts next week, the immediate driver remains the market’s renewed confidence in the strength of the US economy.
EUR/USD outlook: inflation data and ECB take centre stage
Attention now turns to US consumer price inflation on Wednesday. After surprising markets with a 3.8% annual reading in April, inflation is expected to accelerate further to 4.2% in May, reflecting the recent surge in energy prices.
The release could prove pivotal for market sentiment. A reading above consensus would likely reinforce expectations that the Federal Reserve may need to keep policy restrictive for longer, potentially extending the dollar’s recent gains. Conversely, any downside surprise could prompt investors to scale back some of the hawkish pricing that emerged following the payrolls report.
On Thursday, attention shifts to Frankfurt where the European Central Bank is expected to deliver a widely anticipated 25 basis point rate increase. The decision itself is unlikely to surprise markets; instead, investors will focus on President Lagarde’s guidance regarding the path beyond June.
With inflation still proving stubborn across parts of the eurozone, policymakers may be reluctant to signal an imminent pause. Any indication that further tightening remains on the table could offer modest support to the EUR/USD outlook, although the currency’s direction will also depend heavily on developments between the United States and Iran.


-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.

Japanese Yen Outlook: USD/JPY, GBP/JPY, AUD/JPY Setups
USD/JPY and GBP/JPY show signs of stabilising, while AUD/JPY remains vulnerable as yen crosses deliver mixed technical signals.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.