



Another step high ahead of US NFP
Government and central bank stimulus and optimism surrounding the reopening of economies continues to overshadow astonishing data.
Share this:

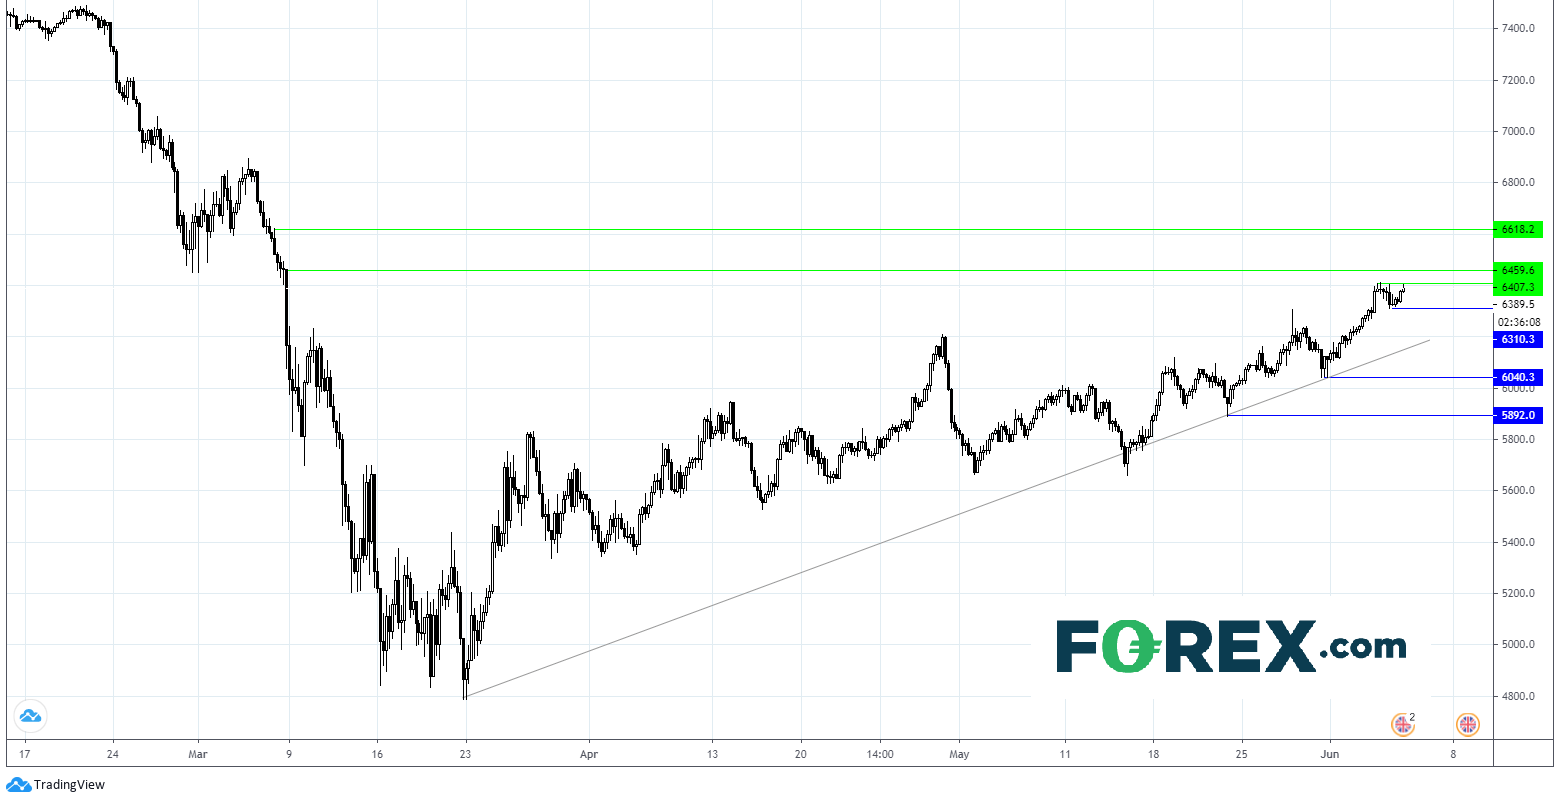
Wall Street joined Europe finishing lower in the previous session as the risk on rally paused for breath. After surging across the first part of the week, and a brief dip lower on Thursday, traders are once again showing willingness to take on risk and push higher into the weekend, despite the upcoming non-farm payroll.
European bourses are pointing to an upbeat start, as are US futures, as a combination of government and central bank stimulus and optimism surrounding the reopening of economies continues to overshadow astonishing data which lays bare the destruction that coronavirus crisis has caused to economies across the globe.
German factory orders plunge
Yesterday the ECB added to the stimulus effect, expanding its emergency bond buying programme by €600 billion, more than what the market had expected. However, the grim staff projections offered support for the move as did today’s German factory orders which declined a record -25.8% mom in April, worse than the -19.7% forecast.
Yesterday the ECB added to the stimulus effect, expanding its emergency bond buying programme by €600 billion, more than what the market had expected. However, the grim staff projections offered support for the move as did today’s German factory orders which declined a record -25.8% mom in April, worse than the -19.7% forecast.
In true show of how the markets react to dire data of late, the Euro shrugged off the numbers, remaining elevated versus the weaker USD, whilst the Dax showed little regard, with a 1% jump on the open still forecast.
8 million jobs lost
Attention will now turn to the US non-farm payrolls. Expectations are for 8 million jobs to have been lost in May, a significant improvement on the 25 million recorded in April. This would take unemployment to 19.5%, up from 14.7% last month. Given that he ADP private payroll report, a strong lead indicator for the NFP was significantly better than forecast, there is a good chance that today’s jobs report will surprise to the upside. Wages are expected to remain skewed to the upside as more low earners are laid off.
Attention will now turn to the US non-farm payrolls. Expectations are for 8 million jobs to have been lost in May, a significant improvement on the 25 million recorded in April. This would take unemployment to 19.5%, up from 14.7% last month. Given that he ADP private payroll report, a strong lead indicator for the NFP was significantly better than forecast, there is a good chance that today’s jobs report will surprise to the upside. Wages are expected to remain skewed to the upside as more low earners are laid off.
If the data isn’t as bad as expected, this could signal that the downturn might not be as bad as initially forecast, providing an uplifting effect to the market. Even if the figure is worse than anticipated, there is a good chance that markets will brush it off as we have seen countless times with dire data over the past 10 weeks.
A word on oil
Oil is nudging higher for the fourth straight session, as traders await an OPEC+ meeting which could take place as soon as this weekend. WTI has rallied 5.9% across the week, its sixth consecutive week of gains supported by output cuts and signs of improving fuel demand. The pace of gains has slowed as investors await confirmation, potentially this Saturday as to whether OPEC+ output cuts will be extended. Even if the output cuts are extended there is always the question of compliance.
FTSE Chart
Wall Street joined Europe finishing lower in the previous session as the risk on rally paused for breath. After surging across the first part of the week, and a brief dip lower on Thursday, traders are once again showing willingness to take on risk and push higher into the weekend, despite the upcoming non-farm payroll.
European bourses are pointing to an upbeat start, as are US futures, as a combination of government and central bank stimulus and optimism surrounding the reopening of economies continues to overshadow astonishing data which lays bare the destruction that coronavirus crisis has caused to economies across the globe.
German factory orders plunge
Yesterday the ECB added to the stimulus effect, expanding its emergency bond buying programme by €600 billion, more than what the market had expected. However, the grim staff projections offered support for the move as did today’s German factory orders which declined a record -25.8% mom in April, worse than the -19.7% forecast.
Yesterday the ECB added to the stimulus effect, expanding its emergency bond buying programme by €600 billion, more than what the market had expected. However, the grim staff projections offered support for the move as did today’s German factory orders which declined a record -25.8% mom in April, worse than the -19.7% forecast.
In true show of how the markets react to dire data of late, the Euro shrugged off the numbers, remaining elevated versus the weaker USD, whilst the Dax showed little regard, with a 1% jump on the open still forecast.
8 million jobs lost
Attention will now turn to the US non-farm payrolls. Expectations are for 8 million jobs to have been lost in May, a significant improvement on the 25 million recorded in April. This would take unemployment to 19.5%, up from 14.7% last month. Given that he ADP private payroll report, a strong lead indicator for the NFP was significantly better than forecast, there is a good chance that today’s jobs report will surprise to the upside. Wages are expected to remain skewed to the upside as more low earners are laid off.
Attention will now turn to the US non-farm payrolls. Expectations are for 8 million jobs to have been lost in May, a significant improvement on the 25 million recorded in April. This would take unemployment to 19.5%, up from 14.7% last month. Given that he ADP private payroll report, a strong lead indicator for the NFP was significantly better than forecast, there is a good chance that today’s jobs report will surprise to the upside. Wages are expected to remain skewed to the upside as more low earners are laid off.
If the data isn’t as bad as expected, this could signal that the downturn might not be as bad as initially forecast, providing an uplifting effect to the market. Even if the figure is worse than anticipated, there is a good chance that markets will brush it off as we have seen countless times with dire data over the past 10 weeks.
A word on oil
Oil is nudging higher for the fourth straight session, as traders await an OPEC+ meeting which could take place as soon as this weekend. WTI has rallied 5.9% across the week, its sixth consecutive week of gains supported by output cuts and signs of improving fuel demand. The pace of gains has slowed as investors await confirmation, potentially this Saturday as to whether OPEC+ output cuts will be extended. Even if the output cuts are extended there is always the question of compliance.
FTSE Chart
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.