




Apple Earnings Preview
Apple is due to report favourable earnings on 28th January
Share this:
When:
Tuesday 28th January after US close
Tuesday 28th January after US close
Expectations:
Revenue $85.5 billion - $89.5 billion
EPS $4.53
Revenue $85.5 billion - $89.5 billion
EPS $4.53
A lot to live up to
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
After rallying over 100% across the previous year, 33% in the past three months alone and joining the exclusive $1 trillion dollar club, the pressure is on Apple to prove that it is worth recent lofty valuations. After returning to top and bottom line growth the market will want to see that the momentum can continue.
Favourable earnings expected
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Revenue guidance is between $85.5 billion and $89.5 billion with the midpoint implying 4% growth. Apple’s guidance is typically conservative. Services and wearables are expected to see another period of strong growth whilst iPhone sales saw an upswing in demand in the final part of Q4 boding well for Q1.
Key points to watch for on earnings call:
1. 5G – management comments on plan to capitalise on 5G network
2. Emerging services – comments on financial services, how Apple card is performing, and healthcare could be increasingly important drivers in 2020.
3. Non – smart phone products – after strong Christmas sales of Apple watches and Air Pods Pro
Risks Ahead - Upgrade cycle 2020
Recent optimism surrounding Apple is owing to the upgrade cycle that the broader smart phone market is heading into. For the past few years customers have had little reason to upgrade or replace their phones, hanging onto their devices for longer.
With the build out of the 5G network, customers will have a reason to upgrade their phones. 5G and China are expected to be big drivers of growth at Apple. US, UK and Korea will also play their part.
It is this upgrade cycle, the wearables business and Apple’s focus on services, which are the main reasons behind analysts lifting Apple’s price target, helping to lift the share price.
There is of course no guarantee that the 5G upgrade cycle will appear. There is always the possibility that investors won’t be wowed by Apple’s 5G iPhone or simply aren’t interested in upgrading to 5G. iPhone shipments actually declined during the move from 3G to 5G.
As demand expectations have helped lift Apple shares to $319.99, should that demand fail to materialise across the coming year, Apple’s share price take a hit.
Chart thoughts
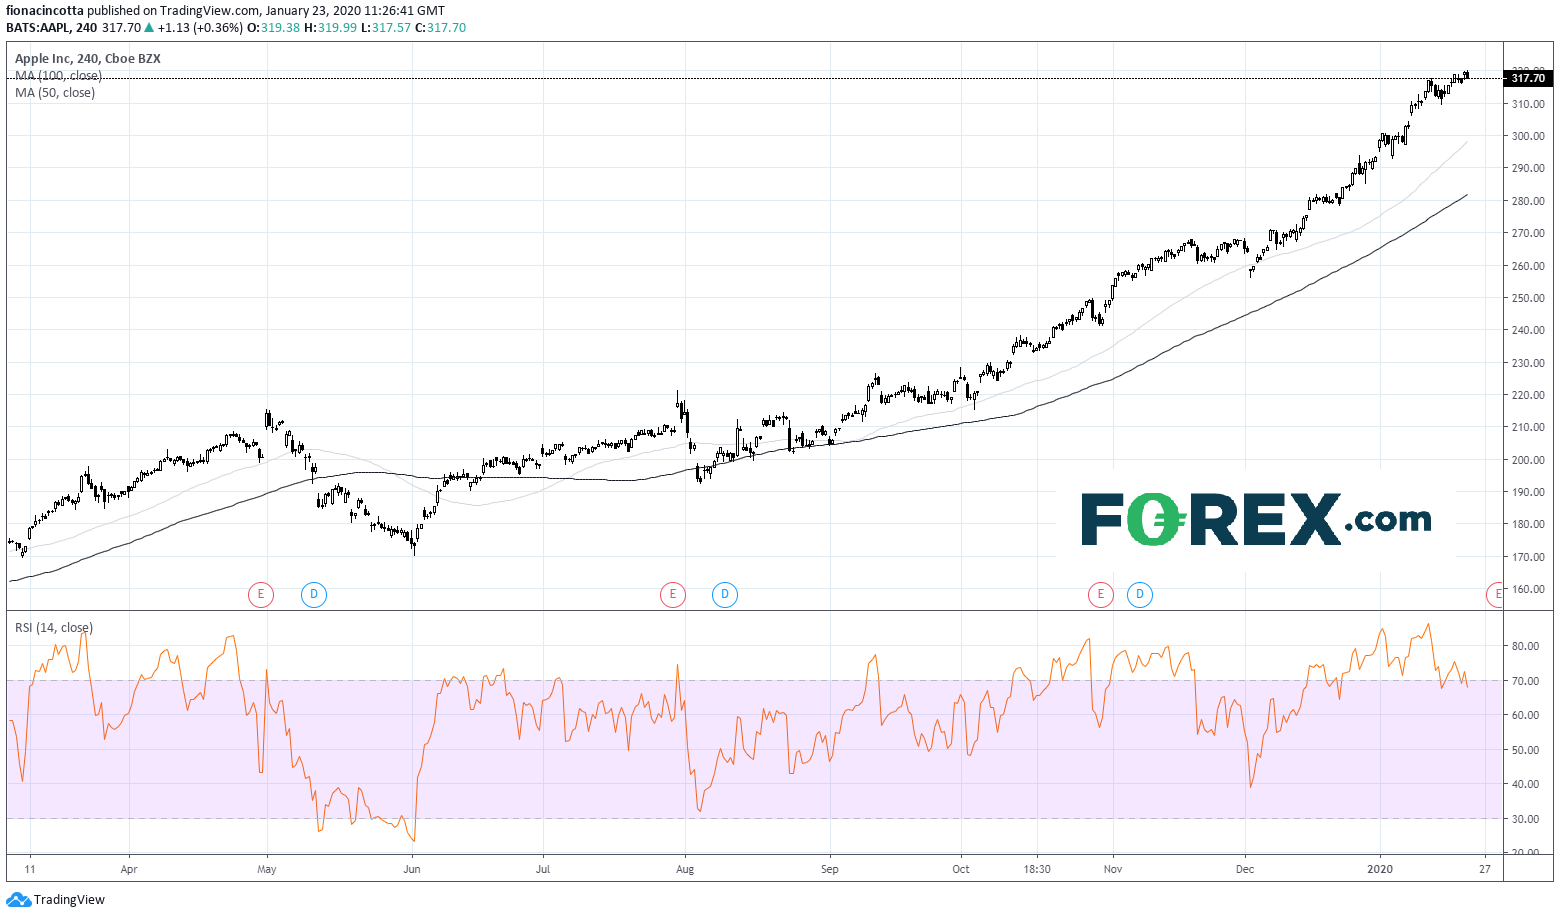
Apple trades firmly above its 50, 100 and 200 sma on a strongly bullish 4 hour chart. On the RSI, it has dipped back below 70 so is no longer in over bought territory. Immediate resistance is at $319.99 the recent all-time high. Immediate support is at the psychological level of $300.
Related tags:




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.

S&P 500, Nasdaq 100 Forecast for the Week Ahead
A hawkish Fed and 10-Year Notes on the verge of a push above 5%, yet stocks have so far shrugged off that fear. But can it continue?

Hang Seng Tech rout nears make-or-break zone
The technical damage is clear, but with Hang Seng Tech now deeply stretched and approaching major support, the risk-reward is becoming more two-sided.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.