



Asia Morning August 17
Note that shares of China-based companies Baidu (BIDU) and Iqiyi (IQ) slid...
Share this:

On Friday, U.S. stocks were little changed. The Dow Jones Industrial Average edged up 34 points (+0.12%) to 27931, while the S&P 500 was flat at 3372 and the Nasdaq 100 eased 13 points (-0.12%) to 11164.

Source: GAIN Capital, TradingView
Still, no progress was made on political negotiations over the new coronavirus relief package.
Energy (+0.94%), Transportation (+0.91%) and Food & Staples Retailing (+0.73%) sectors traded higher, while Utilities (-0.91%), Commercial & Professional Services (-0.51%) and Household & Personal Products (-0.39%) sectors were under pressure. McKesson Corp (MCK +4.26%), DXC Technology (DXC +3.92%) and Applied Materials (AMAT +3.92%) were top gainers.
Note that shares of China-based companies Baidu (BIDU -6.29%) and Iqiyi (IQ -11.16%) slid.
Regarding U.S. economic data, Retail Sales gained 1.2% on month in July (+2.1% expected) and Industrial Production gained 3.0% (as expected). The University of Michigan Consumer Sentiment index rose to 72.8 in a preliminary August reading (72.0 expected).
Due later today is the U.S. Empire State Manufacturing Survey (a decline to 14.5 in August expected).
European stocks remained under pressure. The Stoxx Europe 600 Index fell 1.20%, Germany's DAX 30 declined 0.71%, France's CAC 40 shed 1.58%, and the U.K.'s FTSE 100 lost 1.55%.
U.S. government bond prices stabilized, as the benchmark 10-year Treasury yield eased to 0.708% from 0.716% Thursday.
Spot gold price declined $8.00 (-0.44%) to $1,945 an ounce halting a two-day rebound. Spot silver price shed 3.88% to $26.44 an ounce.
U.S. WTI crude oil futures (September) dipped 0.5% to $42.02 a barrel.
On the forex front, the ICE U.S. Dollar Index dropped 0.3% on day to 93.10, posting a three-day decline.
EUR/USD rose 0.3% to 1.1841. Official data showed that the eurozone's GDP contracted 15.0% on year in the second quarter (as expected).
GBP/USD gained 0.2% to 1.3084.
USD/JPY lost 0.3% to 106.59. This morning, Japan's second quarter annualized GDP shrank 27.8% on quarter (-26.9% expected), the largest decline in record, according to the government.
USD/CAD advanced 0.4% to 1.3266, halting a four-day losing streak. Government data showed that Canada's manufacturing sales grew 20.7% on month in June (+16.4% expected).
Other commodity-linked currencies were mixed against the greenback. AUD/USD rose 0.3% to 0.7171 while NZD/USD slipped 0.1% to 0.6538. Official data showed that China's industrial production grew 4.8% on year in July (+5.1% expected) while retail sales dropped 1.1% (+0.1% expected).
Dow Jones Industrial Average: Daily Chart:
Source: GAIN Capital, TradingView
Still, no progress was made on political negotiations over the new coronavirus relief package.
Energy (+0.94%), Transportation (+0.91%) and Food & Staples Retailing (+0.73%) sectors traded higher, while Utilities (-0.91%), Commercial & Professional Services (-0.51%) and Household & Personal Products (-0.39%) sectors were under pressure. McKesson Corp (MCK +4.26%), DXC Technology (DXC +3.92%) and Applied Materials (AMAT +3.92%) were top gainers.
Note that shares of China-based companies Baidu (BIDU -6.29%) and Iqiyi (IQ -11.16%) slid.
Regarding U.S. economic data, Retail Sales gained 1.2% on month in July (+2.1% expected) and Industrial Production gained 3.0% (as expected). The University of Michigan Consumer Sentiment index rose to 72.8 in a preliminary August reading (72.0 expected).
Due later today is the U.S. Empire State Manufacturing Survey (a decline to 14.5 in August expected).
European stocks remained under pressure. The Stoxx Europe 600 Index fell 1.20%, Germany's DAX 30 declined 0.71%, France's CAC 40 shed 1.58%, and the U.K.'s FTSE 100 lost 1.55%.
U.S. government bond prices stabilized, as the benchmark 10-year Treasury yield eased to 0.708% from 0.716% Thursday.
Spot gold price declined $8.00 (-0.44%) to $1,945 an ounce halting a two-day rebound. Spot silver price shed 3.88% to $26.44 an ounce.
U.S. WTI crude oil futures (September) dipped 0.5% to $42.02 a barrel.
On the forex front, the ICE U.S. Dollar Index dropped 0.3% on day to 93.10, posting a three-day decline.
EUR/USD rose 0.3% to 1.1841. Official data showed that the eurozone's GDP contracted 15.0% on year in the second quarter (as expected).
GBP/USD gained 0.2% to 1.3084.
USD/JPY lost 0.3% to 106.59. This morning, Japan's second quarter annualized GDP shrank 27.8% on quarter (-26.9% expected), the largest decline in record, according to the government.
USD/CAD advanced 0.4% to 1.3266, halting a four-day losing streak. Government data showed that Canada's manufacturing sales grew 20.7% on month in June (+16.4% expected).
Other commodity-linked currencies were mixed against the greenback. AUD/USD rose 0.3% to 0.7171 while NZD/USD slipped 0.1% to 0.6538. Official data showed that China's industrial production grew 4.8% on year in July (+5.1% expected) while retail sales dropped 1.1% (+0.1% expected).
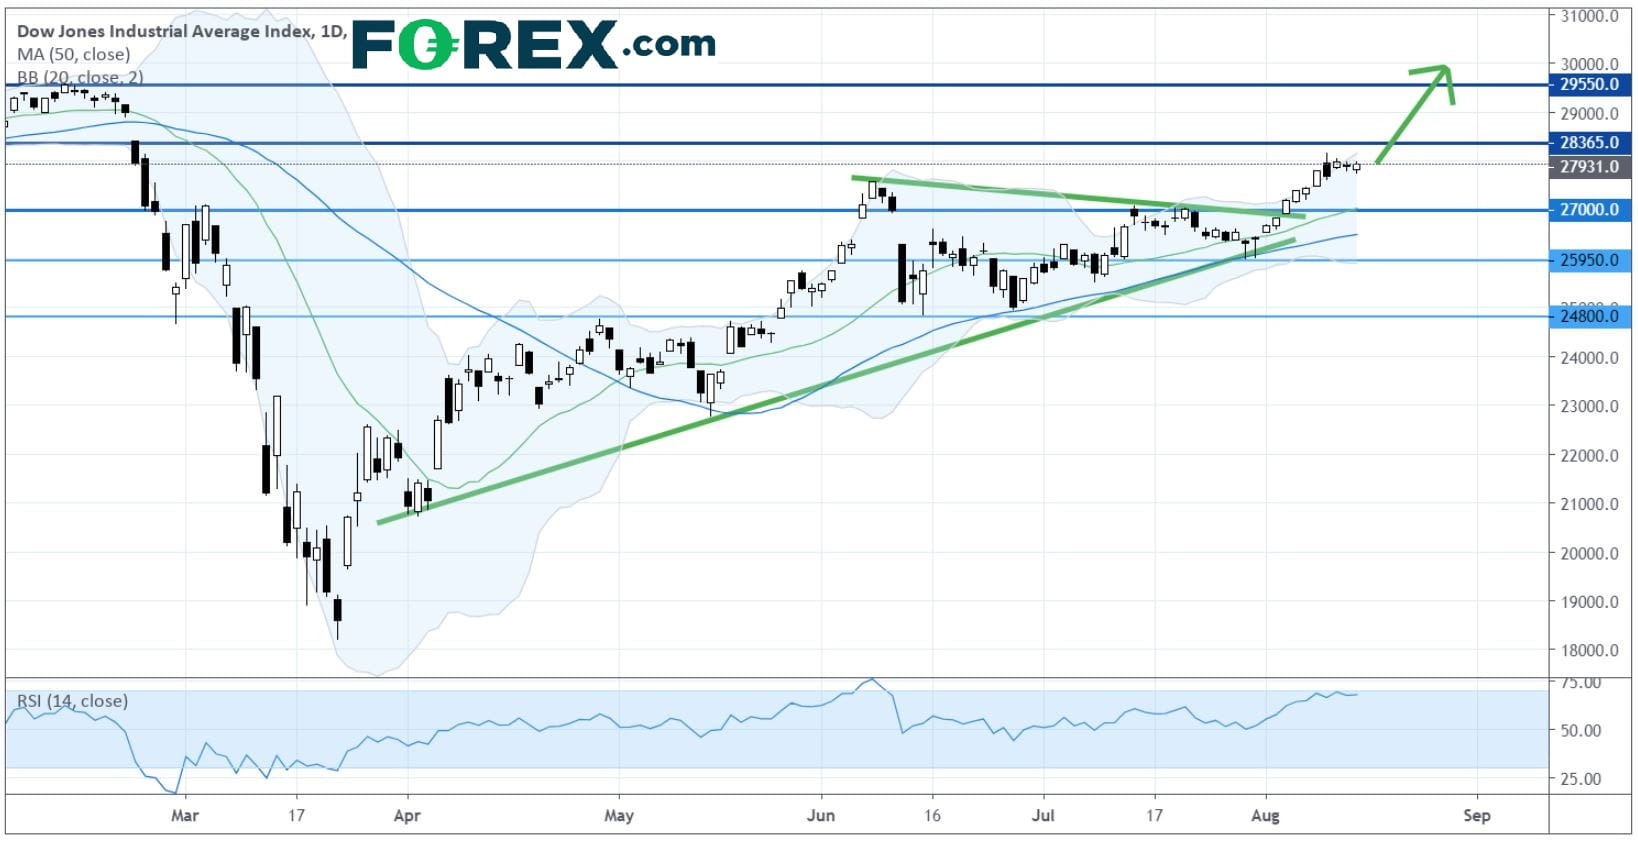
On Friday, U.S. stocks were little changed. The Dow Jones Industrial Average edged up 34 points (+0.12%) to 27931, while the S&P 500 was flat at 3372 and the Nasdaq 100 eased 13 points (-0.12%) to 11164.
Source: GAIN Capital, TradingView
Still, no progress was made on political negotiations over the new coronavirus relief package.
Energy (+0.94%), Transportation (+0.91%) and Food & Staples Retailing (+0.73%) sectors traded higher, while Utilities (-0.91%), Commercial & Professional Services (-0.51%) and Household & Personal Products (-0.39%) sectors were under pressure. McKesson Corp (MCK +4.26%), DXC Technology (DXC +3.92%) and Applied Materials (AMAT +3.92%) were top gainers.
Note that shares of China-based companies Baidu (BIDU -6.29%) and Iqiyi (IQ -11.16%) slid.
Regarding U.S. economic data, Retail Sales gained 1.2% on month in July (+2.1% expected) and Industrial Production gained 3.0% (as expected). The University of Michigan Consumer Sentiment index rose to 72.8 in a preliminary August reading (72.0 expected).
Due later today is the U.S. Empire State Manufacturing Survey (a decline to 14.5 in August expected).
European stocks remained under pressure. The Stoxx Europe 600 Index fell 1.20%, Germany's DAX 30 declined 0.71%, France's CAC 40 shed 1.58%, and the U.K.'s FTSE 100 lost 1.55%.
U.S. government bond prices stabilized, as the benchmark 10-year Treasury yield eased to 0.708% from 0.716% Thursday.
Spot gold price declined $8.00 (-0.44%) to $1,945 an ounce halting a two-day rebound. Spot silver price shed 3.88% to $26.44 an ounce.
U.S. WTI crude oil futures (September) dipped 0.5% to $42.02 a barrel.
On the forex front, the ICE U.S. Dollar Index dropped 0.3% on day to 93.10, posting a three-day decline.
EUR/USD rose 0.3% to 1.1841. Official data showed that the eurozone's GDP contracted 15.0% on year in the second quarter (as expected).
GBP/USD gained 0.2% to 1.3084.
USD/JPY lost 0.3% to 106.59. This morning, Japan's second quarter annualized GDP shrank 27.8% on quarter (-26.9% expected), the largest decline in record, according to the government.
USD/CAD advanced 0.4% to 1.3266, halting a four-day losing streak. Government data showed that Canada's manufacturing sales grew 20.7% on month in June (+16.4% expected).
Other commodity-linked currencies were mixed against the greenback. AUD/USD rose 0.3% to 0.7171 while NZD/USD slipped 0.1% to 0.6538. Official data showed that China's industrial production grew 4.8% on year in July (+5.1% expected) while retail sales dropped 1.1% (+0.1% expected).
Dow Jones Industrial Average: Daily Chart:
Source: GAIN Capital, TradingView
Still, no progress was made on political negotiations over the new coronavirus relief package.
Energy (+0.94%), Transportation (+0.91%) and Food & Staples Retailing (+0.73%) sectors traded higher, while Utilities (-0.91%), Commercial & Professional Services (-0.51%) and Household & Personal Products (-0.39%) sectors were under pressure. McKesson Corp (MCK +4.26%), DXC Technology (DXC +3.92%) and Applied Materials (AMAT +3.92%) were top gainers.
Note that shares of China-based companies Baidu (BIDU -6.29%) and Iqiyi (IQ -11.16%) slid.
Regarding U.S. economic data, Retail Sales gained 1.2% on month in July (+2.1% expected) and Industrial Production gained 3.0% (as expected). The University of Michigan Consumer Sentiment index rose to 72.8 in a preliminary August reading (72.0 expected).
Due later today is the U.S. Empire State Manufacturing Survey (a decline to 14.5 in August expected).
European stocks remained under pressure. The Stoxx Europe 600 Index fell 1.20%, Germany's DAX 30 declined 0.71%, France's CAC 40 shed 1.58%, and the U.K.'s FTSE 100 lost 1.55%.
U.S. government bond prices stabilized, as the benchmark 10-year Treasury yield eased to 0.708% from 0.716% Thursday.
Spot gold price declined $8.00 (-0.44%) to $1,945 an ounce halting a two-day rebound. Spot silver price shed 3.88% to $26.44 an ounce.
U.S. WTI crude oil futures (September) dipped 0.5% to $42.02 a barrel.
On the forex front, the ICE U.S. Dollar Index dropped 0.3% on day to 93.10, posting a three-day decline.
EUR/USD rose 0.3% to 1.1841. Official data showed that the eurozone's GDP contracted 15.0% on year in the second quarter (as expected).
GBP/USD gained 0.2% to 1.3084.
USD/JPY lost 0.3% to 106.59. This morning, Japan's second quarter annualized GDP shrank 27.8% on quarter (-26.9% expected), the largest decline in record, according to the government.
USD/CAD advanced 0.4% to 1.3266, halting a four-day losing streak. Government data showed that Canada's manufacturing sales grew 20.7% on month in June (+16.4% expected).
Other commodity-linked currencies were mixed against the greenback. AUD/USD rose 0.3% to 0.7171 while NZD/USD slipped 0.1% to 0.6538. Official data showed that China's industrial production grew 4.8% on year in July (+5.1% expected) while retail sales dropped 1.1% (+0.1% expected).
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast: Eurozone stagflation risks mount as dollar holds firm ahead of data
The dollar was bouncing back at the time of writing, after it had eased overnight on the back of some weaker-than-expected economic data yesterday which had prompted markets to scale back expectations of an October Fed rate hike. However, with more significant US data due today and Friday, and with oil prices continuing to remain elevated, the dollar’s broader direction remains bullish.

Treasury Yields Lose Momentum as Energy ETF Retreats
The 10-year Treasury yield is testing a resistance zone respected since the 1920s, as bearish RSI divergence signals fading upside momentum.


NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.