



Asia Morning June 26
On Thursday, U.S. stocks rebounded making most of the gains in the last trading hour. Goldman Sachs (+4.59%), Wells Fargo (+4.79%) and JPMorgan Chase (+3.49%) led major indexes higher...
Share this:

On Thursday, U.S. stocks rebounded making most of the gains in the last trading hour. The Dow Jones Industrial Average rose 299 points (+1.18%) to 25745, the S&P 500 gained 33 points (+1.10%) to 3083, and the Nasdaq 100 was up 99 points (+0.99%) to 10101.
S&P 500 Index: Daily Chart

Source: GAIN Captial, TradingView
Banks (+3.57%), Insurance (+2.55%) and Diversified Financials (+2.07%) sectors gained the most after financial regulators eased up "Volcker Rule" restrictions on banks' risk-taking. Goldman Sachs (GS +4.59%), Wells Fargo (WFC +4.79%) and JPMorgan Chase (JPM +3.49%) led major indexes higher.
However, in after-market hours, the Federal Reserve, in anticipation of a prolonged economic downturn, announced measures to bar the nation's biggest banks from buying back their own stocks or increasing dividend payments in the third quarter.
On the technical side, about 36.7% (43.1% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 13.5% (35.3% in the prior session) were trading above their 20-day moving average.
The U.S. Labor Department reported that Initial Jobless Claims decreased to 1.480 million for the week ended June 20 (1.320 million expected) and Continuing Claims slid to 19.522 million for the week ended June 13 (20.000 million expected).
And the Commerce Department said first-quarter GDP contracted 5.0% on quarter annualized (as expected), and Durable Goods Orders (preliminary reading) jumped 15.8% on month in May (+10.5% expected).
Due later today are reports on May Personal Income (-6.0% on month expected), Personal Spending (+9.0% expected), and the University of Michigan's Consumer Sentiment Index (a rise to 79.2 in June expected).
European stocks were broadly higher. The Stoxx Europe 600 Index climbed 0.7%, Germany's DAX rose 0.7%, France's CAC jumped 1.0%, and the U.K.'s FTSE 100 was up 0.4%.
U.S. government bond prices remained firm, as the benchmark 10-year Treasury yield dropped further to 0.670% from 0.683% Wednesday.
Spot gold price added $2.00 (+0.1%) to $1,763 an ounce.
Oil prices stabilized after losing for two sessions. WTI crude oil futures (August) increased 1.9% to $38.72 a barrel.
On the forex front, the ICE U.S. Dollar Index climbed 0.2% on day to 97.39, up for a second straight session. The Federal Reserve released the results of its stress tests, stating: ""The banking system has been a source of strength during this crisis, and the results of our sensitivity analyses show that our banks can remain strong in the face of even the harshest shocks."
EUR/USD fell 0.3% to 1.1220. Germany's GfK Consumer Confidence Index for July improved to -9.6 (-12.0 expected) from -18.6 in June.
GBP/USD was little changed at 1.2424.
USD/JPY edged up 0.1% to 107.18. This morning, official data showed that Japan's Tokyo CPI grew 0.3% on year in June (as expected).
S&P 500 Index: Daily Chart
Source: GAIN Captial, TradingView
Banks (+3.57%), Insurance (+2.55%) and Diversified Financials (+2.07%) sectors gained the most after financial regulators eased up "Volcker Rule" restrictions on banks' risk-taking. Goldman Sachs (GS +4.59%), Wells Fargo (WFC +4.79%) and JPMorgan Chase (JPM +3.49%) led major indexes higher.
However, in after-market hours, the Federal Reserve, in anticipation of a prolonged economic downturn, announced measures to bar the nation's biggest banks from buying back their own stocks or increasing dividend payments in the third quarter.
On the technical side, about 36.7% (43.1% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 13.5% (35.3% in the prior session) were trading above their 20-day moving average.
The U.S. Labor Department reported that Initial Jobless Claims decreased to 1.480 million for the week ended June 20 (1.320 million expected) and Continuing Claims slid to 19.522 million for the week ended June 13 (20.000 million expected).
And the Commerce Department said first-quarter GDP contracted 5.0% on quarter annualized (as expected), and Durable Goods Orders (preliminary reading) jumped 15.8% on month in May (+10.5% expected).
Due later today are reports on May Personal Income (-6.0% on month expected), Personal Spending (+9.0% expected), and the University of Michigan's Consumer Sentiment Index (a rise to 79.2 in June expected).
European stocks were broadly higher. The Stoxx Europe 600 Index climbed 0.7%, Germany's DAX rose 0.7%, France's CAC jumped 1.0%, and the U.K.'s FTSE 100 was up 0.4%.
U.S. government bond prices remained firm, as the benchmark 10-year Treasury yield dropped further to 0.670% from 0.683% Wednesday.
Spot gold price added $2.00 (+0.1%) to $1,763 an ounce.
Oil prices stabilized after losing for two sessions. WTI crude oil futures (August) increased 1.9% to $38.72 a barrel.
On the forex front, the ICE U.S. Dollar Index climbed 0.2% on day to 97.39, up for a second straight session. The Federal Reserve released the results of its stress tests, stating: ""The banking system has been a source of strength during this crisis, and the results of our sensitivity analyses show that our banks can remain strong in the face of even the harshest shocks."
EUR/USD fell 0.3% to 1.1220. Germany's GfK Consumer Confidence Index for July improved to -9.6 (-12.0 expected) from -18.6 in June.
GBP/USD was little changed at 1.2424.
USD/JPY edged up 0.1% to 107.18. This morning, official data showed that Japan's Tokyo CPI grew 0.3% on year in June (as expected).
On Thursday, U.S. stocks rebounded making most of the gains in the last trading hour. The Dow Jones Industrial Average rose 299 points (+1.18%) to 25745, the S&P 500 gained 33 points (+1.10%) to 3083, and the Nasdaq 100 was up 99 points (+0.99%) to 10101.
S&P 500 Index: Daily Chart
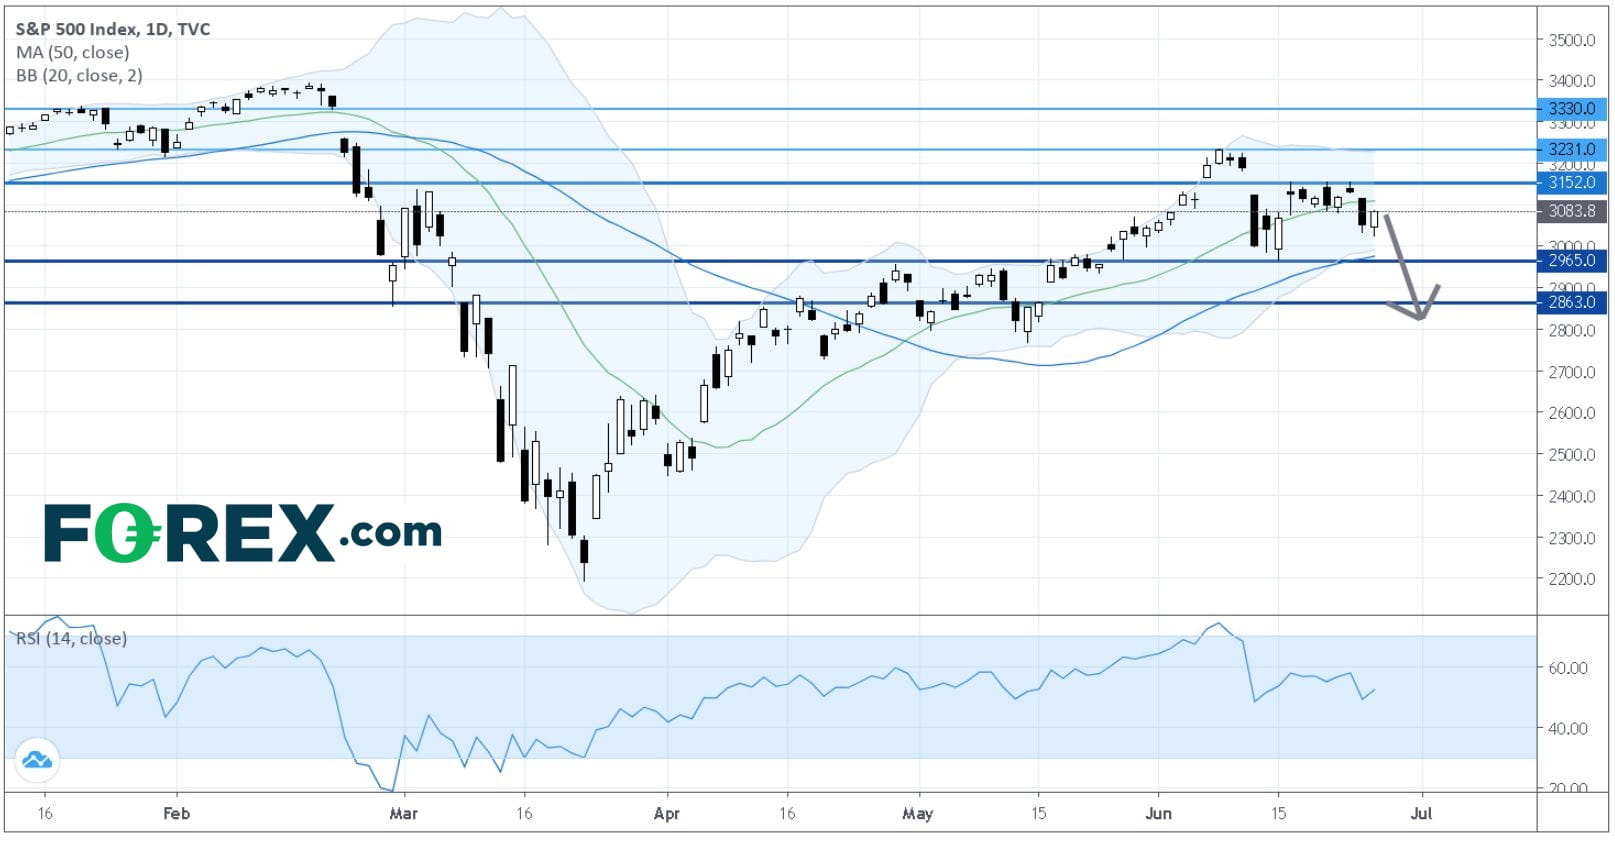
Source: GAIN Captial, TradingView
Banks (+3.57%), Insurance (+2.55%) and Diversified Financials (+2.07%) sectors gained the most after financial regulators eased up "Volcker Rule" restrictions on banks' risk-taking. Goldman Sachs (GS +4.59%), Wells Fargo (WFC +4.79%) and JPMorgan Chase (JPM +3.49%) led major indexes higher.
However, in after-market hours, the Federal Reserve, in anticipation of a prolonged economic downturn, announced measures to bar the nation's biggest banks from buying back their own stocks or increasing dividend payments in the third quarter.
On the technical side, about 36.7% (43.1% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 13.5% (35.3% in the prior session) were trading above their 20-day moving average.
The U.S. Labor Department reported that Initial Jobless Claims decreased to 1.480 million for the week ended June 20 (1.320 million expected) and Continuing Claims slid to 19.522 million for the week ended June 13 (20.000 million expected).
And the Commerce Department said first-quarter GDP contracted 5.0% on quarter annualized (as expected), and Durable Goods Orders (preliminary reading) jumped 15.8% on month in May (+10.5% expected).
Due later today are reports on May Personal Income (-6.0% on month expected), Personal Spending (+9.0% expected), and the University of Michigan's Consumer Sentiment Index (a rise to 79.2 in June expected).
European stocks were broadly higher. The Stoxx Europe 600 Index climbed 0.7%, Germany's DAX rose 0.7%, France's CAC jumped 1.0%, and the U.K.'s FTSE 100 was up 0.4%.
U.S. government bond prices remained firm, as the benchmark 10-year Treasury yield dropped further to 0.670% from 0.683% Wednesday.
Spot gold price added $2.00 (+0.1%) to $1,763 an ounce.
Oil prices stabilized after losing for two sessions. WTI crude oil futures (August) increased 1.9% to $38.72 a barrel.
On the forex front, the ICE U.S. Dollar Index climbed 0.2% on day to 97.39, up for a second straight session. The Federal Reserve released the results of its stress tests, stating: ""The banking system has been a source of strength during this crisis, and the results of our sensitivity analyses show that our banks can remain strong in the face of even the harshest shocks."
EUR/USD fell 0.3% to 1.1220. Germany's GfK Consumer Confidence Index for July improved to -9.6 (-12.0 expected) from -18.6 in June.
GBP/USD was little changed at 1.2424.
USD/JPY edged up 0.1% to 107.18. This morning, official data showed that Japan's Tokyo CPI grew 0.3% on year in June (as expected).
S&P 500 Index: Daily Chart
Source: GAIN Captial, TradingView
Banks (+3.57%), Insurance (+2.55%) and Diversified Financials (+2.07%) sectors gained the most after financial regulators eased up "Volcker Rule" restrictions on banks' risk-taking. Goldman Sachs (GS +4.59%), Wells Fargo (WFC +4.79%) and JPMorgan Chase (JPM +3.49%) led major indexes higher.
However, in after-market hours, the Federal Reserve, in anticipation of a prolonged economic downturn, announced measures to bar the nation's biggest banks from buying back their own stocks or increasing dividend payments in the third quarter.
On the technical side, about 36.7% (43.1% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 13.5% (35.3% in the prior session) were trading above their 20-day moving average.
The U.S. Labor Department reported that Initial Jobless Claims decreased to 1.480 million for the week ended June 20 (1.320 million expected) and Continuing Claims slid to 19.522 million for the week ended June 13 (20.000 million expected).
And the Commerce Department said first-quarter GDP contracted 5.0% on quarter annualized (as expected), and Durable Goods Orders (preliminary reading) jumped 15.8% on month in May (+10.5% expected).
Due later today are reports on May Personal Income (-6.0% on month expected), Personal Spending (+9.0% expected), and the University of Michigan's Consumer Sentiment Index (a rise to 79.2 in June expected).
European stocks were broadly higher. The Stoxx Europe 600 Index climbed 0.7%, Germany's DAX rose 0.7%, France's CAC jumped 1.0%, and the U.K.'s FTSE 100 was up 0.4%.
U.S. government bond prices remained firm, as the benchmark 10-year Treasury yield dropped further to 0.670% from 0.683% Wednesday.
Spot gold price added $2.00 (+0.1%) to $1,763 an ounce.
Oil prices stabilized after losing for two sessions. WTI crude oil futures (August) increased 1.9% to $38.72 a barrel.
On the forex front, the ICE U.S. Dollar Index climbed 0.2% on day to 97.39, up for a second straight session. The Federal Reserve released the results of its stress tests, stating: ""The banking system has been a source of strength during this crisis, and the results of our sensitivity analyses show that our banks can remain strong in the face of even the harshest shocks."
EUR/USD fell 0.3% to 1.1220. Germany's GfK Consumer Confidence Index for July improved to -9.6 (-12.0 expected) from -18.6 in June.
GBP/USD was little changed at 1.2424.
USD/JPY edged up 0.1% to 107.18. This morning, official data showed that Japan's Tokyo CPI grew 0.3% on year in June (as expected).
Related tags:


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

NZD/USD pressure mounts as payrolls looms large
NZD/USD has fallen sharply as Fed rate expectations reset higher, but extreme downside stretch and major support raise the risk of a violent counter-trend rebound.

US Core PCE Preview: Stale or Significant for the Fed
Core PCE inflation takes center stage Wednesday, with traders watching for signs of renewed price pressure and clues on whether the Fed could hike again in October.

Australian Dollar Forecast: AUD/USD Four-Week Slide Nears Critical Uptrend Support 9 29 2026
Aussie momentum has deteriorated sharply into quarter-end, with inflation, Core PCE and NFP on tap as AUD/USD closes in on a pivotal technical threshold.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.