



ASX200 Afternoon Report July 20th 2022
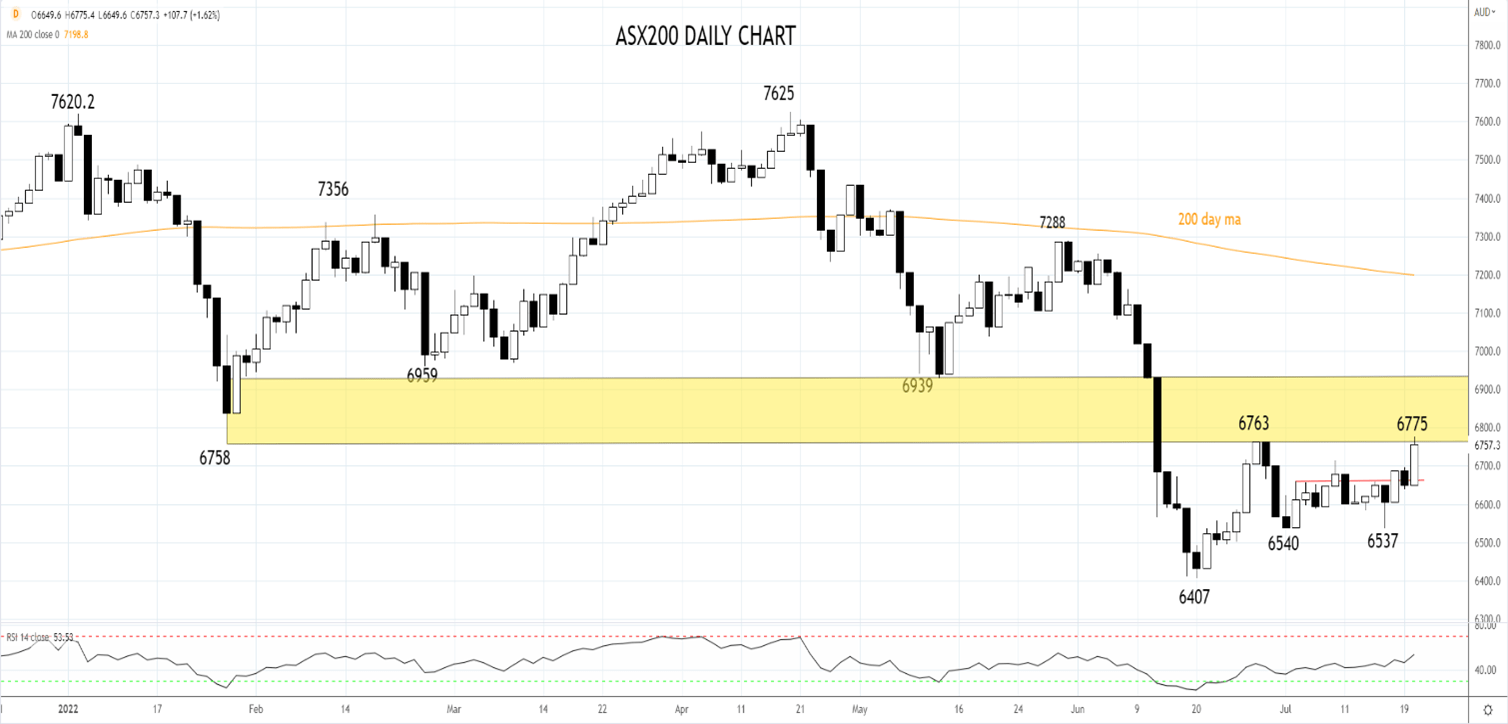
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
Share this:

This content will only appear on City Index websites!
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
After a promising start to the new week ended in disappointment yesterday, the ASX200 has today traded to its highest level in five weeks at 6775.4, supported by a robust overnight session on Wallstreet.
The rally on Wallstreet follows apparent confirmation that gas supply to Europe via the Nord Stream 1 would soon resume. And better-than-expected U.S Q2 earnings reports that have (for now) eased concerns over an imminent slowdown.
The high beta tech sector has led the rampage higher, with Megaport the best on ground, adding 23% to $7.95 after the company reported EBITDA profit in Q4 for the first time. Elsewhere, ZIP added 11% to $0.66c, Tyro Payments added 7.5% to $0.71c. Appen added 6.6% to $6.28 and Wisetech Global added 5.5% to $44.43.
Looking to snap a six-week losing streak, the Materials Sector added 2.36%. Mineral Resources added 5.25% to $47.54, FMG added 4.76% to 4.64, South32 added 4.12% to $3.54 while index heavyweight BHP added 1.94% to $37.72
Gains also for Consumer Discretionary stocks following a bumper trading update from J.B. Hi-Fi yesterday. JB Hi-Fi added 4.5% to $43.64, Harvey Norman added 4.2% to $4.20. Flight Centre added 2.6% to $17.66, Wesfarmers added 1.7% to $46.92 and Webjet added 2% to $5.45.
Bank stocks have benefitted from a continued rebound in the U.S. banking sector and after Westpac bumped higher both its fixed and variable rates. Macquarie added 4.46% to $174.30, Westpac added 1.4% to $20.59, CBA added 1.2% to $96.07 and NAB added 0.7% to $29.26. The ANZ shares remain in a trading halt as it finalised its book build to buy Suncorp.
In the Lithium space, it was Liontown Resource's turn to notch double-digit gains as it climbed 10% to $1.12. Galan Resources added 8% to $1.07, Iluka Resources added 6.7% to $9.21, Core Lithium added 5.4% to $0.98, Pilbara added 4% to $2.46
Turning to the charts, the ASX200 has edged into the bottom of a resistance band between 6750/6950 that it needs to recover above to negate the technical damage caused by the breakdown in June. Until this occurs, the rally from the 6407 low is viewed as a bear market rally.
Source Tradingview. The figures stated are as of July 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 trades 105 points higher at 6755 at 3.15 pm Sydney time with all sectors in the green.
After a promising start to the new week ended in disappointment yesterday, the ASX200 has today traded to its highest level in five weeks at 6775.4, supported by a robust overnight session on Wallstreet.
The rally on Wallstreet follows apparent confirmation that gas supply to Europe via the Nord Stream 1 would soon resume. And better-than-expected U.S Q2 earnings reports that have (for now) eased concerns over an imminent slowdown.
The high beta tech sector has led the rampage higher, with Megaport the best on ground, adding 23% to $7.95 after the company reported EBITDA profit in Q4 for the first time. Elsewhere, ZIP added 11% to $0.66c, Tyro Payments added 7.5% to $0.71c. Appen added 6.6% to $6.28 and Wisetech Global added 5.5% to $44.43.
Looking to snap a six-week losing streak, the Materials Sector added 2.36%. Mineral Resources added 5.25% to $47.54, FMG added 4.76% to 4.64, South32 added 4.12% to $3.54 while index heavyweight BHP added 1.94% to $37.72
Gains also for Consumer Discretionary stocks following a bumper trading update from J.B. Hi-Fi yesterday. JB Hi-Fi added 4.5% to $43.64, Harvey Norman added 4.2% to $4.20. Flight Centre added 2.6% to $17.66, Wesfarmers added 1.7% to $46.92 and Webjet added 2% to $5.45.
Bank stocks have benefitted from a continued rebound in the U.S. banking sector and after Westpac bumped higher both its fixed and variable rates. Macquarie added 4.46% to $174.30, Westpac added 1.4% to $20.59, CBA added 1.2% to $96.07 and NAB added 0.7% to $29.26. The ANZ shares remain in a trading halt as it finalised its book build to buy Suncorp.
In the Lithium space, it was Liontown Resource's turn to notch double-digit gains as it climbed 10% to $1.12. Galan Resources added 8% to $1.07, Iluka Resources added 6.7% to $9.21, Core Lithium added 5.4% to $0.98, Pilbara added 4% to $2.46
Turning to the charts, the ASX200 has edged into the bottom of a resistance band between 6750/6950 that it needs to recover above to negate the technical damage caused by the breakdown in June. Until this occurs, the rally from the 6407 low is viewed as a bear market rally.
Source Tradingview. The figures stated are as of July 20th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

Nikkei threatens breakout as tech rebound broadens
Breakouts across the SOX and Nasdaq are being matched by rebounds across Asia, with the Nikkei now threatening to join the move.


Nasdaq 100 Forecast: Confidence Returns as the Index Challenges Record Highs
The trading week is getting underway with renewed bullish momentum across Nasdaq. This is reflected in today's session, where the index has gained more than 2.5%, highlighting a buying bias that has not been observed with this level of strength in several weeks.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.