



Crude up despite worst Chinese GDP showing in 30 years
At the time of writing, both contracts were still probing their session highs but remained marginally lower on the week.
Share this:

In the previous week, oil prices had ended a three-week losing streak but there was no immediate bullish follow-through as this week got underway. But oil prices have pared their weekly losses, with both Brent and WTI rising noticeably on Thursday before adding to their gains on Friday morning despite a poor Chinese GDP report. At the time of writing, both contracts were still probing their session highs but remained marginally lower on the week.
In other words, oil prices have stabilised over the past couple of weeks. During this period, we have also seen equity prices rise noticeably as a result of optimism over the US-China trade situation and Brexit. So, the gains can be partially explained away by improved risk appetite as a trade deal is seen as being positive for the Chinese and global economies, and in turn demand for oil.
China, which is the world’s second largest economy, expanded at its slowest pace since the early 1990s last quarter, according to official data released on Friday. While this provides more evidence that the trade war is taking a toll on growth, the more up-to-date data showed industrial production rose a surprisingly large 5.8% y/y rise last month when expectations were for a smaller 5.0% increase. Industrial output has therefore grown at a faster pace for the first time in three months but remains to be seen whether this spike is just an outlier (like in the case of March and June) or the start of something more profound.
From the supply-side of things, news that US crude oil inventories climbed last week by the most in almost six months suggests supply remains plentiful here. Further sharp increases in crude stocks, if seen, may keep price gains in check, although ongoing intervention from the OPEC+ group means the downside will be limited as well. So, overall, we are talking about a range-bound market, but with prices being near the range lows, the probability of a several-dollar rally has now increased.
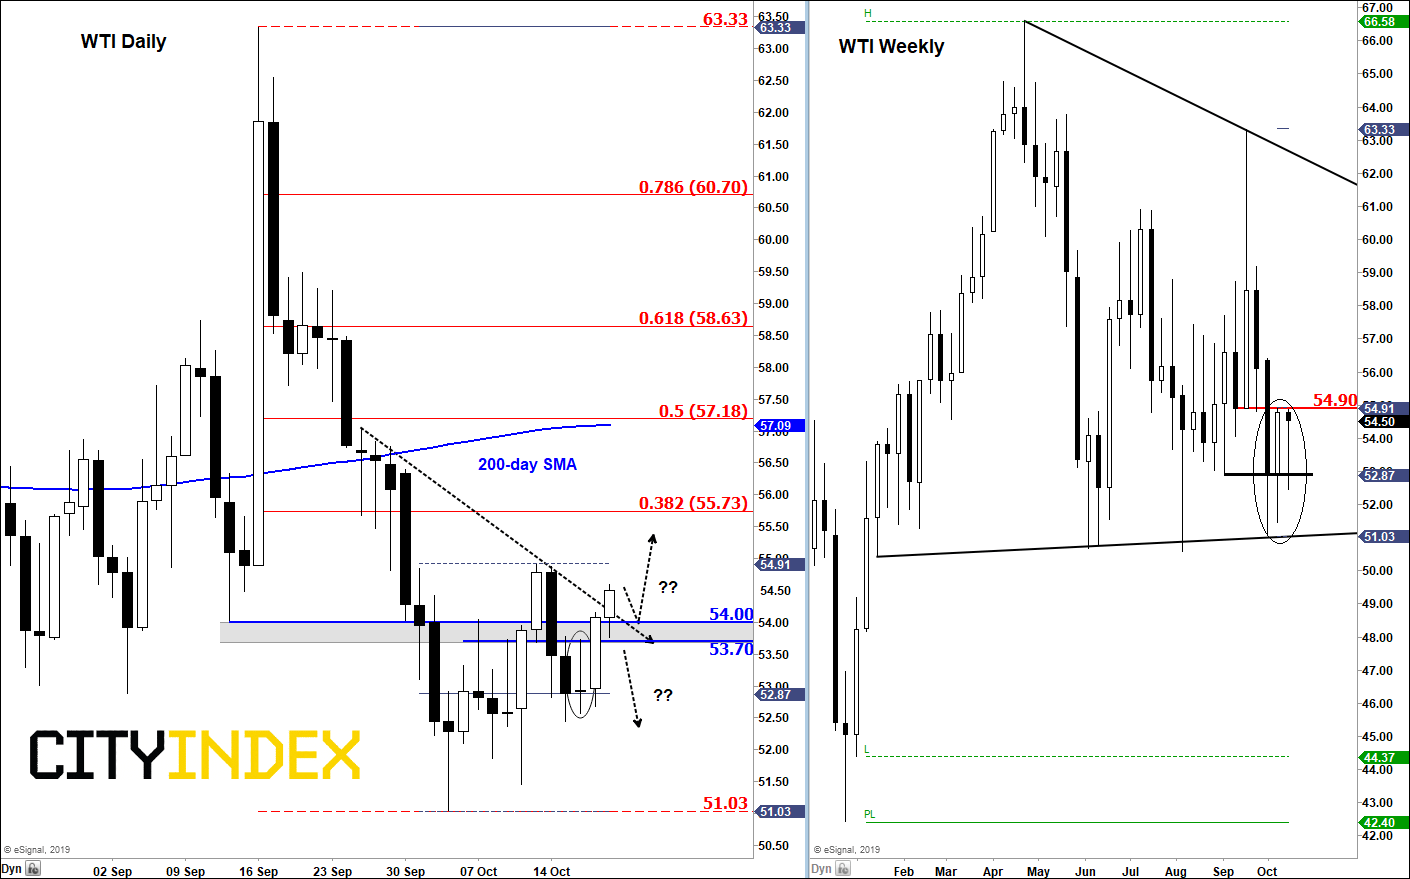
From a technical point of view, the fact that WTI has broken above the 53.70-54.00 resistance range is bullish. But more work is needed from the bulls. They need to push prices above sturdy resistance in the $54.90-$55.00 range to trigger fresh buying interest. Otherwise, there is a risk that today’s gains could evaporate as we head towards the second half of the day.
Source: eSignal and City Index.
In the previous week, oil prices had ended a three-week losing streak but there was no immediate bullish follow-through as this week got underway. But oil prices have pared their weekly losses, with both Brent and WTI rising noticeably on Thursday before adding to their gains on Friday morning despite a poor Chinese GDP report. At the time of writing, both contracts were still probing their session highs but remained marginally lower on the week.
In other words, oil prices have stabilised over the past couple of weeks. During this period, we have also seen equity prices rise noticeably as a result of optimism over the US-China trade situation and Brexit. So, the gains can be partially explained away by improved risk appetite as a trade deal is seen as being positive for the Chinese and global economies, and in turn demand for oil.
China, which is the world’s second largest economy, expanded at its slowest pace since the early 1990s last quarter, according to official data released on Friday. While this provides more evidence that the trade war is taking a toll on growth, the more up-to-date data showed industrial production rose a surprisingly large 5.8% y/y rise last month when expectations were for a smaller 5.0% increase. Industrial output has therefore grown at a faster pace for the first time in three months but remains to be seen whether this spike is just an outlier (like in the case of March and June) or the start of something more profound.
From the supply-side of things, news that US crude oil inventories climbed last week by the most in almost six months suggests supply remains plentiful here. Further sharp increases in crude stocks, if seen, may keep price gains in check, although ongoing intervention from the OPEC+ group means the downside will be limited as well. So, overall, we are talking about a range-bound market, but with prices being near the range lows, the probability of a several-dollar rally has now increased.
From a technical point of view, the fact that WTI has broken above the 53.70-54.00 resistance range is bullish. But more work is needed from the bulls. They need to push prices above sturdy resistance in the $54.90-$55.00 range to trigger fresh buying interest. Otherwise, there is a risk that today’s gains could evaporate as we head towards the second half of the day.

Source: eSignal and FOREX.com.
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Wall Street Forecast: DJIA rises on hawkish Fed expectations & rising yields
U.S. stocks are opening lower on Wednesday, pressured by higher crude oil prices and rising government bond yields, as investors await further developments from negotiations in the Middle East and ahead of a key U.S.-China summit.


Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.

Crude and dollar rebound as Trump says deal possible after the election
Donald Trump’s speech at the UN seems to have poured cold waters on any hopes of a deal. Crude oil, the US dollar and bond yields all bounced back from their lows, causing fresh pressure on foreign currencies, European indices and to a lesser degree precious metals.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.