


DAX under pressure: US inflation will now decide the outcome
The DAX correction now has little to do with corporate news. Rising oil prices, higher bond yields, and the prospect of further interest rate hikes are dominating market activity. Following the strong US PPI report, all focus is now on today's US CPI. The figures could determine whether the current risk-off phase continues or whether the markets can launch a short-term relief rally.
Share this:
DAX Market Letter: US Inflation on the Agenda
Friday, September 11, 2026
DAX starts recovery attempt after sell-off
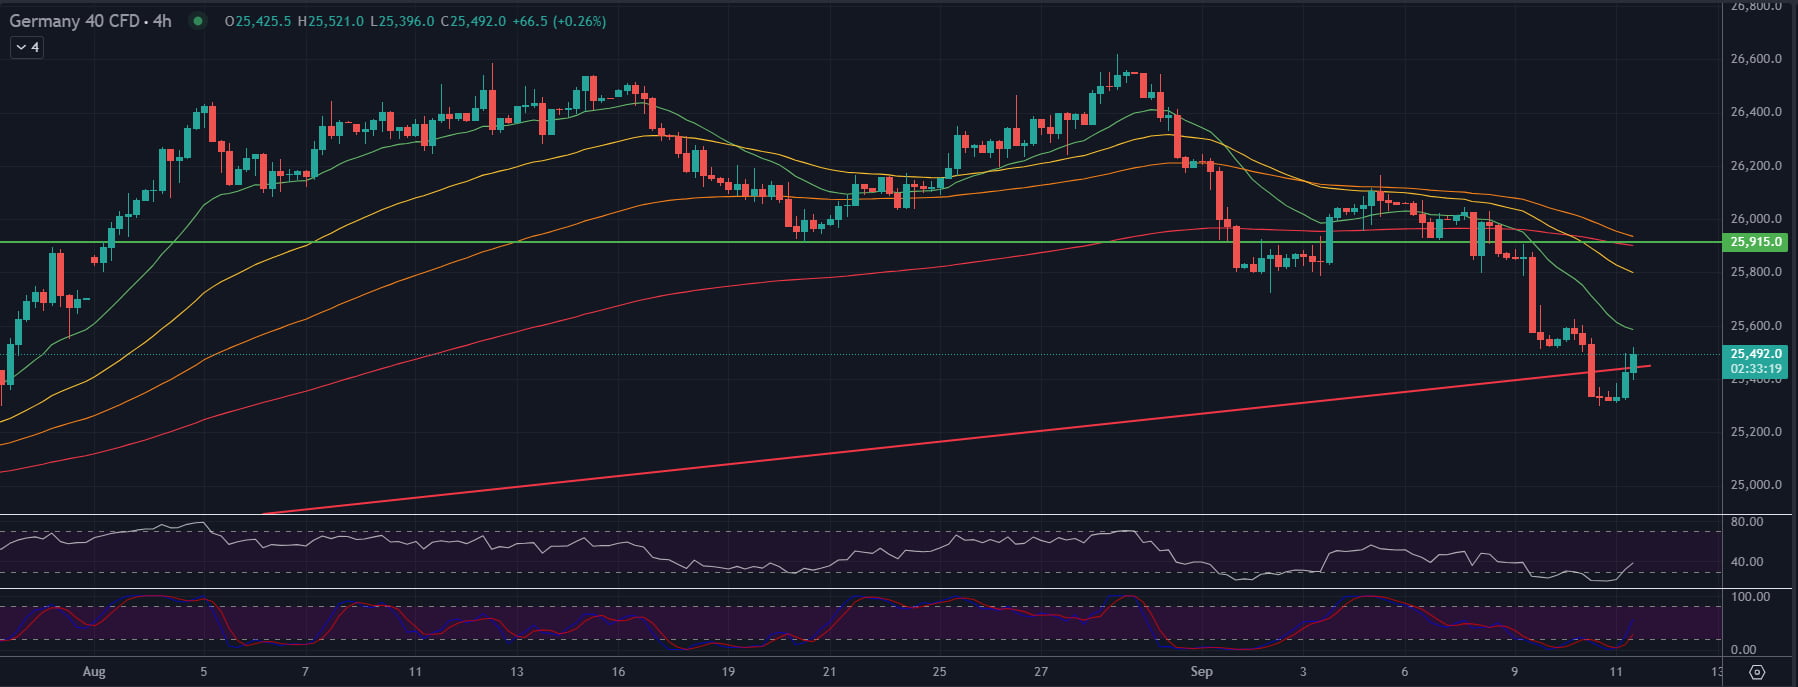
After Thursday's significant drop, the DAX entered Friday with a cautiously more stable starting position. The leading index lost 0.84% on Thursday, closing at 25,361 points . This leaves the DAX down approximately 2.6% for the week .
The decline is primarily due to a combination of rising oil prices, higher bond yields, and an increasingly restrictive monetary policy . At the same time, the Middle East conflict remains the most significant geopolitical risk factor.
The DAX is likely to attempt to stabilize today. However, the decisive impetus will only come from the US in the afternoon.
The US CPI is the most important event of the day.
The US consumer price index for August will be released at 2:30 PM CEST . Current forecasts predict monthly inflation of +0.4% and an annual rate of approximately 3.4% . Core inflation is expected to rise by 0.2% month-over-month and 2.4% year-over-year .
Because the figures are published immediately before the next Fed meeting,
the data is particularly important.
Even after the strong US producer price report released on Thursday, pressure on the Federal Reserve has increased further, as the PPI rose by 0.4% in August compared to the previous month and 5.4% compared to the previous year .
The probability of a Fed interest rate hike of 25 basis points at the meeting on September 15/16 has now increased to around 70–71% .
Three scenarios for the DAX
The CPI is significantly above expectations:
US yields are likely to rise, and expectations for interest rate hikes are expected to increase further. This would be negative for the Nasdaq and DAX.
The CPI is roughly in line with consensus:
The market could initially digest the recent increases in yields. The DAX has potential for a technical rebound.
Significantly lower CPI:
Falling yields and a weaker dollar would provide a clear boost to growth stocks. The DAX could then recover a larger portion of its weekly losses.
ECB raises interest rates – oil remains the problem
The ECB raised its key interest rate by 25 basis points to 2.50% on Thursday, as expected . At the same time, the central bank signaled that high energy prices continue to weigh on inflation.
Markets now have to consider a scenario in which both the ECB and the Fed could raise interest rates further .
Brent is now trading above $105 per barrel after geopolitical tensions in the Middle East heightened concerns about global energy supplies.
This creates a problematic cycle:
Higher oil prices → higher inflation → higher interest rates → higher returns → lower stock valuations.
Bond yields are becoming a burden factor
The yield on 10-year US Treasury bonds is now around 4.95% , after a significant recent rise. This brings it once again approaching the psychologically important 5% mark, a high of more than 20 years.
This is relevant for the stock market because higher risk-free returns reduce the relative attractiveness of stocks.
Highly valued technology and growth companies are particularly affected.
The yield on German Bunds is also important for the DAX. It, too, is at a level that is becoming increasingly unfavorable for European stocks.
DAX stocks in focus
Yesterday's trading showed a broad wave of selling.
winner
Deutsche Börse was the strongest performer in the DAX, rising 2.19% . Deutsche Telekom, Munich Re, Hannover Re, and Rheinmetall also posted gains.
loser
Particularly weak were SAP (-2.76%), Siemens (-2.38%), Siemens Energy (-2.98%), Infineon (-2.02%) and adidas (-2.56%) .
The weakness of SAP and Siemens is particularly relevant for the index. Both companies are among the most important holdings in the DAX.
Rheinmetall 's geopolitical situation remains generally supportive. At the same time, the stock withstood the widespread sell-off on Thursday relatively well.
DAX Outlook
The DAX is currently undergoing a clear short-term correction. Since its record high at the end of August, the index has lost approximately 4.7% .
Technically, the momentum has clearly weakened.
Three factors are crucial for today:
1. US CPI: The most important short-term trigger.
2. US 10Y yield: A sustained increase towards or above 5% would be another warning signal.
3. Oil price: Brent above $100 keeps inflationary pressure high.
Conclusion
The short-term bias remains bearish to neutral .
After the sharp sell-off, a technical rebound is always possible. However, for a sustained rebound, the market will likely need support from a weaker US CPI and falling bond yields .
A hot inflation report, on the other hand, would exacerbate the current problem: higher oil prices, higher inflation, higher interest rates and falling stock valuations.
This means that today at 2:30 pm , the direction of the DAX will not be decided by the German corporate landscape, but by US inflation.
Von Philip J Papageorgiou - Leiter der Marktforschung
Finde ihn auf X (x twitter) - PhilipForexCom
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rises as oil prices fall, but treasuries remain at multi-decade highs
U.S. stocks are rising on Friday after a volatile week that saw a surge in Treasury yields ripple through financial markets.


Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.