



Dow Jones Forecast: DJIA steady after hitting a record closing high
U.S. futures are pointing to a muted open on the final trading day of the month, quarter and first half of the year after the Dow Jones achieved a record closing high on Monday.
Share this:
US futures
Dow futures 0.19%, S&P futures 0.13% & Nasdaq futures 0.13%
In Europe
FTSE 0.88% & DAX 1.2%
- U.S futures are muted after strong gains yesterday
- The DJIA outperformed the Nasdaq in June
- Nike reports after the close
- Oil falls 20% in June as supply fears ease
U.S. futures are muted at the end of the month, quarter, and half-year
U.S. futures are pointing to a muted open on the final trading day of the month, quarter and first half of the year after the Dow Jones closed at a record high.
The Dow rose 0.6% on Monday to close above the 52,000 level for the first time, helped by a near 5% rally in Alphabet during the company's first trading session as a Dow component.
The Dow outperformed its tech-heavy counterpart in June, rising 2.25% compared with a 4% decline in the Nasdaq. The divergence highlights a rotation away from high-growth technology stocks and into more defensive areas of the market.
While AI remains a long-term structural growth theme, investors are becoming increasingly focused on valuations and whether the enormous investment in AI infrastructure will translate into earnings growth quickly enough to justify current share prices. At the same time, a more hawkish Federal Reserve has weighed on high growth stocks.
Markets are currently pricing around a 60% probability of a 25-basis-point rate hike in September, with some investors also seeing scope for up to three rate hikes this year.
Attention this week will be on Federal Reserve Chair Kevin Warsh's speech at the ECB Sintra Forum, as well as Thursday's U.S. non-farm payroll report, both of which could provide further clues over the outlook for U.S. interest rates.
Ahead of that, today's JOLTS job openings and Consumer Confidence figures will provide further insight into the resilience of the U.S. labour market.
Investors also welcomed the U.S. Supreme Court's decision allowing Federal Reserve Governor Lisa Cook to remain in her post while legal proceedings continue. The ruling removes a degree of uncertainty surrounding the Fed's independence at a time when markets remain highly focused on monetary policy.
Elsewhere, oil prices are edging lower after reports that a U.S. envoy is travelling to Qatar for talks with Iran, although Tehran has yet to confirm the discussions.
Corporate Movers
Nike is in focus ahead of earnings after the closing bell. In March, the company warned that current-quarter sales would decline between 2% and 4%, reflecting weaker demand across key markets including Greater China, Europe, the Middle East and Africa. Investors will be looking for signs that inventory normalisation and Elliott Hill's turnaround strategy are beginning to gain traction.
Dow Jones Forecast – Technical Analysis
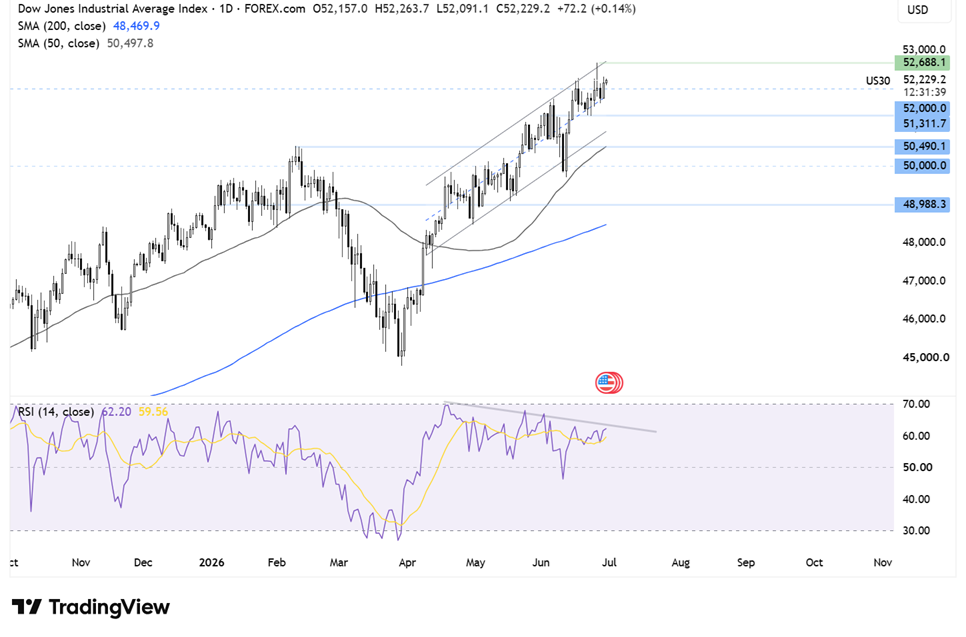
The Dow Jones continues to trade within an ascending channel dating back to April, rising to a fresh closing high around 52,300.
However, bearish RSI divergence suggests upside momentum is beginning to fade despite prices making fresh highs.
Buyers will look to extend gains towards 52,670, the record high and the upper boundary of the rising channel. Above there, 53,000 becomes the next psychological target.
Immediate support is seen at 51,300, last week's low. A break below here exposes the lower boundary of the rising channel around 50,870, ahead of the 50-day SMA near 50,500. A break below the 50,000 support zone would suggest the recent uptrend is beginning to lose momentum.
FX Markets – USD Holds Firm
The U.S. dollar is holding onto recent gains after rising 1.4% during the second quarter, building on a 1.6% advance in the first quarter. The greenback continues to be supported by expectations that the Federal Reserve will raise interest rates later this year.
Attention now turns to Fed Chair Kevin Walsh's speech and Thursday's non-farm payroll report, which could shape expectations for the Fed's next move.
EUR/USD remains under pressure around 1.1400 despite stronger-than-expected German retail sales. Sales rose 1.1% year-on-year in May and rebounded 1.1% month-on-month after April's decline, comfortably beating expectations. Attention now turns to German inflation data later today.
USD/JPY has climbed to a 40-year high, putting the yen firmly on intervention watch. Expectations of further Fed tightening continue to widen the U.S.-Japan yield differential, supporting the carry trade and keeping the yen under pressure despite the Bank of Japan's recent rate hike.
Oil Falls 20% in June
Oil prices are slipping around 1% on Tuesday after reversing yesterday's gains and remain on course for their largest monthly decline in years.
Both Brent and WTI have fallen around 20% during June and are now trading close to pre-conflict levels as investors continue to price in a positive outcome from U.S.-Iran talks in Doha and a gradual recovery in crude flows through the Strait of Hormuz.
However, the ceasefire remains fragile following the recent flare-up in hostilities over the weekend, meaning some geopolitical risk premium is likely to remain in prices.
On the demand side, Chinese data overnight was encouraging. Even so, crude imports remain subdued, suggesting demand from the world's largest oil importer has yet to recover meaningfully.
Latest market news


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Wall Street Forecast: DJIA rises on hawkish Fed expectations & rising yields
U.S. stocks are opening lower on Wednesday, pressured by higher crude oil prices and rising government bond yields, as investors await further developments from negotiations in the Middle East and ahead of a key U.S.-China summit.

Why Crude Oil Slid While Middle East Tensions Kept Building
The crude oil pullback from monthly highs is running ahead of the headlines, as WTI and Brent ease while Middle East tensions stay unresolved.

Crude and dollar rebound as Trump says deal possible after the election
Donald Trump’s speech at the UN seems to have poured cold waters on any hopes of a deal. Crude oil, the US dollar and bond yields all bounced back from their lows, causing fresh pressure on foreign currencies, European indices and to a lesser degree precious metals.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.